Tag Archives: accounting

Why Most Cannabis COGS Would Fail an Audit — and How Operators Can Fix It

By David Kay, CPA, CMA, CFE
No Comments

For cannabis operators, the cost of goods sold (COGS) is far more than an accounting line item.  It’s the most critical financial number in the entire business.

Under IRC Section 280E, most ordinary business deductions are disallowed, making COGS the primary mechanism for reducing taxable income.  At the same time, COGS drives pricing decisions, product profitability analysis, capital investment planning, and ultimately enterprise value.

Yet in practice, many cannabis operators run COGS systems that would struggle to withstand audit scrutiny—and even more concerning, fail to reflect the true economic cost of producing their products.

The result is dual exposure: elevated tax risk on one side, and distorted business decision-making on the other.

COGS Defensibility Is Not an “Aggressive Tax Strategy”

A common misconception about cannabis is that maximizing COGS is primarily a tax exercise.  Operators often focus on what they believe can be included rather than what can be consistently substantiated, documented, and operationally supported.

True COGS defensibility rests on four pillars:

  1. Substantiation – Can each cost be supported by payroll records, invoices, time tracking, inventory movements, and production documentation?
  2. Consistency – Are allocation methodologies applied the same way, period after period?
  3. Traceability – Can costs be directly tied to physical production activities and inventory flows?
  4. Operational alignment – Do accounting numbers reflect how the facility actually operates?

When any of these pillars are weak, audit exposure increases — and financial insight deteriorates.

Importantly, defensible COGS isn’t only about minimizing tax liability.  Accurate costing enables operators to understand true unit economics, identify profitable SKUs, set pricing intelligently, evaluate yield performance, and allocate capital effectively.  Tax optimization becomes a byproduct of operational discipline rather than a risky accounting maneuver.


Why IRS Scrutiny Is Increasing — Not Decreasing

Some operators assume that potential federal rescheduling will materially reduce audit pressure or eliminate the importance of rigorous COGS practices.  That assumption is premature.

Even if cannabis ultimately moves to Schedule III, timing remains uncertain, implementation will take time, and open tax years will remain subject to existing 280E rules.  Historical returns remain examinable, and enforcement activity does not unwind retroactively.

At the same time:

  • The IRS has developed greater institutional knowledge of cannabis operations.
  • Digital payroll systems, banking records, and seed-to-sale data have improved audit visibility.
  • Prior enforcement cycles have highlighted recurring weaknesses in labor classification and inventory controls.

Audit standards are tightening, not loosening.

Where Most Cannabis COGS Break Down

Across cultivation, manufacturing, extraction, and retail operations, several failure patterns consistently appear.

Labor Misclassification

Production labor is often blended with administrative, compliance, or sales functions.  Without time studies, job costing, or consistent labor tracking, allocations become subjective and difficult to defend.

Unsupported Overhead Allocations

Facilities frequently allocate rent, utilities, depreciation, and indirect labor using informal spreadsheets or percentage assumptions that are not grounded in measurable production drivers.

Inventory Accuracy Gaps

Cycle counts are inconsistent.  Work-in-process tracking is incomplete.  Adjustments lack documentation.  Reconciliation between physical inventory, accounting systems, and seed-to-sale platforms is often weak.

Manual Processes and Spreadsheets

Critical cost calculations are often stored in individual spreadsheets with limited version control, audit trails, or governance.

Weak Documentation Culture

Standard operating procedures, allocation methodologies, and change management processes are rarely formalized.

Individually, these issues may seem manageable.  Collectively, they undermine both audit defensibility and business intelligence.

Seed-to-Sale Systems Are Not Cost Accounting Systems

State-mandated seed-to-sale platforms were designed primarily for regulatory traceability, not financial accuracy.  They track weights, transfers, and compliance events, but they don’t calculate labor absorption, overhead allocation, yield efficiency, or true unit economics.

Operators often assume that because inventory exists in the seed-to-sale process, COGS must therefore be accurate.  That assumption is incorrect.

Seed-to-sale data must be reconciled and integrated into accounting systems using disciplined costing logic before it becomes financially reliable.

Why COGS Accuracy Improves Business Performance

Defensible COGS delivers far more than tax protection.

When costs are properly captured and allocated, operators gain:

  • Accurate SKU profitability – Identifying which products truly drive margin versus consume resources.
  • Pricing discipline – Setting prices based on real cost structures rather than market guesswork.
  • Yield optimization insight – Revealing where losses, rework, or inefficiencies erode margin.
  • Capital allocation clarity – Understanding which processes justify automation or expansion.
  • Financial credibility – Strengthening lender confidence, investor trust, and exit readiness.

In short, accurate costing becomes a management tool, not just a compliance requirement.

What Defensible COGS Looks Like in Practice

High-performing operators increasingly implement:

  • Time tracking and labor studies to support production labor classification.
  • Bills of material and routings to establish standard production models.
  • Documented allocation methodologies tied to measurable operational drivers.
  • Routine cycle counts and reconciliations across physical inventory, accounting records, and seed-to-sale systems.
  • Formal SOPs and change controls governing costing logic.
  • Automated accounting workflows to reduce spreadsheet dependency and strengthen audit trails.

These controls improve both audit readiness and operational clarity.

Practical Steps Operators Can Take Now

Operators don’t need enterprise-scale systems to materially improve COGS integrity.  Several foundational actions create immediate value:

  1. Document current labor classifications and identify inconsistencies.
  2. Validate overhead allocation logic against real production drivers.
  3. Implement regular inventory cycle counts with reconciliation discipline.
  4. Standardize cost calculation templates with version control.
  5. Formalize costing policies and assumptions in writing.
  6. Reconcile seed-to-sale quantities to accounting balances monthly.
  7. Treat COGS as a management system, not merely a tax calculation.

The Bottom Line

Most cannabis operators do not fail COGS audits because of aggressive intent.  They fail because their systems, documentation, and operational alignment are not mature enough to support the numbers they report.

Building defensible COGS strengthens tax compliance, improves decision quality, enhances financial credibility, and positions the business for sustainable profitability and long-term value.

In an industry facing margin compression, capital pressure, and increasing regulatory scrutiny, accurate cost intelligence is no longer optional.  It’s strategic infrastructure.
 

How ESOPs Can Save Cannabis Businesses A Ton of Money While Doing Good

By Darren Gleeman
No Comments

What most people don’t realize is that there is an entirely legal, proven way to increase a company’s profit margins. It’s called an Employee Stock Ownership Plan, or ESOP.

In cannabis, it sometimes feels like every financial conversation ends the same way: “If not for 280E, we’d be thriving.” That line gets repeated in boardrooms and investor decks across the country, and for good reason. Section 280E has choked margins, slowed growth, and kept great operators from building real wealth.

What most people don’t realize is that there is an entirely legal, proven way to increase a company’s bottom line. It’s called an Employee Stock Ownership Plan, or ESOP.

The problem is that when people in cannabis hear “ESOP,” they often imagine a maze of red tape, confusing tax rules, and loss of control. Some think it sounds too good to be true. Others assume it’s only for Fortune 500 companies.

None of that is accurate. ESOPs have been part of U.S. tax law for fifty years. They’ve been tested, audited, and refined by Congress and the IRS many times over. What’s new is how we’re applying them to cannabis.

Let’s separate fact from fiction.


Myth #1: ESOPs Are Too Complex for Cannabis Businesses

Fact: ESOPs aren’t complicated; they’re structured.

Complex doesn’t mean chaotic. The ESOP process is built on structure—specific steps, professional oversight, and a framework that’s been refined for decades. Cannabis operators already deal with licensing, banking, and compliance frameworks that make ESOP implementation look simple by comparison.

With the right team of advisors, setting up an ESOP is no more difficult than selling to a private equity group. The difference is that an ESOP retains the value within your company, rather than transferring it to outside investors.


Myth #2: You’ll Lose Control of Your Company

Fact: ESOPs are designed to be flexible. You decide how and when ownership changes hands.

An ESOP doesn’t take your company away overnight. It lets you sell shares over time, at your pace, while continuing to lead. You remain the CEO, set the strategic direction, and determine when, or if, you step back. Employees become shareholders, but they don’t manage the business day-to-day.


Think of it as succession planning with stability built in. You can gradually transfer ownership without losing control of what you built.


Myth #3: ESOPs Don’t Deliver Fair Market Value

Fact: The law requires ESOPs to pay fair market value, which independent valuation firms verify.

When you sell to an ESOP, the price is based on the same valuation principles used in mergers and acquisitions. There’s no “friends and family” discount. And because ESOPs qualify for capital gains deferral under Section 1042, sellers often end up with more after-tax value than they would in a traditional sale.

You’re selling to your employees, not giving the business away. The transaction adheres to the same financial standards as any other corporate transaction.


Myth #4: ESOPs Create Too Much Debt

Fact: ESOP debt is paid with pre-tax dollars, and it pays for itself, and if the company is 100% owned by an ESOP, the company pays zero income taxes

Unlike conventional debt, ESOP loans are self-liquidating. The company makes contributions to the ESOP trust, deducts them from taxable income, and those contributions repay the loan.

In cannabis, that’s a game changer. Under 280E, many companies lose 60 percent of their profits to taxes. With an ESOP, those profits stay in the business. The Gleeman Model eliminates the 280E burden entirely. With tax pressure lifted, operators can shift their focus from survival to strategy. The money that once went to the IRS can now be used to fund expansion, new equipment, or well-deserved bonuses for their teams.


Myth #5: ESOPs Only Work for Big Companies

Fact: Most ESOPs are small to mid-sized, founder-led businesses.

Across the U.S., the average ESOP company has between 50 and 200 employees. These are construction firms, food producers, and professional services businesses, not global corporations. They succeed because ESOPs align ownership with culture, giving employees a vested interest in the company’s success.

Cannabis companies with EBITDA exceeding $ 2.5 million are ideal candidates. These firms are entrepreneurial, closely held, and value legacy and employee retention. Those are the companies that benefit most from employee ownership.


Myth #6: Employees Can’t Handle Ownership

Fact: Ownership doesn’t mean management. It means alignment.

ESOP participants don’t vote on business strategy or day-to-day operations. They hold shares in a trust and earn value as the company’s value increases. That structure provides employees with a tangible reason to care about the company’s performance. When people have a genuine stake in the outcome, they pay closer attention to quality, take ownership of their work, and seek ways to improve efficiency.


Myth #7: ESOPs Don’t Work in Highly Regulated Industries

Fact: ESOPs were created to function in regulated environments.

They fall under the oversight of the Department of Labor and the IRS, and every plan undergoes an annual valuation and compliance review. In contrast to the constantly changing rules in cannabis, ESOPs offer a level of structure and predictability that’s rare in this industry.

They’ve worked for defense contractors, banks, and utilities—sectors with far tighter oversight than cannabis. The framework is clear, tested, and fully compliant with federal standards.


Myth #8: Selling to Private Equity Is Easier

Fact: Private equity is not necessarily faster, and it often comes at the cost of your culture.

Selling to private equity usually means an aggressive timeline, leveraged buyouts, and a complete change in leadership. ESOPs, on the other hand, let founders exit gradually, keep jobs local, and preserve the company’s mission.

Private equity is designed for short-term return. ESOPs aren’t built for quick wins. They’re built to last. The best structure for you comes down to what kind of business you want to leave behind and who you want it to serve when you’re gone.


Myth #9: ESOPs Don’t Offer Real Tax Benefits

Fact: No other ownership model comes close.

A 100 percent ESOP-owned S-Corporation pays no federal or state income tax. Ever. Sellers can defer capital gains indefinitely. Combined, these two features make ESOPs the most tax-efficient structure available.

For cannabis operators paying crushing 280E rates, that’s not a minor advantage; it’s a survival strategy. Freeing up that much cash flow can double profitability and open the door to expansion or acquisitions that once felt impossible.


Myth #10: ESOPs Are “Too Good to Be True”

Fact: They’re underused and misunderstood.

Thousands of American companies are owned by an ESOP, which, together, employs more than 14 million people. Think Publix, W.L. Gore, or New Belgium Brewing. All are proof that when employees share in ownership, companies tend to last longer and grow stronger.

The only reason ESOPs sound extraordinary is that most cannabis owners have never seen one in practice. However, the model has already been proven in more than 10 cannabis companies.


The Bottom Line

ESOPs aren’t a tax trick or an accounting loophole. They’re the product of decades of bipartisan legislation designed to reward broad ownership and long-term growth.

Skepticism is understandable, especially in cannabis, where operators are constantly warned to avoid anything that sounds unconventional. But in this case, the “too good to be true” option is actually the one most deeply rooted in U.S. law.

For business owners still battling the 280E tax, ESOPs are no longer a fringe idea. They’re a lifeline. They transform a broken tax environment into an advantage, align teams through shared ownership, and enable founders to exit with both wealth and integrity intact.

Ignoring ESOPs isn’t cautious; it’s costly. The facts are there. The framework is legal. The opportunity is real.

The question now isn’t whether ESOPs work. It’s whether the cannabis industry is ready to use them.

You can hear Darren Gleemans’ full interview on the Innovating Cannabis Podcast to dive deeper into ESOPS.

Alternatives to Bankruptcy for Cannabis Companies: Part 1

By Brent Salmons, Yuefan Wang
No Comments

The problems facing the cannabis industry arising from its ongoing status as a federally illegal enterprise are numerous and well documented: 280E tax burdens, limited access to banking, exclusion from capital markets, uneven access to federal intellectual property right protections and the inability to access the stream of interstate commerce. The recent woes faced by cannabis companies operating in mature markets reveal another key legal hurdle for cannabis companies, their investors and their creditors: the inability to access federal bankruptcy protection. However, cannabis companies may have access to a number of contractual and state law remedies to deal with insolvency and other financial woes.

Background

Bankruptcy laws in the United States are unique in the world; nowhere else is access to bankruptcy so available or forgiving for ordinary citizens and companies alike, allowing debtors a fresh start by either liquidating their assets or reorganizing their debt. Commentators have observed that such favorable bankruptcy laws encourage entrepreneurship and have been at least partially responsible for American innovation. Indeed, the ability of Congress to enact bankruptcy laws is enshrined in the United States Constitution. Like almost all laws in the U.S. at the time, bankruptcy was originally the domain of the various states; it was not until the late 18th century that Congress saw the importance of a uniform set of protections for debtors and passed the first federal bankruptcy law in 1800; since then, bankruptcy has been exclusively the purview of federal law, with current bankruptcy law governed by the United States Bankruptcy Code.

Yuefan Wang, attorney at Husch Blackwell

This exclusivity, however, poses a problem for state-regulated cannabis businesses: because cannabis is federally illegal, in the eyes of the United States Trustee Program, a division of the United States Department of Justice responsible for overseeing the administration of bankruptcy proceedings, the reorganization of any cannabis business amounts to “supervis[ing] an ongoing criminal enterprise regardless of its status under state law.” Therefore, since there is no such thing as state law bankruptcy, even cannabis companies operating in full compliance with state laws do not have access to any bankruptcy protections.1

All financing transactions, whether debt or equity, occur in the shadow of bankruptcy. The basic distinction between debt and equity is predicated on the favorable treatment of holders of the former compared to holders of the latter (within debt, the favorable treatment of secured debt over unsecured debt), and this is true, especially in bankruptcy. Even beyond distribution priorities, the Bankruptcy Code’s provisions on automatic stays, avoiding powers, and discharge fundamentally shape the relationship between debtors and creditors: a bankruptcy judge has the power to impose the Bankruptcy Code on the relationship between a debtor and its creditors, no matter their previous contractual relationships. Just as the possibility of litigation is a Sword of Damocles hanging over any legal disputes, the prospect of a bankruptcy filing affects any negotiations between a debtor and its creditors ab initio. Therefore, when financial problems arise and a cannabis company must begin the difficult task of approaching its lenders for relief, it does so without an effective incentive for creditors to come to the table available to other companies in otherwise similar situations.

Alternatives to Bankruptcy

Just as disputants often prefer the contractual certainty of a settlement agreement to the capriciousness of a jury, debtors and creditors may choose extra-judicial solutions for insolvency. The downward trend in bankruptcies over the last few decades may partially be the product of such out-of-court arrangements, and debtors and creditors are increasingly comfortable with them as an alternative to voluntary or involuntary bankruptcy filing. While the effectiveness of these solutions is, in industries other than cannabis, ultimately evaluated with bankruptcy in mind, these solutions may also be preferable for a creditor of a cannabis company that is defaulting on its obligations.

Contractual Remedies: Lender Workouts, Exchange Offers and Composition Agreements

Given that the relationship between a debtor and its creditors is essentially contractual, the parties may choose to modify their relationship in any manner to which they can mutually agree. A lender workout is an agreement for a financially distressed company to adjust its debt obligations with a creditor (or often multiple creditors given that a lender’s payment obligations to one creditor necessarily affect its obligations to its other creditors). These contractual adjustments are tailored to the particular situation and can take the form of deferrals of payments of interest or principal, extensions of maturity dates, covenant relief (e.g., adjustment of the lender’s debt-to-asset ratio or other financial covenants which would otherwise trigger an event of default), and/or debt-for-equity swaps. This last option (including its related concepts, such as grants of options or warrants) is especially prevalent in the cannabis industry, given that cannabis companies often do not have traditional bank debt (though, at the same time, such solutions may be increasingly unattractive to creditors given lower valuations and the prevalence of equity as a form of consideration in cannabis mergers and acquisitions transactions).

Brent Salmons, attorney at Husch Blackwell

Similarly, an exchange offer restructures a faltering company’s capital stack. Typically, a company facing a default will offer its equity-holders new debt or equity securities in exchange for its outstanding debt securities, which new securities have more favorable terms, such as covenants, events of defaults and maturity. Exchange offers have the same goal as lender workouts in that they seek to eliminate a class of securities with an impending maturity date, event of default or breach of a covenant.

Composition agreements are contractual arrangements between a debtor and its creditors whereby the creditors agree to accept less favorable claims in order for the debtor to reorganize its operations so that the debtor’s future inflows can meet its reduced outflows, with the alternative being a complete collapse of the debtor (in which case no one, or perhaps only the most senior secure lenders, is repaid). These agreements often provide for oversight by a committee of the creditors and will often involve contractual promises by creditors to forbear from exercising their previously existing rights until a defined triggering event.

Statutory Remedies: UCC Article 9 Sales and ABCs

If the contractual remedies described above are akin to Chapter 11 bankruptcy proceedings, whereby a company in dire (but ultimately salvageable) straits continues to operate while its debt obligations are reorganized, state law statutory remedies are analogous to Chapter 7 bankruptcy proceedings; the business is a sinking ship and must liquidate its assets to maximize payments to its creditors (in the bankruptcy context, per the rules of absolute priority). Such liquidation is governed by rules under state law which may be available to cannabis companies.

If a creditor has a security interest in the collateral of a debtor, then the most popular option is usually a sale under Article 9 of the Uniform Commercial Code (UCC). The UCC is a standardized set of laws and regulations for conducting business, including lending. The UCC itself is not law; rather it is a codex that has been adopted by most states and incorporated into their statutes as law, usually with some variations. UCC Article 9 deals with secured transactions and, in particular, provides for the sale and disposition of collateral subject to a security interest upon a default by the debtor. Similar to a §363 sale under the Bankruptcy Code, a sale under UCC Article 9 provides for a “friendly foreclosure” whereby a defaulting debtor and its lenders cooperate to facilitate a sale of the secured collateral.

Article 9 imposes certain parameters on such dispositions, including that foreclosure sales be “commercially reasonable”, which the UCC specifies as meaning that the collateral be sold in a reasonable and customary manner on a recognized market, at then-current market prices. If the sale was approved in a judicial proceeding, by a bona fide creditors’ committee, by a representative of creditors or by an assignee for the benefit of creditors, then this creates a presumption of commercial reasonability under the UCC.

A less common option is an assignment for the benefit of creditors (ABCs). Laws governing such assignments vary by state and are generally rare, with California being a notable exception where both ABCs are more common and where cannabis is legal. An ABC is initiated by the debtor, which then enters into an agreement to assign its assets to a third-party assignee, which holds such assets in trust for the benefit of the creditors and is then responsible for their liquidation, similar in principle to a trustee in bankruptcy.

ABCs, however, are generally not suitable for cannabis companies as the third-party assignee would not be able to take possession of a licensed cannabis business, or certain assets such as cannabis plants, distillates and other products, without itself being licensed by the relevant state regulatory agency. A similar problem occurs under Article 9 sales, whereby the purchaser of the collateral must be licensed in order to possess and operate cannabis product and, more importantly, the all-important state-issued licenses which provide a cannabis company with the authority to operate as such; the pool of potential purchasers is therefore limited to those purchasers already licensed or which are willing to undergo the burdensome process of becoming licensed, hence shrinking the market for such assets and reducing their value. These issues may be resolved in some states by the assignor/seller entering into a management services agreement with the assignee/purchaser, pursuant to which the assignee/purchaser effectively manages the operations of the cannabis business. These agreements, however, need to be carefully drafted so that they are not seen as constituting ownership of the business by the assignee/purchaser (until the actual transfer of the licenses occurs), as defined under applicable state law.


  1. While absolutely true for “plant-touching” companies, recent cases in the federal Ninth Circuit Court of Appeals provide some (fact-dependent) hope for cannabis-adjacent companies such as those housing the employees or intellectual property of a plant-touching operational cannabis company (this structure itself largely a solution to deal with federal illegality).

How ERP Tech Helps Companies Manage Traceability & Process Control

By Scott Deakins
No Comments

Commercial real estate took a dive last year as companies began to work from home, but changing regulatory environments have opened doors to a new industry in need of property: cannabis. Growing rapidly at both the medical and adult use levels, cannabis businesses have been eager to move into vacant buildings, quickly buying up space as more states adjust their laws regarding cannabis.

Cannabis businesses cannot go at it blindly, however. Legal cannabis firms of all sizes – from the smallest startup to the biggest enterprise – will face regulatory challenges, traceability requirements, process control standards and, ultimately, the right technology to keep them moving forward in this promising industry.

Use data to keep track of plants, patients and regulations 

As a highly regulated industry, cannabis companies could be investigated at any time. Regulatory authorities may, at the very least, request proof that they are compliant with state restrictions. Cannabis enterprises will only be able to quickly and easily provide that proof if they have immediate access to accurate historical data. With that information, they can generate the necessary reports at a moment’s notice and maintain a reliable audit trail.

Cultivation is where the tracking process begins.

Historical data is also useful for both growers looking to evaluate why certain plants are more successful than others and for sellers looking to improve their customer experience. By tracking everything from mother plants to clones, growers can build a strong genetics profile and gain a powerful competitive edge. Historical data also aids sellers, who can use it to enhance their digital storefronts and keep track of customer information, shopping history and other details that could improve the e-commerce experience.

In addition to customer details, sellers must also keep track of patient information when selling in a medical-only environment. Prescriptions need to be carefully managed to ensure that patients only receive products that they have been approved to purchase and use.

Utilize process control to foster scalable and repeatable processes

Process control is another vital component that every cannabis grower, manufacturer, processor and distributor must possess. They need scalable and repeatable processes to prevent steps from being bypassed, ensuring that every finished product matches the same high-quality standards. If there are no stopgaps in place, steps could be missed if employees are rushing to meet a deadline or simply think that a particular test or check isn’t needed. Those kinds of mistakes can be hugely detrimental to any cannabis company and may waste product, diminish profits and turn off customers.

PlantTag
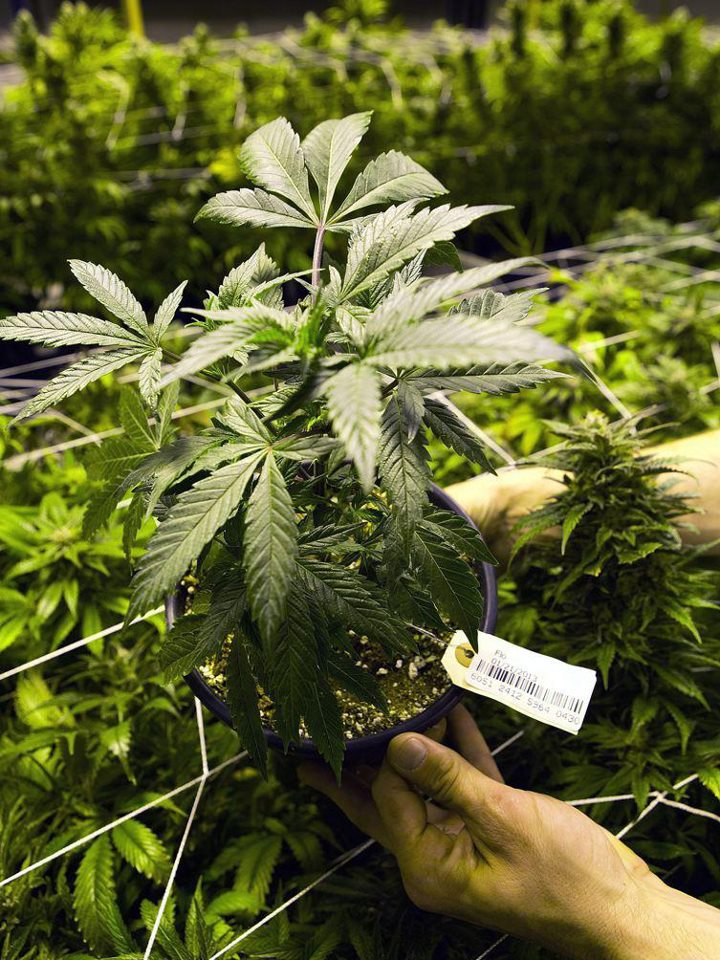
A plant tagged with a barcode and date for tracking

Similarly, visibility and control over inventory is a top priority for any business, but it reigns supreme in the cannabis space. Managers should always, at all times, know where the product is as it moves throughout the warehouse, or risk costs and waste. By directly tying scanners and barcodes to the right technology, organizations can ensure that all product is accounted for and easily located using real-time data.

Build a foundation for scalability 

Cannabis businesses don’t have the time to manually keep track of these aspects, and it wouldn’t even be possible as they grow and expand their operations. As they evolve, so too will the list of software requirements that are needed to operate smoothly, reliably and efficiently.

Cannabis processors have traditionally invested in seed-to-sale technology, relying on barcodes to track products throughout their lifecycle. While it is critical for cannabis enterprises to keep a strong level of control over lot tracking, this type of software is very limited. Cannabis firms would therefore be better served by an ERP solution with a single data source that provides centralized, real-time access to vital business information.

ERP technology can also help cannabis businesses better manage their production schedule, material requirements planning, accounting, purchasing, inventory management and document generation. The key, however, is to choose the right technology, avoiding ERP solutions that rely on customizations and bolt-ons, which will impede an organization’s ability to scale. Cannabis businesses should instead use technology that makes all of its features, enhancements and extensibility available to all customers, ensuring that every user has access to the same benefits.

The Cannabis Industry and Tax Implications of Entity Structure: Issues to Consider

By Calvin Shannon
2 Comments

This piece is intended to provide some considerations that current and potential license holders should think about as they work with advisors to make entity selection decisions or consider potential tax elections. Please note that this article is a high-level overview and is not intended to declare the best type of entity structure for a license holding entity. Although there are numerous tax variables that should be contemplated, tax issues are not the only concerns relevant to determining entity type. In addition, some states may tax entities differently than how the entity is taxed for federal purposes.

First, let’s look at the legal entity types that may be set up to hold a license, operate a business and what that may mean for how an entity is taxed. Often, entities are set up as either limited liability companies or corporations.

If a limited liability company is organized and the entity is owned by only one owner, a single member LLC, the default tax treatment would be that the entity is disregarded for tax purposes. In other words, it would not file a separate federal income tax return, except in some states including CA, TX, TN and RI. All the tax consequences of the activities within the legal entity are reported on the tax return of the owner of the entity.

If a limited liability company is set up and the entity is owned by more than one owner, a multiple member LLC, the default tax treatment would be that the entity is taxed as a partnership. An entity taxed as a partnership reflects the tax consequences of the activities within the legal entity on a partnership return. The partnership generally does not pay tax on the activity, but rather the taxable income and loss are passed through to the owners of the LLC. The owners of the LLC reflect the taxable income or loss on their tax return and are responsible for paying any resulting tax. In the rare instance of an entity being audited, there is a possibility that the entity may have to pay tax on the partners behalf, depending on the ownership structure. Either a single member LLC or a multiple member LLC may elect to treat the LLC as a C-corporation or an S-corporation for tax purposes.

The Taxation of C-Corporations & S-Corporations

The default treatment for an entity set-up as a corporation is the entity will be taxed as a C-corporation. An entity taxed as a C-corporation, including an LLC electing to be taxed as a C-corporation, pays the tax on any taxable income generated by activities within the entity.  Additionally, any distributions of earnings from the C-corporation to the owners of the entity are generally considered dividends which are required to be reported as taxable income by the owners when received. In other words, the earnings of an entity taxed as a C-corporation are potentially taxed twice. Once, as they are earned within the entity, and then again upon distribution to the owners of the entity.

An entity set-up as a corporation, a single member LLC or a multiple member LLC may elect to be treated as an S-corporation. Like an entity taxed as a partnership, an S-corporation does not pay tax at the entity level, but rather passes the taxable income and loss through to the owner or owners. Additionally, like a partnership, distributions from an S-corporation are not taxable as dividends to the owner when received.

Since we covered how different entities are taxed based on how they are set-up, and what elections they may or may not make, we will explore some of the issues that should be considered when making an entity selection. We will also address potentially electing to treat an entity one way or another for tax purposes. 

S-Corporations 

Advantages: The advantages of an S-corporation are limited to the avoidance of double taxation associated with C-corporations, as well as some potential benefits of lower Social Security and Medicare taxes.

Disadvantages: The primary disadvantage of an S-corporation for a license holding company is any non-deductible expenses resulting from 280E are passed through to the owner(s), which then reduces the ownership’s tax basis in its investment in the entity. A reduction in tax basis is determinantal to owners of an entity because the basis is used to reduce taxable income when/if the owner liquidates ownership in the entity.

Other disadvantages of S-corporations include but are not limited to restrictions on ownership of the entity, a requirement for reasonable compensation paid to owners and a lack of flexibility in the allocations of earnings among owners.

Partnerships

Advantages: The advantages of a partnership include but are not limited to the avoidance of double taxation associated with C-corporations, flexibility in the allocation of earnings and losses among owners, and flexibility in the type of owners of the entity.

Disadvantages: Like S-corporations, the primary disadvantage of a partnership is any non-deductible expenses resulting from 280E are passed through to the owner(s).

Other disadvantages of partnerships include potential self-employment taxes on earnings allocated to active owners, potential complexity in the allocations of taxable income and losses among partners in entities with many owners or different classes of ownership.

C-Corporations

Advantages: In contrast to S-corporations and partnerships, the tax basis resulting from the ownership’s investment in the entity is not subject to reductions from non-deductible expenses being passed through to owners. This protection of tax basis is particularly important to owners of license holding entities.

An additional advantage of C-corporation tax treatment may be a lower tax rate applied to taxable income.

Disadvantages: The most significant disadvantage of C-corporation tax treatment is the potential double taxation of earnings that might be applicable if the entity does have earnings that are distributed.

In addition to the items address above, the advantages and disadvantages of the entity type and related tax elections, additional considerations include:

  1. How much of the 280E nondeductible expenses will the taxpayer be subject to?
  2. How much earnings will the entity be distributing to the owners?
  3. How complex is the entity’s ownership?
  4. The lack of certainty regarding whether or not the qualified business income deduction (QBID) enjoyed by pass-through entity owners is allowable as a deduction by owners receiving pass-through income from an entity subject to 280E.
  5. Are there plans for selling the entity and if so, what is the time horizon for doing so?

At Bridge West, we advise taxpayers to consult with cannabis advisors who have experience in the industry, can help navigate the complexities of tax compliance and Code Section 280E and are experienced with entity structures.

How To Choose The Right Cannabis Consultant For Your Company

By Martha Ostergar
3 Comments

The cannabis industry is growing fast as more states implement legislation to legalize cannabis in different ways. If you’re trying to break in or keep your place in this new market, it can be difficult to understand and comply with ever-changing government regulations as you try and scale your business.

Cannabis businesses need to comply with a range of new local, state and federal regulations related to cannabis specifically, in addition to regulations already in place for the pharmaceutical and food industries to ensure their products are safe for public consumption. On top of that, there are the complexities of managing a supply chain, including growing, warehousing, transportation, food safety requirements, product labeling, business plans, marketing, selling and any other necessities that come with running a businesses.

This is a lot of new information when you’re vying for your place in the cannabis industry. That’s why some businesses are turning to consultants to help. Consultancy is a great and time-tested way to grow your businesses and keep a competitive edge. But just like every other industry, when you choose a consultant, there are specific things to look for and avoid.each party will have work to do in order to communicate clearly, define responsibilities and execute on a plan.

Understand the Role of Consultants

The expertise of  cannabis consultants can vary widely. Usually there’s no “one stop shop” for everything you need to run your business, meaning consultants often specialize in a specific area. Consultant expertise includes specialties such as cultivation, manufacturing, food safety, dispensary, transportation, legal, accountants, human resources and more, all within different regulatory compliance wrappers.

It’s important to remember that consultants are usually not responsible for setting goals for you, but the right consultant can help you refine, meet and even exceed your goals. However, each party will have work to do in order to communicate clearly, define responsibilities and execute on a plan.

Focus on Your Specific Needs

Identifying your specific needs and understanding what success looks like for you is a critical step to take before contacting any consultant. This prep work helps you identify what kind of consulting you actually need and what you’re willing to spend to get it. Some consultants can help you tackle more than one area, but most will specialize. In fact, choosing several specialized consultants (if you have many needs), may feel like it costs more up front, but it will likely save you frustration, headaches and money in the long run. Additionally, if a consultant claims they can do everything in several areas of expertise, they may be overpromising on what they can actually deliver to you as a customer.

Ask the Right Questions

When vetting a consultant, it’s your job to ask probing questions. Don’t hold back and don’t be put off by vague answers. If a consultancy avoids questions or can’t give clear answers, they may be overpromising or being less than honest about their skillset. Here are some general areas of discussion to help you get started when interviewing consultants:

Consultants can help you get through unfamiliar territory or help you to manage your team’s workload.
  • The consultant’s relevant experience.
  • Past or current client references.
  • Detailed discussion of your specific needs as a business.
  • How much time can the consultant dedicate to you as a client.
  • Detailed outline of the consultation plan, including a clear timeline.
  • Responsibilities of each party, deliverables and what success looks like for customer sign off.
  • Certifications and credentials if relevant to your consultation needs (e.g. legal, accounting, regulatory).
  • What is and is not included with their quoted fee, and what you may be charged for as an “add on” to your contract.
  • Any possible conflicts of interest, including how consultants separate work for clients who are competitors.

Avoid Red Flags

As with any burgeoning market, there will be consultants who get into the cannabis space that are more interested in making money than helping you as an individual client as businesses work to legitimize the industry as a whole. Doing your research and asking for referrals helps, but there are also red flags to look for. Some of these red flags may pop up due to inexperience and some may be a sign of bad actors in the consultant market.

  • Asking for equity as payment.
  • Refusing to provide references.
  • Avoiding questions or giving unclear answers.
  • Unwilling to track time and itemize costs on bills.
  • Overpromising AKA “this sounds too good to be true.”
  • Dominating the process instead of treating you like a partner.

Build a Strong Relationship

To get the most out of a consultancy experience, it’s important for both parties to work at building a strong business relationship. You know you’re hitting the sweet spot in business relationships when you have well-oiled communication and feedback loops, including honesty around expectations and frustrations from both parties. A great consultant wants feedback so they can improve their process, therefore they will actively listen to and address your concerns. Additionally, it’s important for you as a client to also be open to feedback and ready to make changes to your process to get the best return on your investment.

Richard Naiberg
Quality From Canada

Protecting Intellectual Property in Canada: A Practical Guide, Part 5

By Richard Naiberg
No Comments
Richard Naiberg

Editor’s Note: This is the fifth article in a series by Richard Naiberg where he discusses how cannabis businesses can protect their intellectual property in Canada. Part 1 introduced the topic and examined the use of trade secrets in business and Part 2 went into how business owners can protect new technologies and inventions through applying for patents. Part 3 raised the issue of plant breeders’ rights and Part 4 discussed trademarks and protecting brand identity. Part 5, below, will detail copyright laws for cannabis companies and how they can protect works of creative expression.

Copyright: Protection for Works of Creative Expression

In the course of describing and marketing its products, the cannabis producer will prepare or have prepared any number of articles, instructions, write-ups, photographs, videos, drawings, web site designs, packaging, labeling and the like. Copyright protects all such literary and artistic works from being copied by another.

Copyright arises upon the creation of the work, although one can register the copyright under the Copyright Act for a minimal cost.Canada’s Copyright Act provides that the owner of copyright has the exclusive right to make copies of copyrighted work for the lifetime of its author, and for fifty years thereafter. The Court will enforce this copyright, stopping infringements and ordering infringers to compensate the owner in damages, accountings of profits and delivery up of infringing material for destruction. Intentional copying or renting out of a copyrighted work is also an offence that can attract imprisonment. The owner of a copyright can also request the seizure of infringing articles being imported or exported in Canada.

Copyright arises upon the creation of the work, although one can register the copyright under the Copyright Act for a minimal cost. Registration creates a presumption that copyright subsists in the work and that the registrant is the owner, presumptions that can simplify copyright proceedings. In litigation, the fact of registration also removes the ability of a defendant to argue that it did not have notice of the copyright, a factor relevant to the Court in awarding a remedy.Copyright protects all such literary and artistic works from being copied by another. 

There are two aspects of copyright law that tend to cause confusion. The first involves the distinction between the right to use a copyrighted article and the copyright itself. To illustrate, consider the sale of a literary work, such as a book. The purchaser acquires the physical book but not the copyright. The purchaser can use the physical book and can sell that book to another.  What the purchaser may not do is make and sell another copy of the book. Making copies is the exclusive right of the copyright holder.

The second involves the ownership of a commissioned work. The first owner of a copyright is either the author of the work or the employer of the author if the author creates the work in the course of his or her employment. Ownership of copyright can only be transferred by written assignment. Further, the author of a work is granted moral rights in the work, meaning the right to be associated with the work and the right to its integrity. These rights can be waived by the author but not assigned.

Ownership of copyright can only be transferred by written assignment.Therefore, if a company hires a third party supplier to prepare copyrightable work, such as brochures, artwork or web sites, and does not secure an assignment of the copyright and wavier of the author’s moral rights as part of the transaction, that supplier will own the copyright in the resulting work and the author of that work will have the right to insist on his or her moral rights. The hiring company will not have the right to make or authorize others to make copies of the work, to amend the work, to derive new works from what was delivered, or to use the work without reference to the name of the author or in a way so as to offend the author’s integrity. The supplier will also be free to sell the same brochures, artwork or web sites to other companies, or to derive other works from it. All of this is so even though the hiring company paid for the work to be done. This result is often surprising and disappointing to hiring companies.

Accordingly, cannabis producers contracting with the third parties for literature, photographs, web sites and the like will need to think about how they want to use the work in the future. It is simplest if the producer contracts to have the owner assign the copyright in the work to the producer upon creation, and deliver the author’s waiver of moral rights. While the third party will likely charge more for an assignment of the copyright and the waiver of moral rights, it may be worth avoiding negotiations over specific uses and how the author is to be credited, as well as avoiding the uncertainty inherent in trying to imagine how the producer will use the material in the future.


In the 6th and final part, Naiberg will summarize the key takeaways from his series that cannabis companies can use to protect their intellectual property in Canada.