Tag Archives: California

A Q&A with Matt Hawkins, Co-Founder & Managing Partner at Entourage Effect Capital

By Aaron Green
No Comments

The cannabis industry saw close to $15.5B in deals across VC, private equity, M&A and IPOs in 2020 according to PitchBook data. Early and growth stage capital has been a key enabler in deal activity as companies seek to innovate and scale, taking advantage of trends towards national legalization and consolidation. Entourage Effect Capital is one of the largest VC firms in cannabis with over $150MM deployed since its inception in 2014. Some of their notable investments include GTI, CANN, Harborside (CNQ: HBOR), Acreage Holdings, Ebbu, TerrAscend and Sunderstorm.

We spoke with Matt Hawkins, co-founder and managing partner at Entourage Effect Capital. Matt started Entourage in 2014 after exiting his previous company. He has 20+ years of private equity experience and serves on the Boards of numerous cannabis companies. Matt’s thought leadership has been on Fox Business in the past and he has also recently featured on CNBC, Bloomberg, Yahoo! Finance, Cheddar and more.

Aaron Green: How did you get involved in the cannabis industry?

Matt Hawkins: We’ve been making investments in the cannabis industry since 2014. We’ve made 65 investments to date. We have a full team of investment professionals, and we invest up and down the value chain of the industry.

I had been in private equity for 25 years and I kind of just fell into the industry after I’d had an exit. I started lending to warehouse owners in Denver that were looking to refinance their mortgages out of commercial debt into private debt, which would then give them the ability to lease their facilities to growers. I realized there would be a significant opportunity to place capital in the private equity side of the cannabis business. So, I just started raising money for that project and I haven’t looked back. It’s been a great run and we’ve built a fantastic portfolio. We look forward to continuing to deploy capital up to and through legalization.

Green: Do you consider Entourage Effect Capital a VC fund or private equity firm? How do you talk about yourself?

Hawkins: In the early stages of the industry, we were more purely venture capital because there was hardly any revenue. We’re probably still considered a venture capital firm, by definition, just because of the risk factors. As the industry has matured, the investments we make are going to be larger. The reality is that the checks we write now will go to companies that have a track record of not only 12 months of revenue, but EBITDA as well. We can calculate a multiple on those, and that makes it more like lower/middle-market private equity investing.

Green: What’s your investment mandate?

Matt Hawkins, Co-Founder and Managing Partner at Entourage Effect Capital

Hawkins: From here forward our mandate is to build scale in as many verticals as we can ahead of legalization. In the early days, we were focused on giving high net worth individuals and family offices access to the industry using a very diversified approach, meaning we invested up and down the value chain. We’ll continue to do that, but now we’re going to be really laser focused on combining companies and building scale within companies to where they’re going to be more attractive for exit partners upon legalization.

Green: Are there any particular segments of the industry that you focus on whether it’s cultivation, extraction or MSOs?

Hawkins: We tend to focus on everything above cultivation. We feel like cultivation by itself is a commodity, but when vertically integrated, for example with a single-state operator or multi-state operator, that makes it intrinsically more valuable. When you look at the value chain, right after cultivation is where we start to get involved.

Green: Are you also doing investments in tech and e-commerce?

Hawkins: We’ve made some investments in supply chain, management software, ERP solutions, things like that. We’re not really focused on e-commerce with the exception of the only CBD company we are invested in.

Green: How does Entourage’s investment philosophy differ from other VC and private equity firms in cannabis?

Hawkins: We really don’t pay attention to other people’s philosophies. We have co-invested with others in the past and will continue to do so. There’s not a lot of us in the industry, so it’s good that we all work together. Until legalization occurs, or institutional capital comes into play, we’re really the only game in town. So, it behooves us all to have good working relationships.

Green: Across the states, there’s a variety of markets in various stages of development. Do you tend to prefer investing in more sophisticated markets? Say California or Colorado where they’ve been legalized for longer, or are you looking more at new growth opportunities like New York and New Jersey?

Hawkins: Historically, we’ve focused on the most populous states. California is obviously where we’ve placed a lot of bets going forward. We’ll continue to build out our portfolio in California, but we will also exploit the other large population states like New Jersey, New York, Arizona, Massachusetts, Michigan, Ohio and Illinois. All of those are big targets for us. 

Green: Do you think legalization will happen this Congress?

Hawkins: My personal opinion is that it will not happen this year. It could be the latter part of next year or the year after. I think there’s just too much wood to chop. I was encouraged to see the SAFE Banking Act reappear. I think that will hopefully encourage institutional capital to take another look at the game, especially with the NASDAQ and the New York Stock Exchange open up. So that’s a positive.

I think with the election of President Biden and with the Senate runoffs in Georgia going Democrat, the timeline to legalization has sped up, but I don’t think it’s an overnight situation. I certainly don’t think it’ll be easy to start crossing state lines immediately, either.

Green: Can you explain more about your thoughts on interstate commerce?

Hawkins: I think it’s pretty simple. The states don’t want to give up all the tax revenue that they get from their cultivation companies that are in the state. For example, if you allow Mexico and Colombia to start importing product, we can’t compete with that cost structure. States that are neighbors to California, but need to grow indoors which is more expensive, are not going to want to lose their tax revenues either. So, I just think there’s going to be a lot of butting heads at the state level.

The federal government is going to have to outline what the tax implications will be, because at the end of the day the industry is currently taxed as high as it ever will be or should be. Anything North of current tax levels will prohibit businesses from thriving further, effectively meaning not being able to tamp down the illicit market. One of the biggest goals of legalization in my opinion should be reducing the tax burden on the companies and thereby allowing them to be able to compete more directly with the illicit market, which obviously has all the benefits of reduced crime, etc.

Green: Do you foresee 280E changes coming in the future?

Hawkins: For sure. If the federal illegality veil is removed – which means there’ll be some type of rescheduling – cannabis would be removed from the 280E category. I think 280E by definition is about just illegal drugs and manufacturing and selling of that. As long as cannabis isn’t part of that, then it won’t be subject to it.

Green: What have been some of the winners in your portfolio in terms of successful exits?

Hawkins: When the CSC started allowing companies in Canada to own U.S. assets, the whole landscape changed. We were fortunate to be early investors in Acreage and companies that sold to Curaleaf and GTI before they were public. We are big investors in TerrAscend. We were early investors in Ebbu which sold to Canopy Growth. Those were huge wins for us in Fund I. We also have some interesting plays in Fund II that are on the precipice of having similar-type exits.

You read about the big ones, but at the end of the day, the ones that kind of fall under the radar – the private deals – actually have even greater multiples than what we see on some of the public M&A activity.

Green: Governor Cuomo has been hinting recently at being “very close” on a deal for opening up the cannabis market in New York. What do you think are the biggest opportunities in New York right now?

Hawkins: If it can get done, that’s great. I’m just concerned that distractions in the state house right now in New York may get in the way of progress there. But if it doesn’t, and it is able to come to fruition, then there isn’t a sector that doesn’t have a chance to thrive and thrive extremely well in the state of New York.

Green: Looking at other markets, Curaleaf recently announced a big investment in Europe. How do you look at Europe in general as an investment opportunity?

Hawkins: We have a pretty interesting play in Europe right now through a company called Relief Europe. It’s poised to be one of the first entrants to Germany. We think it could be a big win for us. But let’s face it, Europe is still a little behind, in fact, a lot behind the United States in terms of where they are as an industry. Most of the capital that we’re going to be deploying is going to be done domestically in advance of legalization.

Green: What industry trends are you seeing in the year ahead?“We’re constantly learning from other industries that are steps ahead of us to figure out how to use those lessons as we continue to invest in cannabis.”

Hawkins: Well, I think you’ll see a lot of consolidation and a lot of ramping up in advance of legalization. I think that’s going to apply in all sectors. I just don’t see a scenario wherein mom and pops or smaller players are going to be successful exit partners with some of the new capital that’s coming in. They’re going to have to get to a point where they’re either selling to somebody bigger than them right now or joining forces with companies around the same size as them and creating mass. That’s the only way you’re going to compete with companies coming in with billions of dollars to deploy.

Green: How do you see this shaking out?

Hawkins: That’s where you start to look into the crystal ball. It’s really difficult to say because I think until we get to where we truly have a national footprint of brands, which would require crossing state lines, it’s going be really difficult to tell where things go. I do know that liquor, tobacco, beer, the distribution companies, they all are standing in line. Big Pharma, big CPG, nutraceuticals, they all want access to this, too.

In some form or fashion, these bigger players will dictate how they want to go about attacking the market on their own. So, that part remains to be seen. We’ll just have to wait and see where this goes and how quickly it goes there.

Green: Are you looking at other geographies to deploy capital such as APAC or Latin America regions?

Hawkins: Not at this point. It’s not a focus at all. What recently transpired here in the elections just really makes us want to focus here and generate positive returns for investors.

Green: As cannabis goes more and more mainstream, federal legalization is maybe more likely. How do you think the institutional investor scene is evolving around that? And is it a good thing to bring in new capital to the cannabis market?

Hawkins: I don’t see a downside to it. Some people are saying that it could damage the collegial and cottage-like nature of the industry. At the end of the day, if you’ve got tens of billions of dollars that are waiting to pour into companies listed on the CSC and up-listing to the NASDAQ or New York Stock Exchange, that’s only going to increase their market caps and give them more cash to acquire other companies. The trickle-down effect of that will be so great to the industry that I just don’t know how you can look the other way and say we don’t want it. 

Green: Last question: What’s got your attention these days? What’s the thing you’re most interested in learning about?

Hawkins: We’re constantly learning about just where this industry is headed. We’re constantly learning from other industries that are steps ahead of us to figure out how to use those lessons as we continue to invest in cannabis. We all saw the correlation between cannabis and alcohol prohibition. The reality is that the industry is mature enough now where you can see similarities to industries that have gone from infancy to their adolescent years. That’s kind of where we are now and so we spend a lot of time studying industries that have been down this path before and see what lessons we can apply here.

Green: Okay, great. So that concludes the interview!

Hawkins: Thanks, Aaron.
Learning from The First Wave Part 3: Seven Basic Questions About Local Cannabis Ordinances & Real Estate

By Todd Feldman
No Comments

Part One of this series took a look at how the regulated cannabis market can only be understood in relation to the previous medical market as well as the ongoing “traditional” market. Part Two of the series describes how regulation defines vertical integration in California cannabis.


If you are considering getting involved in California cannabis, imagine the following sentence in ten-foot-tall letters made out of recently ignited $20 bills:

Before you put any money down on property, carefully examine the local cannabis ordinance and tax rates. 

This article is written in the form of advice to a newbie cannabis entrepreneur in California, but it will discuss issues that are also of significance to investors, as well as (to various degrees) cannabis entrepreneurs in other states.

Here are seven basic questions that you need to ask about local regulations (in order, except for Number 7).

1. What’s Your Jurisdiction?

If you’re in city limits, it’s the city. If you’re outside city limits, it’s the county.

2. Does the Jurisdiction Allow Cannabis Activities?

If the answer is yes, go to the next question. If the answer is no, pick another jurisdiction.

3. Where Does the Jurisdiction Allow Cannabis Activities?

A zoning ordinance will limit where you can set up shop. The limitation will probably vary by license type.

4. How Does the Local Ordinance Affect Facility Costs?

The short answer is: in many ways. Your local ordinance is a Pandora’s box of legal requirements, especially facility-related requirements.1 Read your local cannabis ordinance very carefully.

Generally speaking, the cannabis ordinance will set out two types of requirements – those that are specific to cannabis and those that apply generally to any business.

Looks great but . . . where are the sprinklers? Does it need a seismic upgrade? How about floor drains?
Photo by Wilhelm Gunkel on Unsplash

Cannabis-specific requirements:

  • Typically incorporate state cannabis laws by reference.
  • Have significant overlaps with state cannabis laws. For example, the state requires commercial-grade locks and security cameras everywhere cannabis may be found on a given premises. Local ordinances generally include similar requirements – keep in mind that you will need to comply with a combined standard that satisfies both state and local requirements.2
  • Vary greatly according to type of activity. For example, manufacturers will need to comply with Health & Safety Code requirements that can have a major impact on construction costs.
  • Vary greatly by jurisdiction when it comes to equity programs.

General requirements:

  • Include by reference building and fire codes, which can require very expensive improvements. Note that this means your facility will be inspected by the building department and the fire department.
  • Can include anything from Americans with Disabilities Act (ADA) requirements to city-specific requirements, such as Design Guidelines.
  • Will be zealously enforced because you’re a cannabis business.

5. What is the Enforcement Policy?

It may be that your local jurisdiction will give you temporary local authorization after meeting some, but not all, of the requirements. For example, you may be able to begin operations once you’ve provided your city or county with your cannabis permit application, a zoning clearance and a business permit. In this jurisdiction, you would be able to bring your building up to code sometime after you begin operations.

On the other hand, your local jurisdiction may require you to meet every requirement – from cannabis-specific security requirements to general building code and ADA requirements – before you can begin operations. Depending on the type of cannabis business (and facility condition), this might be inconsequential. Or it might mean that you will have to pay more than a year’s worth of rent (or mortgage) before you can start making money.

6. Can You Choose a Facility That Saves You Time and Money?

Of course, you won’t have to spend much time or money bringing your facility up to code if it’s already up to code. How likely it is that you will find such a facility varies wildly according to the type of cannabis activity in question. In general:

  • Service-side activities (delivery retail, storefront retail, distribution) are in many respects similar to their non-cannabis counterparts. From a facilities standpoint, the major differences come from security requirements. So, it may be possible to save time and money by choosing a facility that is already up to code for a similar use.
  • Manufacturing activities are trickier, since you will need food-grade facilities and equipment. You may be able to save money by setting up shop in a commercial kitchen.
  • Extraction with volatile solvents is a special (and particularly expensive) case, since it is inherently dangerous and requires special facilities.
  • Outdoor cultivation may be relatively unproblematic if it has an appropriate water source.
  • Indoor cultivation is expensive because of climate-control and lighting requirements. Buildings potentially suitable for large-scale indoor grows frequently come with significant problems. Former warehouses will typically require major power upgrades, while former factories may have inconvenient architecture and/or hidden toxic waste. In all cases, internal reconstruction is likely to be necessary, and will trigger all sorts of building and fire code requirements.

7. What Are the Local Cannabis Taxes?

Cannabis tax rates may be determinative. For example, Oakland imposes a 6.5% gross receipts tax on manufacturers that have gross receipts of less than $5M, and 9.5% on manufacturers that have gross receipts over $5M. In comparison, Santa Rosa only imposes a 1% gross receipts tax on manufacturers.

Local cannabis ordinances and taxes can make or break your business, so you need to understand them before you commit to a location. The seven basic questions listed above are designed to get you started.

This article is the opinion of the author and is not intended to be legal or other advice.


References

  1. For example, see Part II of the City of Oakland’s Administrative Regulations and Performance Standards, and The City of Los Angeles’s Rules and Regulations for Cannabis Procedures No. 3 (A)(14).
  2. For example, compare 16 CCR § 5044 (“Video Surveillance System”) with The City of Los Angeles’s Rules and Regulations for Cannabis Procedures No. 10 (A)(7).

Flower-Side Chats Part 1: A Q&A with Sam Ghods, CEO of Connected

By Aaron Green
No Comments

Flower continues to be the dominant product category in US cannabis sales. In this “Flower-Side Chats” series of articles Green interviews integrated cannabis companies and flower brands that are bringing unique business models to the industry. Particular attention is focused on how these businesses navigate a rapidly changing landscape of regulatory, supply chain and consumer demand.

Connected is a vertically-integrated cannabis company based out of Sacramento, CA and one of the most sought-after brands in California and Arizona. Having formed as a legacy operation in 2009, Connected has created a cult-like following over more than a decade in business. According to BDS Analytics, Connected Cannabis and their acquired brand Alien Labs now boasts the highest wholesale flower price in any major legal market – their average indoor flower wholesale price is 2x the CA average – yet also has the highest flower retail revenue.

We spoke with Sam Ghods, CEO of Connected to learn more about his transition from tech to cannabis, how Connected thinks about product and his vision for future growth. Sam joined Connected in 2018 after getting to know the founders. Prior to Connected, Sam was a co-founder at Box where he stayed on for 3 years after their successful IPO.

Aaron Green: How did you get involved in the cannabis industry?

Sam Ghods: I originally came from the tech industry. I co-founded Box, a cloud sharing and storage company, in the mid 2000s with three other friends. We grew that from the four of us to eventually a multi-billion-dollar public offering in 2015. I stayed on a few more years after that until I took some time off trying to decide what I wanted to do next. I looked at a number of different industries and companies, but personally I always had a real passion for artisan and craft consumer goods. It’s a really big hobby of mine. Whether it’s going to Napa or learning about different kinds of premium consumer goods, I really had a deep love and never knew cannabis could be like that.

When I first met Caleb, the co-founder of Connected, he instantly got my attention by telling me that they had been selling out of their product in the volume of millions of dollars a year at more than two times what everybody else was selling for. That really piqued my interest because creating a product that has that level of consumer passion and demand is maybe the single hardest thing about building a consumer goods business. For them to have been so successful in what was a very difficult and gray market to operate in at the time – this was mid 2018 that I was speaking with him and he had been building this company since 2009 – is a really big challenge, and really impressive.

Sam Ghods, CEO of Connected

So, I started spending time with Caleb and the Connected team and learned a lot about the business. Everything I learned got me more interested and more excited. The way that they thought about the product, the way they treated it was with a reverence and level of sophistication I had no idea was possible.

I was so excited to just learn about the space. I mean, honestly, it feels like the internet in the 90’s- The sheer possibility and excitement. The only difference here is that the market already has existed for 100 years plus: the gray and underground markets for this product are actually phenomenally mature. And now we’re lifting up billions of dollars in commerce that’s already occurring and attempting to legalize all of it in one fell swoop, which creates such an interesting set of challenges.

I first got involved as an advisor on fundraising and strategy. And then a few months later, they were looking for a CEO and I joined full time as CEO in September 2018.

Aaron: What trends in the industry are you focused on?

Sam: It may seem basic, but I think product quality in the broader cannabis markets nationally and internationally is really underrated. Because of the extreme weight of the regulatory frameworks in so many different markets, it’s resulting in a lot of product being grown and sold just because it can be by the operators that are doing it. In many markets, they count the number of producers by the handful, instead of being measured in hundreds or thousands like in California or Oregon. And in that kind of environment, you’re not really having competition, and you’re not really able to see the quality that has existed in this category for years and years and years.

That’s one of the things that really sets us apart – the quality is first above all else, as well as the innovation and time that has gone into it, and not many existing brands in the legal market can say that. With some of the “premium” brands on the market, it would be comparable to just jumping into the wine industry one day and thinking that you can become a premium brand, without having any knowledge of the history of the product or the industry itself. At Connected, we have a team that’s been doing this for over a decade. We did a back of the envelope calculation: there’s over one thousand lifetime harvests between our team. We’ve also brought in specialists from Big Ag and other industries to complement that experience.

Cannabis is a very, very difficult plant to grow at a very high level. It’s much more like high-end wine or spirits than other fruit or produce. I think in the cannabis community, that’s extremely acknowledged, and appreciation for that is the reason we get by with the highest prices in the legal market. I think in the broader investor and financial community, this point hasn’t really hit home, because the limited license markets aren’t mature enough, and there isn’t enough competition in many of them.

Our focus is continuing to make the best product we can, which has fed and developed our brands [Connected and Alien Labs] into what they are today. That is our number one focus, and we think it’s pretty unique to the space of not just cultivating a great quality product, but also as far as breeding, pushing the bar higher and higher on what can be done with the genetics of the plant. 

Aaron: How do you think about choosing testing labs?

Sam: So, the number one criterion is responsibility and compliance. We must be completely confident that they’re testing accurately, safely and exactly to the specifications of the state. Then from there, it is really cultivating about a partnership. There’s a lot of nuance in the relationship with a testing lab. We note things like: Are they responsive? Are they sensitive to our needs in terms of either timelines or requirements we have? It does come down to timelines and costs to a certain extent, like who’s able to deliver the best service for the best cost, but it really is a partnership where you’re working together to deliver a great product. Reliability and consistency are big pieces as well.

Aaron: Industry estimates for illicit market activities are something like 60% of the California market. From your perspective, how do we fix that?

Sam: I think it probably comes down to funding for the efforts to discontinue those activities and opening up the barrier to entry, incentivizing “illegal” operators to make the investment in the cross-over. I think the most successful attempts to tamp it down was when there were initiatives that were well-orchestrated and well-funded, allowing for legacy growers to actually cross over to the “legal” industry. You can’t launch an industry with such an extreme amount of regulation, set a miles-high barrier to entry, and then penalize legacy growers for continuing their business as-is. If the illicit market continues to be fueled by rejection, you’re not going to achieve the tax revenue that you’re expecting to see, that we all want to see. There needs to be an attitude that every dollar put into transitioning illicit markets into regulated markets is returned many times over in tax revenue to the state’s citizens.

Aaron: So, I understand you sell wholesale. Do you sell direct to consumer?“Once they hit the shelves, we blow people away again, beyond their expectations of what they had before.”

Sam: We own and operate three retail stores, so we do sell direct to our consumers, but at this point the majority of our product is sold through third party dispensaries.

Aaron: Do you make fresh frozen?

Sam: We do. On the cultivation side we have indoor, mixed light and outdoor. We fresh freeze a portion of our outdoor harvest every year, and then we use that fresh frozen for our live resin products, for example, our recent live resin cartridge. It creates a vape experience really unlike any other because we are using our regular market-ready flower, but instead we’re taking that flower and actually extracting, not just using the distillate and mixing a batch of terpenes with it. We extract the entire plant’s content across the board, from cannabinoids to terpenoids and everything in between, and then you have our live resin cartridges.

Aaron: How do you think about brand identity and leveraging the brand to command higher prices?

Sam: The cycle we’ve effectively created is that every time we do a release of a new strain or a new batch or harvest, the quality is generally going up. That quality is released under our brands, and then the customer is able to associate that increase in quality and reputation with those brands. Then for our next launch, we have an even bigger platform to talk about the products and to ship and distribute and sell the products. Once they hit the shelves, we blow people away again, beyond their expectations of what they had before. That continuous cycle keeps fortifying the brand and fortifying the product. From our perspective the brand is built 100% on the quality of the product. The product will always be our highest priority and the brand will come downstream from that. 

Aaron: Tell me about Alien Labs.

Sam: Alien Labs was an acquisition. It was a company that had built their brand really successfully in the gray market through 2017 and Prop 215 in California and had an incredible level of quality, a really loyal and dedicated fan base, not to mention a tremendous Instagram presence and following, which is where 98% of cannabis marketing happens today. We really loved the spirit of what the founders were bringing to the table. In 2018, we decided basically to join forces with them and bring them on board, creating a partnership where they leverage our infrastructure and the systems and processes we’ve built, but still keep their way of cultivation and their product vision. To this day, Ted Lidie, one of the founders, continues as the lead brand director for Alien Labs.

Aaron: In what geographies do you currently operate?

Sam: Our primary offices and facilities are based out of Sacramento, California, but we have facilities throughout the state. Last year, for the first time we launched operations in a new state, Arizona. As you may know, you’re not allowed to take cannabis products across state lines at all, so if you want consistent product in multiple markets you really have no choice but to rebuild your entire infrastructure in each state you want to open up.

There are many brands that are expanding and launching in more markets more quickly, but they’re doing so by taking product that’s already existing and putting their brand name on it. That is something we’ve decided strategically that we will not do. We’ve spent years building a high level of trust with our customers, so we’re only going to put our brand name on products that are our genetics, our cultivation, our style, our quality of product. When we launched in Arizona, we did it with a facility that we leased and took over and now operate with our staff. We’re replicating the same exact product that you can get in California in Arizona, which is really exciting.

We launched just this past November, which has been incredibly successful. Our dispensary partner Harvest saw lines of dozens of people out the door.“We consider ourselves a flower company first and foremost, so for us, that was a very calculated strategic move.”

Aaron: Any new geographies on the horizon that you can talk about?

Sam: We’re constantly evaluating new opportunities. I don’t have anything particularly specific to announce right now, but I will say we look for states where we believe there’s a competitive environment where the product quality is going to really stand out and be appreciated.

Aaron: Do you notice any differences in consumer trends between California and Arizona that stand out?

Sam: Not too many yet. We don’t have a retail location in Arizona, so we don’t have as much direct contact. However, we have heard consistently that the Connected customer demographics – as you would imagine most interested in our product – are those looking for something special, unique, different and have a really superior quality to everything else out there. We ended up launching in Arizona with the highest price point for flower in the state, and we say that’s just the beginning. The market is still so young and immature, both nationally and internationally, that this category is going to develop into one that’s really taste-driven.

Aaron: What’s next in California?

Sam: Continued growth and product development. We want to keep blowing away our customers with more and more incredible products, different product types and categories. For example, the cartridges were a really big launch for us because we don’t really consider ourselves a vape company. We consider ourselves a flower company first and foremost, so for us, that was a very calculated strategic move. We were only going to launch the product if we could fully replicate what the consumer gets from the flower experience. We are very unlikely to ever release a distillate pen, for example.

Aaron: What are you personally interested in learning more about?

Sam: We, as a society, really don’t know very much about the cannabis plant. Pretty much all meaningful research around cannabis stopped in the early 1900’s with prohibition. In the meantime, we’ve performed millions of dollars of studies and research on almost every other plant that we grow commercially. We understand these plants extraordinarily well. Cannabis science is stuck back in agriculture of early 1900s. The most interesting conversations I have are around how the plant works, how it doesn’t work and the ways in which it is so different from all other plants with which we are familiar. Our head of cultivation comes from Driscolls, the largest berry company in the world, and even he is frequently surprised by the way the cannabis plant reacts to things that are commonly understood in other plants. So, the way the actual plant responds to different environments is truly fascinating and something I think we’ll be learning about for decades and decades to come.

Aaron: Okay, great. That concludes the interview. Thank you, Sam!

Learning from the First Wave Part 2: California’s Cannabis Supply Chain and Vertical Integration, with a Grain of Salt

By Todd Feldman
No Comments

Part One of this series took a look at how the regulated cannabis market can only be understood in relation to the previous medical market as well as the ongoing “traditional” market. Part Two of the series describes how regulation defines vertical integration in California cannabis, and conversely, how vertical integration can address some of the problems that the regulations create. But first:

A Grain of Salt

Take the conventional wisdom about vertical integration with a grain of salt. Expected benefits may not materialize under the current circumstances:

  • Overall, the business environment is highly challenging due to extensive regulation, over taxation, insufficient retail capacity and competition from the “traditional” market. As a result, integrating businesses upstream or downstream may mean capturing losses, not profits.
  • The three major types of cannabis activity span three major industrial sectors: raw materials (i.e., cultivation), manufacturing and service (distribution, testing and retail). As a result, a vertically integrated company needs to carry out very different types of activity, which require very different types of core competencies, equipment and facilities.
    • Developing core competencies is especially challenging because each of the major cannabis sectors is still evolving.
    • Realizing the benefits of vertical integration requires an additional core competency in cross-sector operations.

 Regulations Define the Supply Chain

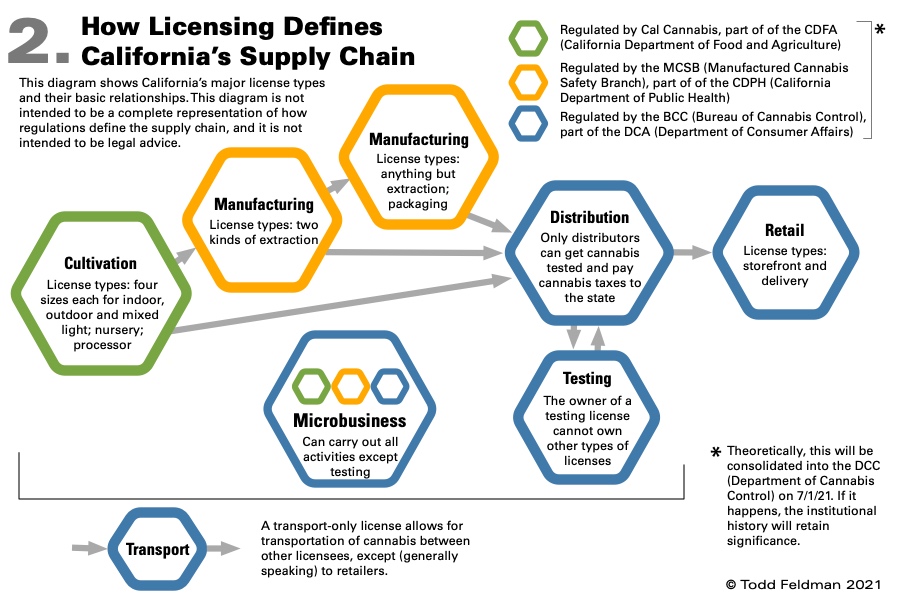
California’s regulations define the cannabis supply chain by defining both the individual links (licensees) and the relationships between those links. Therefore, an understanding of vertical integration must be grounded in an understanding of the underlying regulatory definitions.

The regulatory definition of each link is extensive. For example, each licensee is tied to a specific facility, and must have its own procedures for production, inventory control, security, etc. When the links are strung together, this definition tends to preserve operational redundancies, and impede operational integration.

Overall, the relationships between the links are primarily defined in terms of preserving the chain of cannabis custody. On top of that, regulations define very specific (and very consequential) links between certain licenses, as discussed below.

A Taxonomy of Links

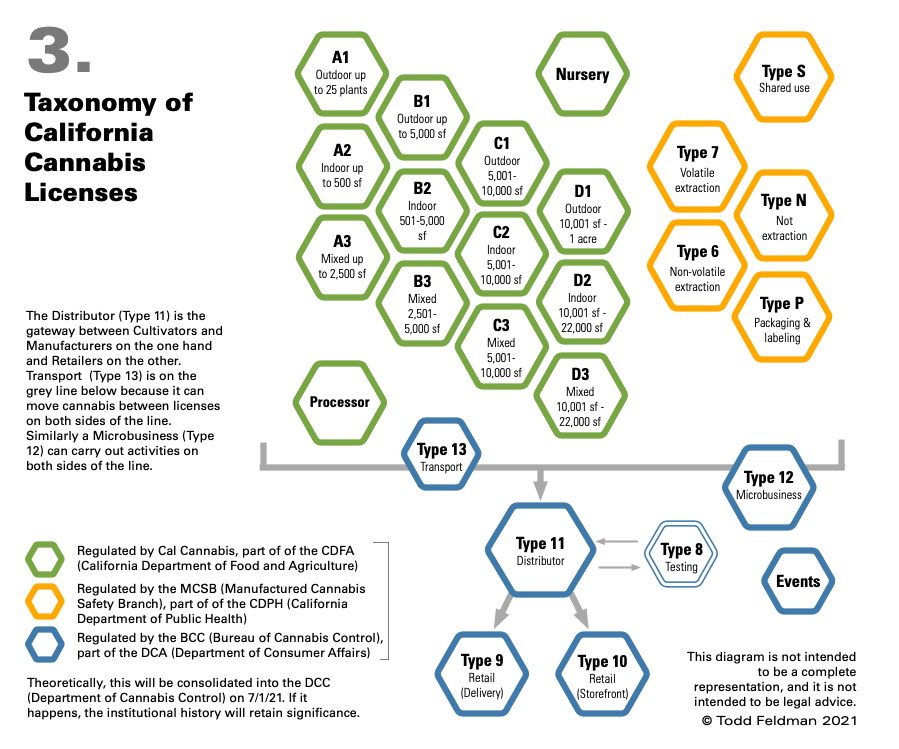
There are currently 26 types of cannabis license in California, 25 of which can be vertically integrated:

  • Cultivation – 14 licenses, including 4 sizes each for Indoor (up to 22,0000 sf), Mixed Light (up to 22,000 sf) and Outdoor (up to 1 acre), as well as Nursery and Processor (drying, trimming and packaging/labeling). Note that cultivation licenses are the only licenses that restrict the scale of activities.
  • Manufacturing – 5 licenses, including volatile extraction, non-volatile extraction, everything but extraction (i.e., infusion) and packaging/labeling.
  • Testing (Type 8), for testing cannabis according to state standards prior to sale. The owner of a testing license cannot own any other type of license.
  • Distribution (Type 11), acts as the gateway between cultivation and manufacturing on the one hand, and retail on the other. The distributor’s gateway status is entirely an artifact of regulation – cannabis must be officially tested before it is sold to a consumer, and only a distributor can order the official test. All products must stay in a “quarantine” area at the distributor until they pass testing. Products that fail testing must be destroyed if they cannot be remediated.
  • Transport (Type 13), which can move cannabis between licensees (with a narrow exception). This license does not allow for official testing.
  • Storefront Retail (Type 9), which is the best license to have, and the hardest one to get.
  • Delivery Retail (Type 10), for delivery services that are subject to the vagaries of software platforms and the intransigence of local authorities.
  • Microbusiness (Type 12), which allows the licensee to carry out cultivation (up to 10,000 square feet), non-volatile manufacturing, distribution and retail.
  • Event Organizer

Self-Distribution – A Case of Useful Integration

You may gather from the previous section that shoving a gratuitous and mandatory distributor into the middle of the supply chain creates problems for cultivators and manufacturers. Savvy operators solve this problem by getting a distribution license. This allows the cultivator or manufacturer to:

  • Pick the time and place for the testing of its cannabis products.
  • Avoid paying someone else for the storage of cannabis products as they await test results or purchase.
  • Reduce transport costs (particularly if the distributor is near the other operations).
  • Sell directly to retailers.

The bottom line is that vertical integration in California cannabis is useful as a means to an end, as opposed to an end in itself. Therefore, cannabis operators should carefully consider how vertical integration will benefit their core business before incurring the risks and expenses associated with an additional license.

This article is an opinion only and is not intended to be legal advice.

Hardware Platforms in Cannabis: A Q&A with Mike McDonald, President and CEO of Ammonite

By Aaron Green
No Comments

More and more we are seeing the development of proprietary hardware platforms in cannabis. With proprietary technology in hand, manufacturers often lean on MSOs, LPs and other brand partners to grow their business through existing sales channels.

We spoke with Mike McDonald, President and CEO at Ammonite, to learn more about the history of the Dablicator™ platform and Ammonite’s North American brand partner strategy. Mike formed Ammonite as a spin-off company from Jetty Extracts after getting to know the founders in a real estate transaction. Prior to Ammonite, Mike was an operator in the manufacturing and product development space, having helped to launch the Giant bicycle brand as well as growing and eventually selling the Atlas Snowshoe Company to K2 Sports.

Aaron: How did you get involved in cannabis?

Mike: Well, like a lot of folks in the industry, my background is pretty eclectic. I come primarily from an operator’s perspective – I’ve been in manufacturing, product development and company growth for my whole career. I lived in Taiwan for several years and helped to launch the Giant bicycle brand worldwide. I was also involved with a ski business that was started at Stanford as a thesis project called Atlas Snowshoe Company. Fast-forward, we built it into the largest snowshoe brand and activity in the US and later sold it to K2 Sports. So, I’ve always been involved in the growth of product-related businesses.

Mike McDonald, President and CEO at Ammonite

I’ve also done some real estate development as well; I actually sold our building to the Jetty guys, which is how we met. In that process, I got involved with their company, helped Jetty reorganize its business model, raise some money, and then just got addicted to the whole industry and really found it fascinating. I liked the team at Jetty and couldn’t resist jumping in, and now I’ve been full-time in the business for over three years.

Aaron: How did you get involved in Ammonite?

Mike: Ammonite is actually a spin out company from Jetty Extracts, which is one of the largest brands in California. Our main Ammonite product is called the Dablicator™ Oil Applicator, which was originally invented at Jetty as a medical device for cancer patients. We saw a big demand for it as a private label partnership product, so we decided to spin out a separate hardware company and really focus on developing unique IP and CBD and cannabis related hardware.

Aaron: What trends are you following in the industry?

Mike: Certainly the MSOs of the world are really expanding and the top three to five are making a mark with growth and more sophistication in the market. I think the social equity movement is really a big component that we’re all excited about in the industry. You’re seeing the larger players really put their money where their mouth is around that. We’ve always been a big part of that in California.

Specifically, regarding trends in the cannabis space, Colorado and California are probably the two most mature markets. We generally say what’s happening in California and Colorado eventually make their way out to the rest of the world. Vaping was invented in California and Colorado, and now it’s a huge part of the business where before, four or five years ago, the market was mostly flower-centric.

There’s a trend away from inhalables, with more awareness around lung-related illnesses and of course COVID, so we’re seeing a big growth in edibles, drinks and so forth. Interestingly enough, although it’s an inhalable, infused pre-rolls are a big growth sector as well. Jetty is actually launching an infused pre-roll program in February.

Folks are looking for ways to get their medicine without smoking – and this has definitely led to a growth in the oil application business. Oil application has traditionally been delivered via a syringe. Dablicator™ oil applicator is essentially an improved, more convenient syringe. On the medical side, patients have been taking oil sublingually, putting it in food and drink and so forth for years because a lot of them can’t smoke. As that trend transfers over to the adult use market, oil application is becoming really big. You can take it sublingually; you can put it in your food or beverage. On the recreational side, you can add it to your loose flower or joints, or of course, dab it directly onto your rig via the heat resistant tip.

Further, you’re probably familiar with a lot of these portable dab rigs that are taking off, like the G Pen Roam and the Puffco Peak and a variety of others. So now you can dab on the go with your standard wax and shatter in a jar. It’s just not the most convenient way if you’re up on a hike or on a mountain bike ride. So now, with a portable dab rig and something like the Dablicator™ oil applicator, you can have a really convenient mess-free way to enjoy cannabis. The big growth in concentrates and areas that aren’t necessarily inhalables is where our product hardware really fits in.

Aaron: How did you come up with the idea for the Dablicator?

Mike: The Jetty team had a friend that had brain cancer. He was doing a lot of chemotherapy and was having trouble eating and keeping weight on and he couldn’t smoke. So, the guys at Jetty began to bring him cannabis oil, which he was able to use ingesting it from a spoon initially and it really helped him with his pain, his anxiety and his appetite. In that process, we realized that there wasn’t really a great way to deliver oil. Syringes were there, but they were kind of sketchy and they weren’t convenient.

So, the Jetty team developed a better mousetrap. Several iterations later, this Dablicator™ product was ready for patients. In fact, it became a big part of the Jetty Shelter Project, a non-profit where the team delivers cannabis to cancer patients, and it was a very much sought-after product delivery device in that world. So, it was developed inside of a need on the medical side and it’s really sort of grown inside the expansion on the adult-use side.

Aaron: Can you explain how the Dablicator™ oil applicator works from a perspective of form and function?

Mike: Pre-Dablicator™ you would use a syringe type product – for direct oil application, sublingual application, or as an add on to your flower. The difference between Dablicator™ oil applicator and a traditional syringe is that Dablicator™ is a twist and plunge product. Imagine a pen filled with oil, but instead of inhaling it, you’re able to dispense it through a tip that is heat resistant, which means you can apply directly to your dab rig nail. You’re able to put it in your pocket without fear of cannabis oil leakage. It’s discreet, precise, compact and portable.

Aaron: How does the user dose using Dablicator™ oil applicator?

Mike: Basically, there’s measurements on the plunger of 55 milligrams apiece – one click is 55 milligrams, and you can dispense as many clicks as you like. What’s cool about the product itself is if you’ve clicked too many times accidentally, you can back it off and the excess oil won’t dispense. You can go to dablicator.com and see demo videos as well.

Aaron: Dablicator™ oil applicator started as a Jetty Extracts spin-off. I see you are now white labeling for other oil brands. How do you go about selecting your partners?

Mike: We call it our brand partner program. It’s not too dissimilar to what other hardware manufacturers, like PAX and GPen, are doing. We’ve got a patented and innovative device where our brand partners, MSOs and leading brands throughout the US and Canada, can take their existing vape and tincture oils and offer them in Dablicator™ oil applicator hardware.

Our focus is signing up major, well respected brands and MSOs on to the “platform,” meaning they are able to immediately offer between six and ten new SKUs to their consumers. They take their existing oils, put them into a custom branded Dablicator™ hardware unit and add their custom branded packaging. It’s a full turnkey solution. For example, one of our partners, 710 Labs, is developing their RSO and were shopping for a delivery method specifically geared towards medical patients. Within eight weeks, we had a custom program for them and delivered hardware, and we assisted on the packaging front as well.

Our partners have to be reputable folks that are interested in developing or delivering oil in a unique and innovative way. Frankly, our early partners are those that see where the growth is. 710 Labs is on the platform, as well as Surterra in Florida, Ancient Roots in Ohio, and we’ve got multiple conversations going to some of the other MOSs and the LPs in Canada.

Aaron: Are the brand partners loading the oil applicator themselves?

Mike: We customize the product for them and then ship them unassembled and empty. In their lab, they use the same machinery and equipment they use to fill their vape cartridges. They then fill their Dablicator™, assemble it, package it and ship it out just like any other product that they’re processing and manufacturing.

Aaron: What kind of oils are suitable for Dablicator™?

Mike: Pretty much any oil that’s going into a vape cart is suitable and then some. Some of our customers, including Jetty, started out with a THC distillate. Live resin is becoming a big product category in California as well as solventless oils. Dablicator™ oil applicator can accommodate everything from distillate to live resin to solventless to RSO and even full spectrum CBD. If it can flow, if it doesn’t crystallize up like shatter and sugars and diamonds, you can put it into Dablicator™, even the thickest of oils. It’s designed to contain any kind of liquids that are flammable.

Aaron: What geographies are you currently in?

Mike: We’re in multiple states throughout the US and actually just signed up with an LP in Canada. We only launched the program in August of 2020, and today we’ve got partners California, Colorado, Ohio, Arizona, Missouri, Florida, soon to be Michigan, Illinois, and throughout Canada.

Aaron: Any plans for international expansion beyond North America?

Mike: We’re getting inquiries on a regular basis from all over the place, including internationally. We’re in conversations with some folks down in Brazil. Spain is actually a big cannabis market and we’re having some conversations with some folks there. The inquiries are coming in faster than we can process the relationships, but right now our major focus is on North America.

Aaron: What are your goals with Ammonite?

Mike: We are developing a category, right? So today, oil dispensing isn’t top of mind. Today, if you want oil, you go into a dispensary and say, “Hey, give me those syringes.” My goal is that a year from now, you can walk into Harborside in Oakland and you see a wall of different branded Dablicator™ oil applicators. The goal is to really turn the oil dispensing business into a category, and then position Dablicator™ oil applicator as the best and leading product in that category.

Aaron: What are you personally interested in learning more about?

Mike: Well, I’ve got two teenagers – two daughters, as a matter of fact, a freshman and a senior – and they’re being homeschooled right now. So that’s been quite an interesting development!

I think on the cannabis side, it’s just fascinating what it is as a business model. It’s the most recent multi-billion-dollar opportunity in consumer products. You only get a chance to participate in something like that maybe once in a lifetime. I’m really looking forward to seeing it become more adopted into the mainstream and it’s already becoming that way from a consumer perspective. I am watching the cannabis market become legal from a federal perspective, hoping that the social equity component of the industry really stays with it.

I’ve been in a lot of businesses over the years; I feel like one of the gray hairs in this business that is actually an operator versus someone who came over from the financial side. I am continuing to learn, grow and work with great people and this has been a really amazing experience for me.

Aaron: Okay, great. Mike, that’s the end of the interview. Thank you for your time today!

Learning from the First Wave Part 1: How Law Shapes the California Cannabis Industry

By Todd Feldman
No Comments

As a cannabis lawyer, I spend a lot of time thinking about the ways that regulations affect a cannabis company’s bottom line. Since I’m in California, the ways are many.

In late 2017 I became the chief compliance officer for an Oakland startup that carried out delivery, distribution, cultivation and six manufacturing operations. A big part of my job was preparing my company, along with several equity cannabis companies, for California’s First Wave of cannabis licenses.

For the most part, First Wave licensees came from California’s essentially unregulated medical cannabis market, and/or from California’s by-definition unregulated “traditional” market. When California began issuing licenses in January 2018, many First Wavers were unprepared because their businesses practices had evolved in an unregulated market. A big part of my job was to help them adapt to the new requirements. As a result, I saw the regulations, and the effects of regulations, in sharp relief.

Regulation touches virtually every aspect of the legal cannabis industry in California. So anyone who wants to understand the industry should have at least a basic understanding of how the regs work. I’m writing this series to lay that out, in broad strokes.

Some key points:

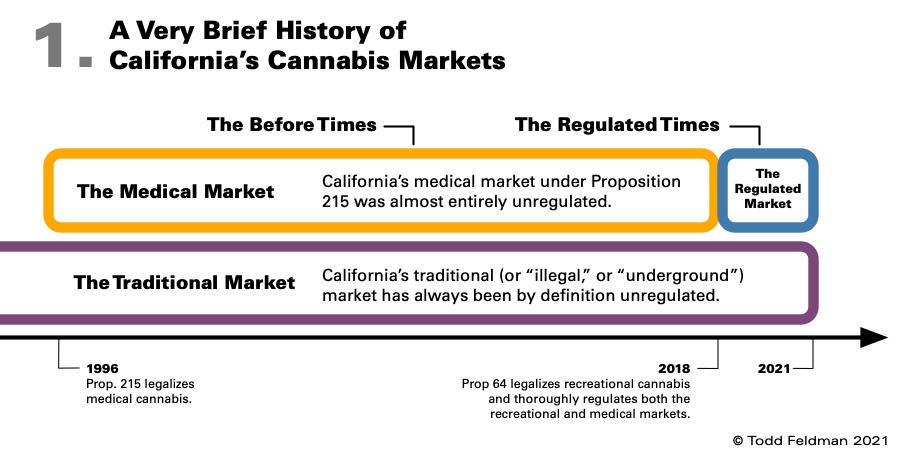
  • The regulated market must be understood in relation to the previous unregulated (medical) market as well as the ongoing traditional market.
  • Regs define the supply chain.
  • Regs are designed to ensure product safety and maximize tax revenue.
  • Many regulations mandate good business practices.
  • Local enforcement of building, health and safety codes tends to be zealous and costly.

A Tale of Three Markets

California’s regulated cannabis market can only be understood in relation to the medical market that preceded it, and in relation to the traditional market (illegal market) that continues to compete with it.

The Before Times

California’s legal medical cannabis market goes back to 1996, when the Compassionate Use Act passed by ballot measure. One fact that shaped the medical market was that it was never just medical – while it served bona fide patients, it also served as a Trojan horse for adult-use (recreational) purchasers.

Another fact that shaped the medical market was a near complete lack of regulation. On the seller’s side, you had to be organized as a collective. On the buyer’s side, you had to have a medical card. That was it.

Meanwhile, the cannabis supply chain was entirely unregulated. This tended to minimize production costs. It also meant that a patient visiting a dispensary had no way of verifying where the products had been made, or how.

The Regulated Times

Licensing under the Medical and Adult-Use Cannabis Regulation and Safety Act (the “Act”) began on January 1, 2018. It was the beginning of legal adult-use cannabis in California. It was also the beginning of the Regulated Times, as the Act and accompanying 300-plus pages of regulations transformed the legal cannabis market.

 For example:

  • The Act defines the cannabis supply chain (as a series of licensees).
  • Across the supply chain, the internal procedures of cannabis companies are subject to review by state agencies;
  • Cultivators and manufacturers cannot sell directly to a dispensary – they must go through a distributor;
  • All cannabis must be tested for potency and a long list of contaminants by a licensed testing laboratory before it may be sold to consumers;
  • And beginning in 2019, all licensees were required to participate in the California Cannabis Track and Trace (CCTT) program, which is designed to track all cannabis from seed to sale.

Just as importantly, the Act establishes a dual licensing system – that is to say, in order to operate, a cannabis company needs a local permit (or other authorization) as well as a state license. In fact, local authorization is a prerequisite for a state license. And your local jurisdiction will have its own rules for cannabis that apply in addition to the state rules, up to and including a ban on cannabis activities.

Needless to say, operating in the Regulated Times is a lot more complicated and expensive than it was during the Before Times.

Especially when you consider the taxes. For example, in the City of Los Angeles, sale of adult-use cannabis is taxed at 10%, which means that any adult-use purchase in L.A. gets a 34.5% markup:

  • 15% state cannabis excise tax, plus
  • 10% Los Angeles Adult Use Cannabis Sales tax, plus
  • 5% sales tax.

Note that the distributors must collect the excise tax from the retailer, so the 15% markup is not necessarily visible to the consumer. Similarly, consumers are generally unaware that there is a cultivation tax of $9.65 per ounce (or about $1.21 per eighth) of dried flower that the distributor has to collect from the cultivator.

Theoretically, all of this might be unproblematic if licensed retailers were only competing with each other. Which brings us to:

The Traditional Market

The traditional market is the illegal market, which is to say, the untaxed and unregulated market.

Legalization of adult-use cannabis was supposed to destroy the traditional market, but it hasn’t. As of early 2020, the traditional market was estimated to be 80% of the total cannabis market in California. This is not surprising, since the traditional market has the advantages of being untaxed and unregulated.

The traditional market has a pervasive negative effect on the legal market. For example, the traditional market tends to depress prices in the legal market and tends to attract talent away from the legal market. Some of these effects will be discussed in the following articles.

This article is an opinion only and is not intended to be legal advice.

CA Health and Safety Warning Laws Have Changed: Are You In Compliance?

By Megan Caldwell, Lindy Martinez
1 Comment

A new California Proposition 65 mandate took effect on January 3, requiring health warning labels for all cannabis products sold in the state. Failure to comply with the requirements can and will result in enforcement against cannabis producers and sellers, resulting in hefty penalties. Here’s what you need to know.

Some Background on Proposition 65 and Cannabis

California’s Proposition 65, also known as the “Safe Drinking Water and Toxic Enforcement Act of 1986,” requires various parties in the supply chain for consumer products to provide warnings on products they sell in the state if exposure to certain chemicals in those products will pose a significant risk of cancer or reproductive harm. Proposition 65 applies to any company that sells products in California, regardless of whether the business is headquartered or manufactures products in California.

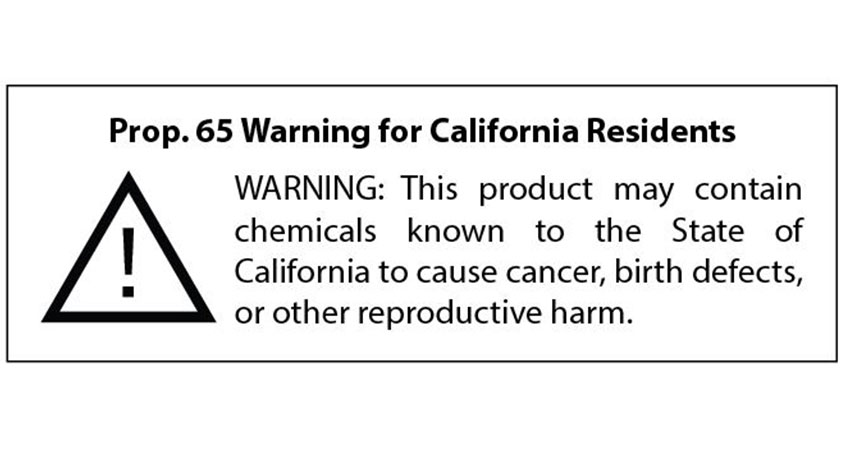
This is an example of a Prop 65 warning label. They might look familiar because we tend to see them on a lot of common goods and products.

“Cannabis (Marijuana) Smoke” was listed under Proposition 65 in 2009 because of the potential that it contains ingredients or emits chemicals known to cause cancer. These chemicals include toxins such as arsenic, benzene, cadmium, formaldehyde, lead and nickel. In January 2020, Delta-9-Tetrahydrocannabinol (THC) was added to the list of toxic chemicals under Proposition 65 because of THC’s potential to cause reproductive harm. Now, both THC and cannabis smoke are listed under Proposition 65 and require warning labels.

What This Means for You and Your Company

The updated chemical list, which includes THC, became effective January 3, 2021, so the clock to come into compliance is ticking if you are not already complying. Many cannabis companies selling in California already comply with Proposition 65 by including warnings on their products that emit cannabis smoke. However, now companies that have previously issued a consumer warning regarding cannabis smoke must expand their warnings to include both the potential risk of cancer and the potential risk of reproductive harm. Additionally, products that previously did not require a warning for cannabis smoke will now be subject to Proposition 65 for exposure to THC.

The listing of THC implicates a broader range of cannabis products because it affects any product that contains detectable levels of THC, including products that contain less than 0.3% THC in compliance with the 2018 Farm Bill. Under the THC listing, a wide range of cannabis and hemp-derived CBD products, including products that do not emit smoke, such as edibles, topicals and other concentrates are subject to the Proposition 65 labeling requirements.

The agency that oversees Proposition 65 has provided so-called “safe harbor” levels for many listed chemicals that allow companies to forego a warning label if exposure to the chemical occurs at or below a certain threshold. However, no safe harbor level has been established for cannabis smoke or THC, and so the burden falls to the business to determine if the levels of the chemical pose a significant risk to the consumer. This determination typically requires extensive and costly testing that is not practical for most businesses. Thus, parties in the cannabis supply chain should work to properly label all cannabis-related products at this time. Failure to do so is risky. Proposition 65 “bounty hunters” team up with individuals to enforce Proposition 65 by sending notice of violation letters and then often filing lawsuits against businesses they believe are in violation of the statute. Many of these demands and lawsuits settle, as the cost to litigate is expensive. Settling, though, can be expensive, too.

Updates in Employment Law: CA, WA & CO

By Conor Dale
No Comments

A number of laws have gone into effect in 2021 which may have a major impact on cannabis industry employers; clearly understanding the changing legal landscape is essential to avoid and limit potential liability in the new year and beyond. Below is a brief summary of some relevant new employment laws in cannabis friendly states:

California:

  • Expansion of family and medical leave: California has long required employers to provide job protected medical and family leave if an employee worked at a jobsite with 50 or more employees within a 75-mile radius.
  • Senate Bill 1383 now requires all employers with five or more employees to provide up to twelve weeks of unpaid, job-protected leave for employees to bond with a new child or to care for themselves or a family member suffering from a serious health condition. To be eligible for the leave, an employee must have at least 12 months of service with the employer and have performed at least 1,250 hours of work in the previous 12-month period. While on leave, employees are entitled to continue to participate in an employer’s health insurance plan and to return to their job or a comparable position at the conclusion of their job-protected leave. Previously exempt small employers should be aware of these obligations moving forward.
  • Employer Pay Reporting Requirements: Under Senate Bill 973, employers with 100 or more employees that are required to file an annual Employer Information Report, colloquially known as the EEO-1 report, must submit annual information on its employees’ pay data to the state’s Department of Fair Employment and Housing (DFEH). The report must include the number of the employer’s employees by race, ethnicity and sex in specific job categories and pay ranges and their associated work hours and earnings.
  • The first report is due on March 31, 2021, and the DFEH has prepared an online portal to assist employers in submitting this information. These reports can be complex and address highly sensitive information, so employers are strongly advised to contact counsel for assistance in preparing and submitting their first report.

Washington

  • Increased pay requirements: Washington’s inflation-based minimum wage system has increased the minimum wage to $13.69 per hour in 2021. Employers with 50 or fewer employees must also pay salaried employees at least $827 per week (or $43,004 per year) and employers with more than 50 employees must pay at least $965 per week (or $50,180 per year) starting January 1st.

Colorado

  • Equal Pay for Equal Work Act: Beginning in 2021, all employers with at least one employee must: (1) provide formal notice to Colorado employees of promotional opportunities; and (2) disclose pay rates or ranges in job postings that could be performed in Colorado (this includes virtual or remote work positions).
  • The Equal Pay for Equal Work Act generally requires employers to take reasonable efforts to promptly announce, post, or otherwise communicate all opportunities to all current employees prior to making a promotion decision. An employer must communicate promotional opportunities when it has or anticipates a vacancy or a new position that could be considered a promotion for current employees in light of pay, benefits, status, duties or further potential promotions.
  • Under the law, job postings must also include: (1) the rate of pay or pay range for the position; (2) a general description of bonuses, commissions or other forms of compensation offered with the job; and (3) a description of the employment benefits associated with the position.

Cannabis industry employers face a range of new laws, even absent the continued legal burden of managing employees during the COVID 19 pandemic. Employers should consider carefully reviewing all applicable laws and seeking guidance from counsel when needed.

Cannabis M&A in the Post-COVID Era

By Jose Sariego
No Comments

After a slow start following a disappointing 2019, M&A in the cannabis space closed 2020 with a bang, with more than $600 million in deals announced immediately following the November elections. Prospects for the New Year are expected to continue the explosive year-end trend with a backlog of nearly $2 billion in deals heading into 2021. The COVID-19 pandemic boosted sales of cannabis products, and election results opening up five new states to legal cannabis use and possible federal regulatory reform are further boosting prospects. Analysts now predict the U.S. cannabis market is poised to double by 2025.

Growth is expected to be led by multi-state operators who have achieved scale, cleaned up their balance sheets and stockpiled dry powder for roll-up acquisitions. Cannabis companies raised nearly $134 million in the two weeks before Election Day, a 185% increase over the same period last year. Most of the money flowed to multistate operators. In addition, the biggest stocks by market capitalization saw a roughly 20% bump ahead of the election and now are trading at record volumes, providing plenty of stock currency for further acquisitions.

Among the headline acquisitions last year:

  • Curaleaf continued its multi-state expansion with two of its largest acquisitions – the all-stock purchases of its affiliated cannabis oil company Select and of Grassroot, another MSO player. Curaleaf is now the largest cannabis company in the world based on annualized revenues, with annualized sales of $1 billion and operations in 23 states and 96 open dispensaries. Curaleaf also raised $215 million privately last year end for further expansion.
  • Close behind, Aphria and Tilray announced in December that they will merge, creating what they say will be the largest cannabis company in the world with an equity value of roughly $3.8 billion. The combined entity will have facilities and offices in the U.S., Canada, Portugal and Germany. The deal is expected to close during the second quarter of this year.
  • Also in December, Illinois-based Verano Holdings LLC unveiled plans to go public at a $2.8 billion valuation through a reverse takeover of a Canadian shell company. That deal followed the announcement that Verano will merge with Florida-based AltMed.
  • In addition, publicly traded New York cannabis firm Columbia Care signed a definitive agreement last month to acquire Green Leaf Medical, a privately held Maryland-based cannabis manufacturer and retailer, for $45 million in cash and $195 million in stock. The acquisition is expected to close this summer. Including Green Leaf’s inventory, the Columbia Care will operate 107 facilities, including 80 dispensaries and 27 cultivation and manufacturing facilities. Columbia Care also took advantage of cannabis fever last year by raising $100 million privately.
  • Also in December, Ayr Strategies announced it would acquire Liberty Health Sciences, one of the largest cannabis companies in Florida, for $290 million in stock, as well Garden State Dispensary, a New Jersey marijuana company for $41 million in cash, $30 million in stock and $30 million in the form of a note. This follows Ayr’s $81 million acquisition of an Arizona medical marijuana operator in November. Voters approved marijuana use in Arizona and New Jersey in November.  Ayr has completed a string of acquisitions in Nevada, Massachusetts, Pennsylvania, Arizona, Ohio and, upon the closing of December’s deals, New Jersey and Florida.

Not all cannabis companies will rely on acquisitions, however. Trulieve, as an example, has focused its efforts on Florida and organic growth. It remains to be seen whether a multi-state approach fueled by acquisitions or a single-state organic growth model will prove the more lasting. Growth and profitability in the short term likely will continue to be hampered by limits on economies of scale due to federal restrictions and differing state laws.

In light of the maturing industry and the 2019 bust, the valuation model for acquisitions in the cannabis space is evolving from one based on sales, typically associated with emerging growth industries, to a more mature industry model based on profits or Earnings Before Interest, Taxes, Depreciation, and Amortization (EBITDA). Most cannabis MSOs have stabilized and generate positive EBITDA, which justifies the evolution away from a sales-driven model.

From a legal standpoint, the same limitations that have vexed the cannabis industry for years will continue to challenge deal makers until there is greater clarity on the federal front. Institutional investor reluctance, financial industry constraints, haphazard state regulation and the unavailability of federal forums such as national copyright and trademark registration will continue to be issues for acquirers and their lawyers in the space.

Acquisition agreements will continue to have to address the federal Damocles’ sword should expected relaxation of federal enforcement under the Biden administration and further legislative relief does not materialize as expected. Although the U.S. House in December passed the “Marijuana Opportunity Reinvestment and Expungement Act” (MORE) to remove cannabis from the Controlled Substances Act, the Senate did not take up the bill in 2020 and it will have to be re-introduced in 2021. Notably, the MORE Act does not affect existing federal regulation of cannabis, such as the Food, Drug and Cosmetics Act, under which the FDA has limited the use of CBD in certain products despite hemp being removed from the Controlled Substances Act in 2018.

The cannabis M&A market is moving into a more mature phase, as MSOs will be choosier in their approach rather than continuing the land-grab mentality of years past. Due to improved financial strength, 2021 should see these MSOs continuing to expand their footprints either within existing states or new ones. Although uncertainties abound, further consolidation and expansion through add-on acquisitions is likely to continue apace in 2021, providing plenty of opportunities for deal makers and their lawyers.

New Trade Organization Launches: The Sustainable Cannabis Coalition

By Cannabis Industry Journal Staff
2 Comments

According to a press release published today, a number of businesses in the cannabis cultivation market have announced they are launching the Sustainable Cannabis Coalition (SCC). The group’s purpose is to “measure, document and improve sustainable cannabis cultivation and manufacturing through education and proliferation of best practices.”

The SCC founding members include: ​Cohn Reznick​, ​Anderson Porter Design​, ​Valiant​, ​Wholly H2O​, ​Cloud Farming​, ​Argus Controls​, ​Conviron, Gro iQ​, ​Trulieve​, ​Byers Scientific​, ​365 Cannabis​, GMP Collective​, ​Omega Equipment and Supply​, ​Simplifya​, ​PathogenDx,​ Grow Generation​ and ​Outlaw Technology​.

The press release says that the SCC will work with industry stakeholders to promote environmental sustainability best practices that can be implemented at scale. “The SCC will be a trusted resource providing foundational best practices to further promote economic benefits of sustainability as the industry continues to grow.”

The SCC will begin its campaign by publishing informative blog posts and podcast interviews on a biweekly basis, with plans to address each vertical in the cultivation and manufacturing supply chain, highlighting environmental sustainability best practices.

According to Peter Dougherty, CEO of Gro IQ and co-founder of the SCC, their mission is to get leaders in the industry to collaborate on promoting the best ways for businesses to become more sustainable. “We will accomplish this by having our founding members companies, which

represent every major link in the cannabis cultivation, manufacturing and distribution supply chain, provide data driven business cases for sustainability based on their area of expertise and then amplifying that content through each other’s websites and social media channels,” says Dougherty.

“With investors across the industry incorporating Environmental, Social and Governance (ESG) factors into the investment process, the creation of a coalition to address sustainability in this space is critical,” Dougherty says. “​The SCC is uniquely poised to impact the industry as it continues to rapidly evolve. As leaders in this space, it is our responsibility to provide data driven sustainability guidance to the industry while protecting both consumers and the environment.”

Their content will be available for free to anyone on their website. Dougherty says they have already received a tremendous amount of interest prior to the launch, so he expects their sphere of influence to expand rapidly.

As of now, the SCC serves as an informal coalition among businesses with no plans to expand too much beyond their current size. The primary goal is dissemination of educational content to start. However, they do encourage folks to check out their website and sign up.