Tag Archives: Green Check Verified

Your Banking Problem Is a Margin Problem

By Stacy Litke
No Comments

Most cannabis operators have a banking problem. For many, that means limited access to financial services, forcing the business to operate largely in cash and be unable to use the standard banking rails every other industry takes for granted. The banking conversation in this industry almost always stops at access. Can the business get an account? Can it keep one? 

Those are real questions, and the answer to both is yes, but they are the wrong ones to stop at. The conversation should continue into how the business is actually functioning within whatever banking access it has, and whether that access is doing the work the business needs. Having some banking is not the same as having a dependable financial infrastructure, and the gap between them does not stay confined to the finance department. It bleeds into operations, labor, vendor relationships, and growth capacity in ways most operators have never stopped to calculate. 

Every margin leak described in the following sections traces back to a banking infrastructure failure, even though none of them are ever labeled that way in a report. Courier costs, absorbed labor hours, vendor friction, untracked losses- these get filed under operations, staffing, or shrinkage. The banking infrastructure that produced them is never identified as the source, and the margin problem remains invisible because no one is looking for it in the right place.


The Costs You Can See

The visible margin hits are straightforward. Cash-heavy operations mean armored transport, on-site storage, and security overhead that eats into the bottom line before the day starts. Because cannabis businesses are largely locked out of standard card processing networks, payment acceptance gets pieced together across alternative solutions that were never designed to work together, creating fragmentation that requires manual reconciliation to function at all. Finance teams spend hours every week manually assembling a cash picture that a business with reliable banking would simply have.

Labor is where the repercussions from limited banking access take their most direct toll on the operation. A store manager spending two or three hours per shift on cash management instead of coaching staff, solving operational problems, or running a tighter floor, a meaningful portion of their shift is absorbed by a process that exists only because the financial infrastructure requires it. At one store, it can be seen as a minor inconvenience. Across ten stores, it is a structural margin drag that never shows up as a line item but absolutely shows up in store performance, team development, and the operator’s ability to keep leadership focused on growth rather than logistics.


The Costs That Never Show Up on a Report

The costs that do not show up in any report tend to be the ones that cause the most damage over time, because they are never attributed to the right source.

Consider what happens when a finance team cannot see the business’s cash position in real time. Forecasting becomes an exercise in approximation built on information that is already two days old. A vendor payment gets timed incorrectly, not because anyone made a bad decision, but because the visibility to make a good one was not there. Each of these feels like an operational problem in the moment. None of them gets logged as a banking problem, which means the root cause never gets addressed, and the friction keeps recurring.

The vendor dimension is the most underestimated consequence. Suppliers do not announce when they have decided an operator is a payment risk. They adjust quietly, building uncertainty into how they price, how much credit they extend, and how quickly they respond. An operator managing cash-heavy, fragmented operations for years may have no idea that their margins with key suppliers are softer than they should be, or that better-banked competitors are getting more favorable terms. That gap does not show up anywhere. It just slowly erodes the economics of relationships that the business depends on.

At one or two locations, all of this feels manageable. A small finance team can hold the whole picture in their heads. Scaling changes that entirely. Five stores do not produce five times the reconciliation burden of one. They produce a fundamentally different problem: each location adds its own exceptions, timing variances, and failure points. At some point, the workaround becomes the business model, not by design but by default, and the cost accumulates in a margin that never materializes and in growth that lags behind what the market is offering.


Choosing the Right Financial Partner

Moving toward dependable financial infrastructure starts with finding the right institution, and that search has a predictable failure mode worth naming. Two patterns come up consistently when cannabis operators end up losing banking access. The first is choosing an institution that was never genuinely comfortable with the business model to begin with, and the second is opening an account under a name that seems ambiguous enough to fly under the radar. That rarely works. Transaction activity, including high cash volumes and interactions with known cannabis payment systems, gets flagged, and accounts get closed. A search for cannabis-friendly banking options will surface legitimate institutions. The focus should be on finding one that understands and is genuinely comfortable with the business model.

The second mistake is evaluating options on monthly fees alone. Understanding the full service menu matters more than the base rate. Wires, ACH, loans, and other services may not be needed immediately, but knowing their costs before the business needs them in a hurry prevents costly surprises. A $2,500 wire fee at the wrong moment is the kind of thing that leaves a mark.


Where the Margin Lift Actually Comes From

The fastest margin improvement typically comes from moving bill payments, tax obligations, and payroll onto traditional rails such as ACH or checks. Reducing the volume of cash moving through the operation reduces courier fees, cash handling overhead, and the security exposure that comes with it. Working with an accountant who understands cannabis, and specifically the implications of cash-heavy operations, surfaces losses that are genuinely hard to see when everything runs through cash. Duplicate payments, theft exposure, and untracked expenses are consistent findings when operators finally get everything documented and reconciled.

There is also a longer-term dimension worth naming. When financial activity is fully documented, the operator is in a materially better position with lenders, investors, and their own accountant. Demonstrating sales, revenue, and expenses clearly is increasingly important as the regulatory environment evolves, including for medical operators navigating the recent changes to 280E disallowance, where a complete payment audit trail is what makes claiming expenses possible.

Most operators have never added up what their current setup is actually costing them in labor hours, management capacity, and forecasting accuracy. When they do, the number is bigger than expected, and the conversation about banking stops being about compliance and starts being about margin, where it should have been from the beginning.

$1.3 Billion/Month Later: What Cannabis Banking Has Really Taught Us

By Kevin Hart
No Comments

A decade ago, most banks wouldn’t touch a cannabis business. Whenever banking access came up, the discussion stopped almost immediately. People said it was too risky, too unclear, or that the timing just wasn’t right.

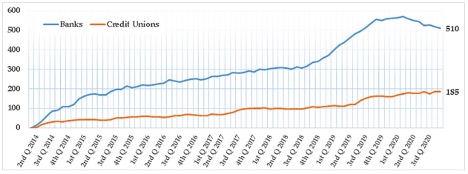
Today, Green Check has over 180 financial institutions across the U.S. that actively serve more than 17,000 licensed operators. Together, those relationships represent more than $1.3 billion in legal, transparent cannabis transactions every month. That number tells a story of progress, not just for financial access, but for normalization.

It’s also revealed, through years of trial and adjustment, what actually works in cannabis banking, and what doesn’t.


From “No Way” to “How Do We Do It?”

The most significant shift hasn’t been in cannabis banking laws; it’s been in mindset. Five years ago, most financial institutions viewed cannabis as a compliance nightmare. Today, the more common attitude is cautious curiosity: “How do we enter safely, and who can help us understand the rules?”

That change came from proximity. After reviewing the data themselves, many banks realized cannabis operators were outliers. They were small business owners balancing compliance checklists that would make most industries sweat. What seemed risky on paper turned out to be ordinary once they saw how the work was actually done.

In short, the more the financial system learned, the less it feared.


Where Banking Works and Where It Still Doesn’t

In mature markets, access to banking has become stable and predictable. For compliant operators, maintaining a transparent account is no longer the exception. In newer states, however, the pattern still repeats: financial institutions hesitate, regulations move slowly, and businesses open their doors before they have access to a secure account.

The gap is widest for early-stage operators, those still seeking licenses or building facilities. These companies often can’t yet show revenue or deposits, making them less appealing to institutions that prefer an established track record. Yet those early relationships are exactly what can prevent later compliance issues. Bridging that gap through education on both sides remains one of the most urgent needs in the ecosystem.


The Data Behind $1.3 Billion per Month 

At this scale, some clear patterns emerge. The strongest cannabis banking relationships all share one trait: they feel ordinary. When operators and financial institutions stop talking about “banking cannabis” and simply talk about “banking,” that’s a sign the system works.

Predictability defines maturity, and transparency drives growth. Businesses that keep clean records, communicate openly with their financial partners, and proactively share compliance documentation not only retain accounts longer but also gain faster access to credit. Over the past year, deposit growth has risen sharply, and lending programs are expanding. Roughly four in ten institutions that serve cannabis now offer lending, a number that continues to climb as confidence grows.

Lending, after all, is where healthy banking relationships evolve. When both sides trust the data, money can finally move in both directions.


Misconceptions That Still Get in the Way

Among operators, one misconception persists: that banking should be free. It’s understandable; it’s their revenue after all, but maintaining compliance requires real infrastructure. Cannabis banking involves transaction monitoring, due diligence, and ongoing regulatory reporting. Those processes take time and resources that extend well beyond traditional business accounts.

On the other side, financial institutions still harbor myths that cannabis is inherently unsafe or tied to bad actors. In reality, licensed cannabis businesses are among the most heavily regulated in the economy. Every product, sale, and employee is documented. When banks apply the same standards they use in other industries and rely on data rather than perception, the risk profile becomes far less intimidating.

The greatest barrier now isn’t legality or even compliance; it’s outdated assumptions.


What Regulators Still Miss

From the ground level, one truth is clear: cannabis banking already works. It’s safe, compliant, and scalable when structured correctly. What regulators and policymakers often underestimate is how much of this progress has happened under existing frameworks.

Licensed operators are not waiting for permission; they are building systems within the rules available to them. Every compliant account represents millions of dollars that are now traceable, reportable, and integrated into the financial system,  the exact outcomes policymakers claim to want.

The call for reform isn’t about possibility; it’s about consistency. Federal guidance that aligns with state programs would reduce friction, expand access, and make it easier for small businesses, not just multistate operators, to participate safely.


What Comes Next

The next chapter of cannabis banking won’t be about opening more accounts; it will be about connecting systems. As markets mature and interstate commerce edges closer, financial institutions will need tools that link compliance, payments, lending, and reporting into a single framework. Manual processes won’t scale in a multi-state or federal model.

The institutions that succeed will be those that think beyond deposits and fees, viewing cannabis as a long-term business segment rather than a compliance project. The operators that thrive will be those who treat transparency as an asset, not a burden.

And for policymakers, the opportunity lies in learning from what already works. Real-world data shows that compliant banking strengthens communities, reduces risk, and provides law enforcement and regulators with clearer oversight than any cash-based system could.


Lessons from the First Billion

Looking back, the first billion dollars in cannabis banking wasn’t defined by profit; it was defined by proof. It proved that local institutions could safely serve a federally restricted industry. It proved that compliance could scale, and it proved that stigma, once confronted with data, tends to lose its power. The next billion will be defined by connection: connecting data to credit, operators to opportunity, and policymakers to evidence.

If there’s one lesson worth carrying forward, it’s this: the closer we get to transparency, the further we move from fear. This is how legitimacy takes root, not through legislation alone, but through everyday practice, repeated a billion dollars at a time.

Compliance as a Revenue Center: Banking & Cannabis, More Similar Than You Think

By Kevin Hart
No Comments

Have you ever been to the DMV, only to be turned away because you didnt have the countless forms of identification needed? Sometimes it feels like no amount of ID or proof of residence is enough, whether its your 2nd grade report card or an electric bill from 25 years ago.

That feeling is what its like for anyone working in compliance; regardless of industry. Banks are no different. They need to possess compliance documents such as Consolidated Reports of Condition and Income and other Federal Financial Institutions Examination Council (FFIEC) reports that work like the laundry list of documents you need to get a drivers license or get your car registered.

The same can be said for newly licensed and legal cannabis companies. They often need state and local inspection documents, federal background checks and a list of other documents that make a CVS receipt look minuscule in comparison.

Historically, across all industries, the whole process of gathering and providing these sorts of documents can turn into a bit of a charade. Many companies do the bare minimum to check the compliance box and achieve certifications. Various teams and stakeholders try to skate through the compliance process by providing answers that reflect what they think the enterprise customer wants to see (vs. the reality).

In order to achieve long term growth, financial institutions (FIs) and cannabis companies alike need to start executing compliance plans. FIs are always seeking new growth and revenue opportunities, and cannabis companies are constantly under the scrutiny of regulators. Identifying new solutions that can help companies grow quickly while also maintaining compliance should be an essential part of the roadmap.

Financial Institutions and Cannabis

Many think that financial institutions and cannabis businesses would be on opposite ends of any spectrum. Banking is a mature and established industry, while legal cannabis is a new, fast moving and constantly evolving space. So, on one side, there is a risk averse fiscally conservative and traditional business model, and on the other side is an industry that is outside of the mainstream.

Lets look at this perception from a different angle though. What is true is that both industries are highly regulated and must comply with the rules placed upon them by regulators; and if their house isnt in order, the consequences can be disastrous (Read: Massive fines or even losing the ability to operate). CRBs and FIs deal with the security and dual control of inventory, and making sure customers are properly identified and of legal capacity to conduct business. In most cases, both are small businesses within their respective communities. ‍

Moreover, each of the industries are forced to navigate nearly-constant regulatory change, making the act of complying with applicable regulations a moving target. For most of these types of businesses, regulatory compliance is cited as one of the largest (and most expensive) challenges they face in day-to-day operations.

Compliance as Revenue Protection 

When financial institutions make the decision to offer services to the cannabis industry, they naturally look at the market opportunity to determine whether the effort associated with the increased compliance obligations outweigh the potential benefits. Traditionally, compliance is viewed as a cost center, but in reality, its a revenue protection center. As the old saying goes; an ounce of prevention is worth more than a pound of cure.” Compliance is that prevention.

Cannabis companies need to demonstrate reliability and a history of compliance in order to attract investors and accumulate capital

Failing to fully comply and meet regulatory compliance standards can cost organizations billions. Having a trusted system of compliance established should not be looked at as a cost-sucking measure for businesses, when it really is negligible when the cost of getting it wrong is far more substantial. Setting up a truthful and transparent compliance program isnt just the right thing to do, it also protects revenue.

As the cannabis industry continues to grow, navigating around pain points is becoming increasingly expensive for the companies participating in it, many of whom are still struggling to turn a profit. Specifically, an IDC forecast shows global revenue from GRC solutions growing from $11.3 billion in 2020 to nearly $16.2 billion by 2025. And the average business hires and spends upward of $50,000 to $200,000 on consultants to manage compliance. Its not uncommon for companies to dedicate five to 10 people working on compliance every week for hours and months on end.

Many in the banking industry are worried about forging into a stigmatized stream of revenue like cannabis, but with the right compliance solutions in place, they can have peace of mind. These solutions guarantee that revenue from cannabis is done legally by analyzing where each dollar came from, and denying those that dont meet the minimum criteria. Having visibility into cannabis-related business (CRBs) accounts that do the enhanced due diligence is the only way to operate.

By implementing purpose-built compliance management solutions, financial institutions are able to unlock new revenue streams and scale cannabis banking operations. Meaning that as cannabis continues to gain mainstream momentum, and becomes less scrutinized locally and federally, these FIs that take part will be ahead of the curve. 

Looking Ahead

With recent movement towards legalization in the House, cannabis investors are optimistic about the industrys future. So how can the cannabis market overcome these hurdles and remain highly profitable?

To start with, CRBs must have greater access to accredited financial institutions like banks and credit unions. Owning bank accounts, obtaining credit cards, and applying for small business loans is essential to growth. Providing CRBs with access to proper financial support and compliance control is crucial for the cannabis market to continue to thrive.

Federal legislation such as the SAFE Banking Act is currently thought of to be the silver bullet that will open the floodgates for CRBs and FIs to work together. But in reality, this is a myth, as the SAFE Banking Act will simply make the current compliance rules stricter.

To be a first mover FI in your area, businesses must start by implementing a scalable, verifiable cannabis banking program. The real customers and financial opportunities are out there, and are even greater than what you might have modeled given the growth of the industry. The ability to do this today is real.