Have you ever been to the DMV, only to be turned away because you didn’t have the countless forms of identification needed? Sometimes it feels like no amount of ID or proof of residence is enough, whether it’s your 2nd grade report card or an electric bill from 25 years ago.
That feeling is what it’s like for anyone working in compliance; regardless of industry. Banks are no different. They need to possess compliance documents such as Consolidated Reports of Condition and Income and other Federal Financial Institutions Examination Council (FFIEC) reports that work like the laundry list of documents you need to get a driver’s license or get your car registered.
The same can be said for newly licensed and legal cannabis companies. They often need state and local inspection documents, federal background checks and a list of other documents that make a CVS receipt look minuscule in comparison.
Historically, across all industries, the whole process of gathering and providing these sorts of documents can turn into a bit of a charade. Many companies do the bare minimum to check the compliance box and achieve certifications. Various teams and stakeholders try to skate through the compliance process by providing answers that reflect what they think the enterprise customer wants to see (vs. the reality).
In order to achieve long term growth, financial institutions (FIs) and cannabis companies alike need to start executing compliance plans. FIs are always seeking new growth and revenue opportunities, and cannabis companies are constantly under the scrutiny of regulators. Identifying new solutions that can help companies grow quickly while also maintaining compliance should be an essential part of the roadmap.
Financial Institutions and Cannabis
Many think that financial institutions and cannabis businesses would be on opposite ends of any spectrum. Banking is a mature and established industry, while legal cannabis is a new, fast moving and constantly evolving space. So, on one side, there is a risk averse fiscally conservative and traditional business model, and on the other side is an industry that is outside of the mainstream.
Let’s look at this perception from a different angle though. What is true is that both industries are highly regulated and must comply with the rules placed upon them by regulators; and if their house isn’t in order, the consequences can be disastrous (Read: Massive fines or even losing the ability to operate). CRBs and FIs deal with the security and dual control of inventory, and making sure customers are properly identified and of legal capacity to conduct business. In most cases, both are small businesses within their respective communities.
Moreover, each of the industries are forced to navigate nearly-constant regulatory change, making the act of complying with applicable regulations a moving target. For most of these types of businesses, regulatory compliance is cited as one of the largest (and most expensive) challenges they face in day-to-day operations.
Compliance as Revenue Protection
When financial institutions make the decision to offer services to the cannabis industry, they naturally look at the market opportunity to determine whether the effort associated with the increased compliance obligations outweigh the potential benefits. Traditionally, compliance is viewed as a cost center, but in reality, it’s a revenue protection center. As the old saying goes; “an ounce of prevention is worth more than a pound of cure.” Compliance is that prevention.
Cannabis companies need to demonstrate reliability and a history of compliance in order to attract investors and accumulate capital
Failing to fully comply and meet regulatory compliance standards can cost organizations billions. Having a trusted system of compliance established should not be looked at as a cost-sucking measure for businesses, when it really is negligible when the cost of getting it wrong is far more substantial. Setting up a truthful and transparent compliance program isn’t just the right thing to do, it also protects revenue.
As the cannabis industry continues to grow, navigating around pain points is becoming increasingly expensive for the companies participating in it, many of whom are still struggling to turn a profit. Specifically, an IDC forecast shows global revenue from GRC solutions growing from $11.3 billion in 2020 to nearly $16.2 billion by 2025. And the average business hires and spends upward of $50,000 to $200,000 on consultants to manage compliance. It’s not uncommon for companies to dedicate five to 10 people working on compliance every week for hours and months on end.
Many in the banking industry are worried about forging into a stigmatized stream of revenue like cannabis, but with the right compliance solutions in place, they can have peace of mind. These solutions guarantee that revenue from cannabis is done legally by analyzing where each dollar came from, and denying those that don’t meet the minimum criteria. Having visibility into cannabis-related business (CRBs) accounts that do the enhanced due diligence is the only way to operate.
By implementing purpose-built compliance management solutions, financial institutions are able to unlock new revenue streams and scale cannabis banking operations. Meaning that as cannabis continues to gain mainstream momentum, and becomes less scrutinized locally and federally, these FIs that take part will be ahead of the curve.
Looking Ahead
With recent movement towards legalization in the House, cannabis investors are optimistic about the industry’s future. So how can the cannabis market overcome these hurdles and remain highly profitable?
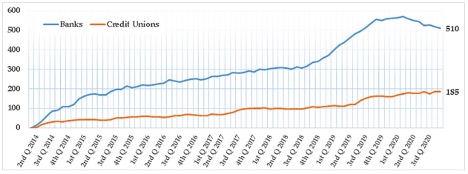
To start with, CRBs must have greater access to accredited financial institutions like banks and credit unions. Owning bank accounts, obtaining credit cards, and applying for small business loans is essential to growth. Providing CRBs with access to proper financial support and compliance control is crucial for the cannabis market to continue to thrive.
Federal legislation such as the SAFE Banking Act is currently thought of to be the silver bullet that will open the floodgates for CRBs and FIs to work together. But in reality, this is a myth, as the SAFE Banking Act will simply make the current compliance rules stricter.
To be a first mover FI in your area, businesses must start by implementing a scalable, verifiable cannabis banking program. The real customers and financial opportunities are out there, and are even greater than what you might have modeled given the growth of the industry. The ability to do this today is real.
2022 brought more change and visibility to the cannabis industry than nearly any year before. Two of five legalization ballot measures passed, bringing the total number of states with legal medical or medical and recreational laws to 39. President Biden issued an executive order pardoning nonviolent offenders and directing a review into rescheduling cannabis. The Medical Marijuana and Cannabidiol Research Expansion Act was enacted. Cannabis arose prominently in legislatures across the country, with over 50 federal bills and hundreds of state-level measures introduced.
We’ve yet to see the full impact from Biden’s October 6 announcement
But as 2022 came to a close, only a handful of actions are being carried into the new year, and the industry faces more hardship and turmoil than it has since the inception of legalization. Legal cannabis retailers and cultivators in markets across the country continue to struggle with onerous regulations and competition from the illicit market, and oversupply in these markets is driving down prices as West Coast growers and manufacturers anxiously await interstate commerce.
Looking ahead to the coming year, industry watchers can anticipate certain issues and legislation: further investigation into cannabis’ classification on the Controlled Substances Act (CSA) from federal agencies, federal cannabis pardons coming to fruition, a follow-up from the Department of Justice’s technical report, and the reintroduction of high-profile federal legislation, like the Cannabis Opportunity Act (CAOA), the States Reform Act, Marijuana Opportunity Reinvestment and Expungement (MORE) Act, Harnessing Opportunities by Pursuing Expungement (HOPE) Act and the Secure and Fair (SAFE) Banking Act.
Below, we recap some of the big moments of 2022 and what to expect in 2023.
A Presidential Pardon for Simple Possession
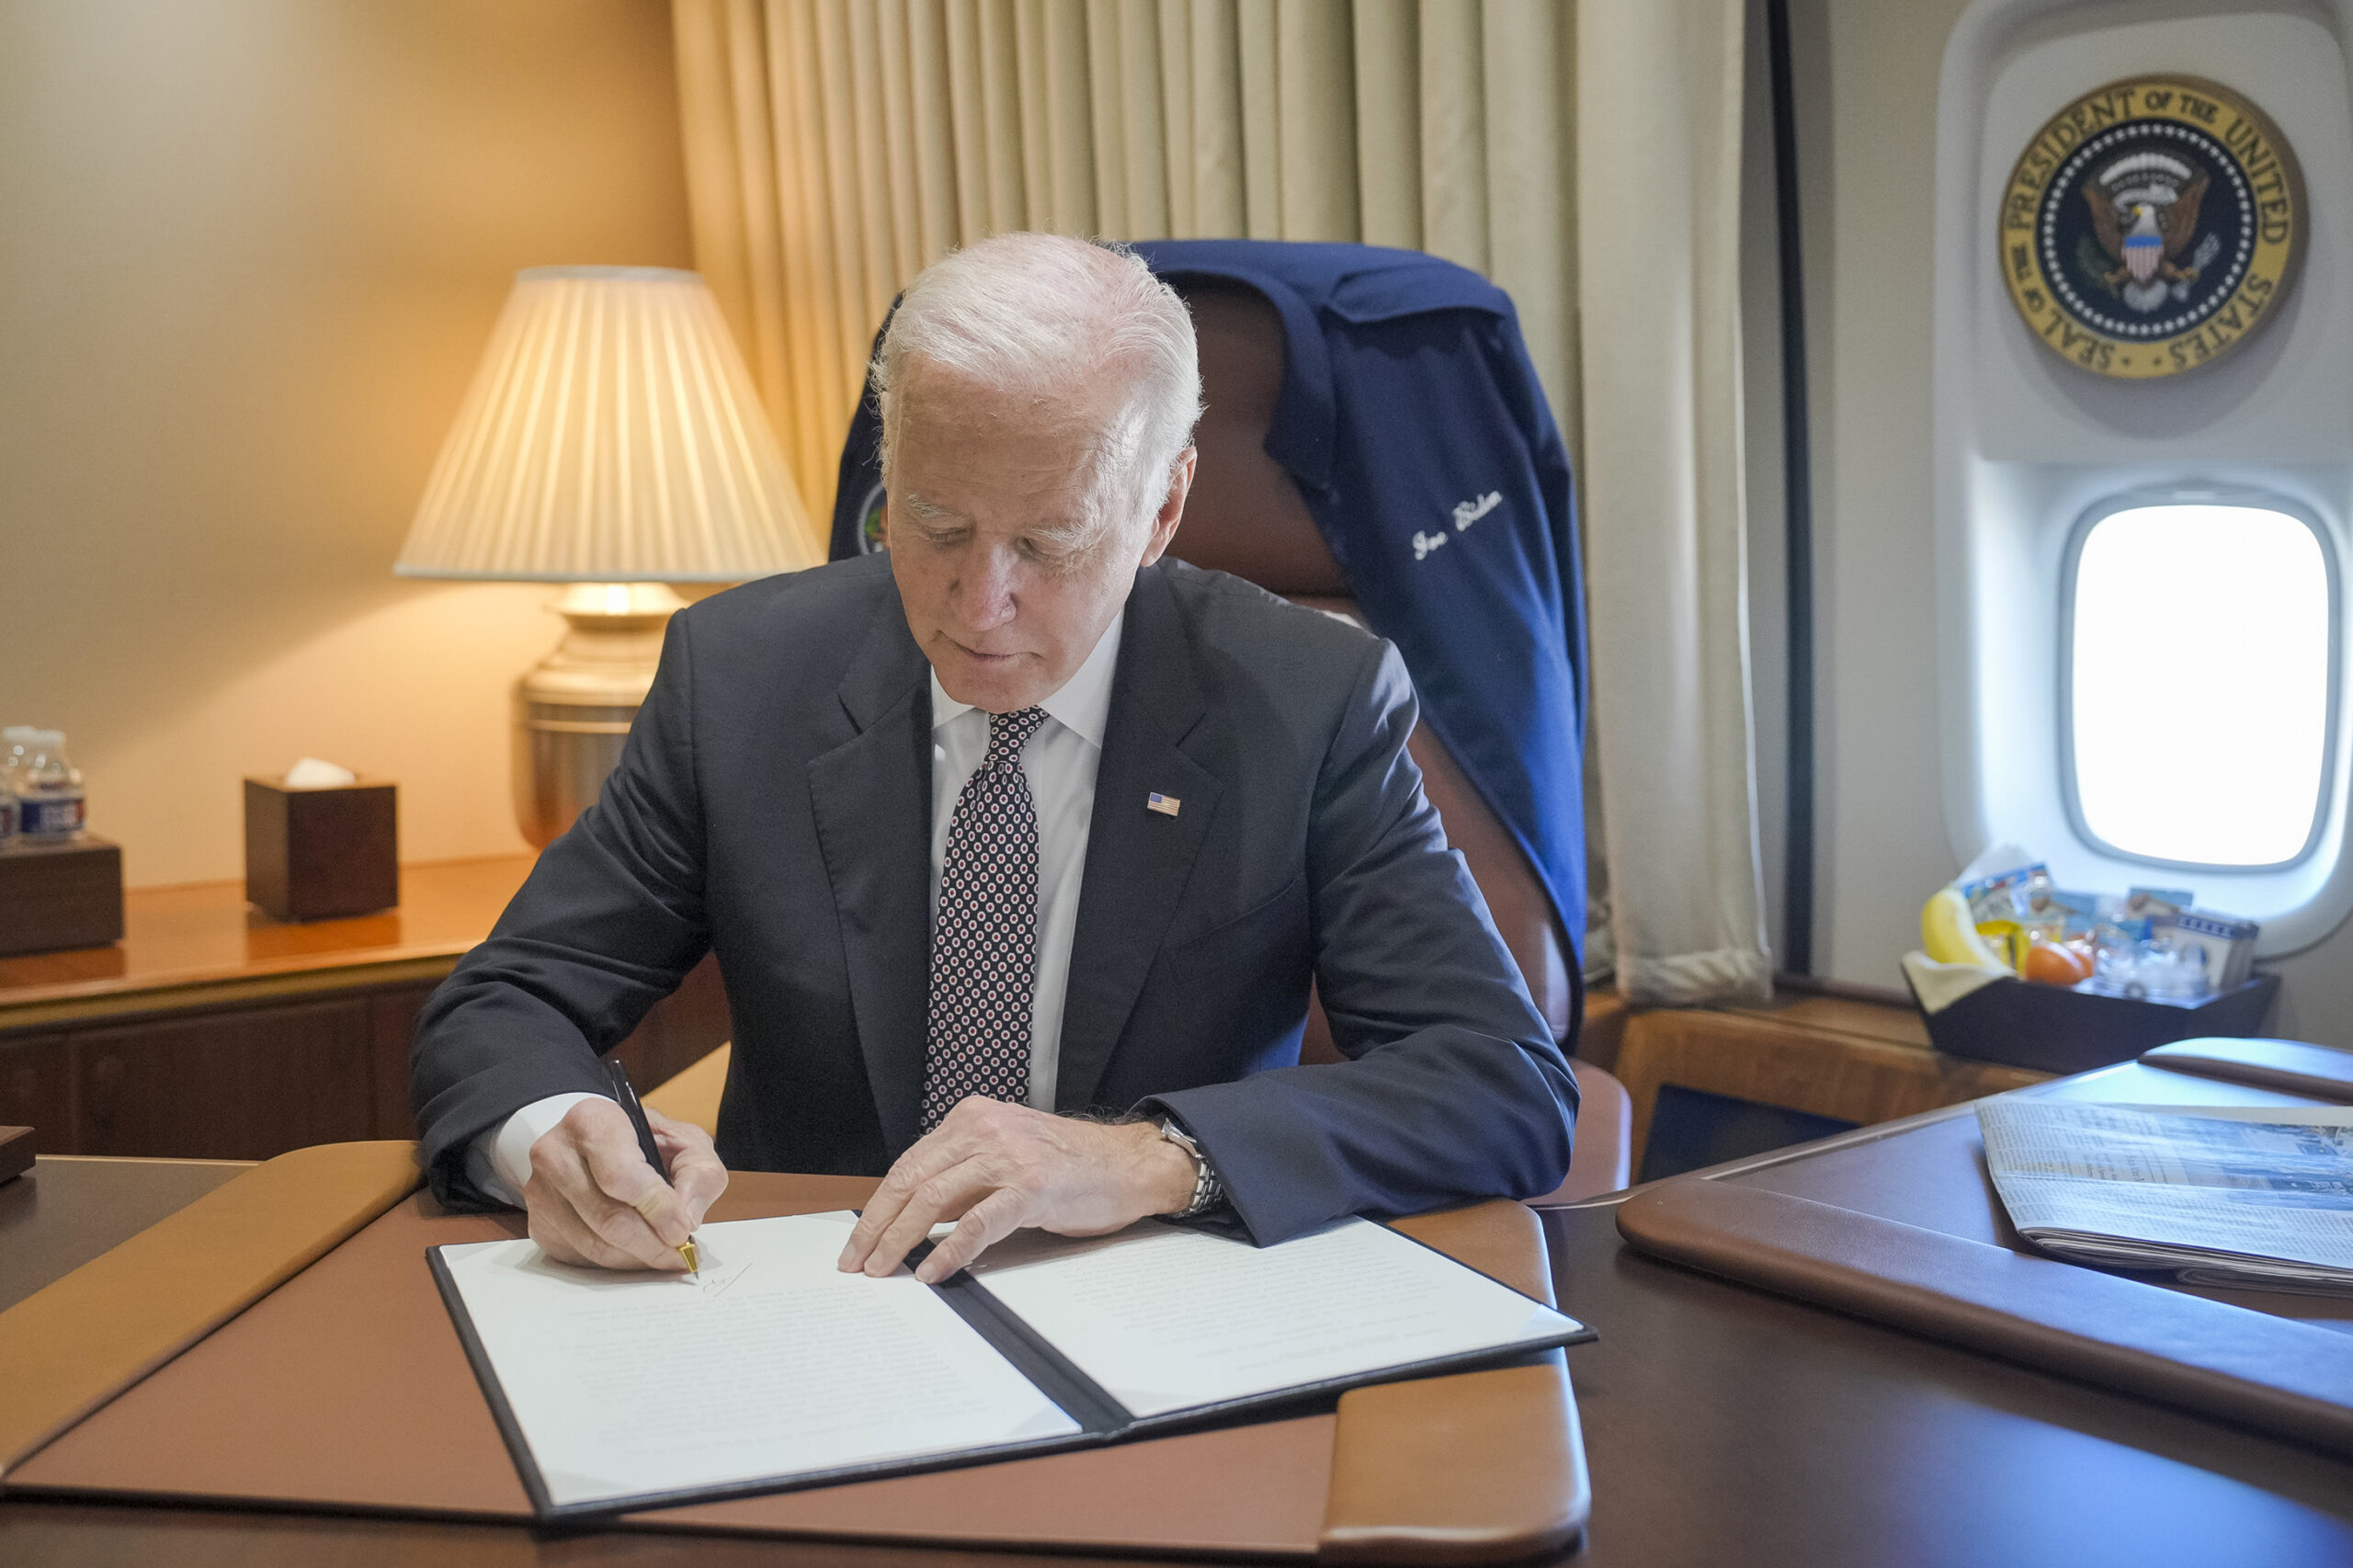
On Oct. 6, President Biden made a historic announcement to “grant a full, complete, and unconditional pardon to all current United States citizens and lawful permanent residents who committed the offense of simple possession of marijuana in violation of the Controlled Substances Act” and “all current United States citizens and lawful permanent residents who have been convicted of the offense of simple possession of marijuana in violation of the Controlled Substances Act.” His executive order also encouraged governors to follow suit for cases regarding state offenses and requested that the secretary of Health and Human Services and the attorney general “expeditiously” review how cannabis is scheduled under federal law.
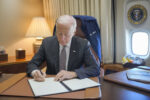
Biden signing his executive order back in October of 2022
The president’s strategic plan attempts to at least partly address some of the adverse impacts of the United States’ war on drugs on certain populations like low-income and Black and Latinx Americans. While an admirable and important effort, certain portions of his executive order will take much longer than others to yield tangible impact. A federal pardoning can take anywhere between two to five years, and the laws and duration of state-level pardoning vary—depending on the state and its governing practices. Additionally, since governors are not required to pardon individuals following the president’s executive order, some convicted persons may never see or be able to seek justice. And the most uncertain timeline relates to the review of cannabis’ classification on the CSA. Rescheduling or descheduling a substance under the CSA can be tedious and grueling, and, as seen with other substances, the process can range from four to ten years. However, the exercise is ongoing, and although results may not be shared in time for the 118th Congress, it is to be expected that the issue will be discussed at length in 2023 and beyond.
When it comes to legislation, there is no question that Majority Leader Chuck Schumer (D-NY) and Sens. Ron Wyden (D-OR) and Cory Booker (D-NJ) will reintroduce the CAOA in 2023. The comprehensive legislation aims to decriminalize cannabis by removing the drug from the CSA and tackles issues related to research, public safety, restorative justice and equity, taxation and regulation, public health and industry practices.
2. States Reform Act.
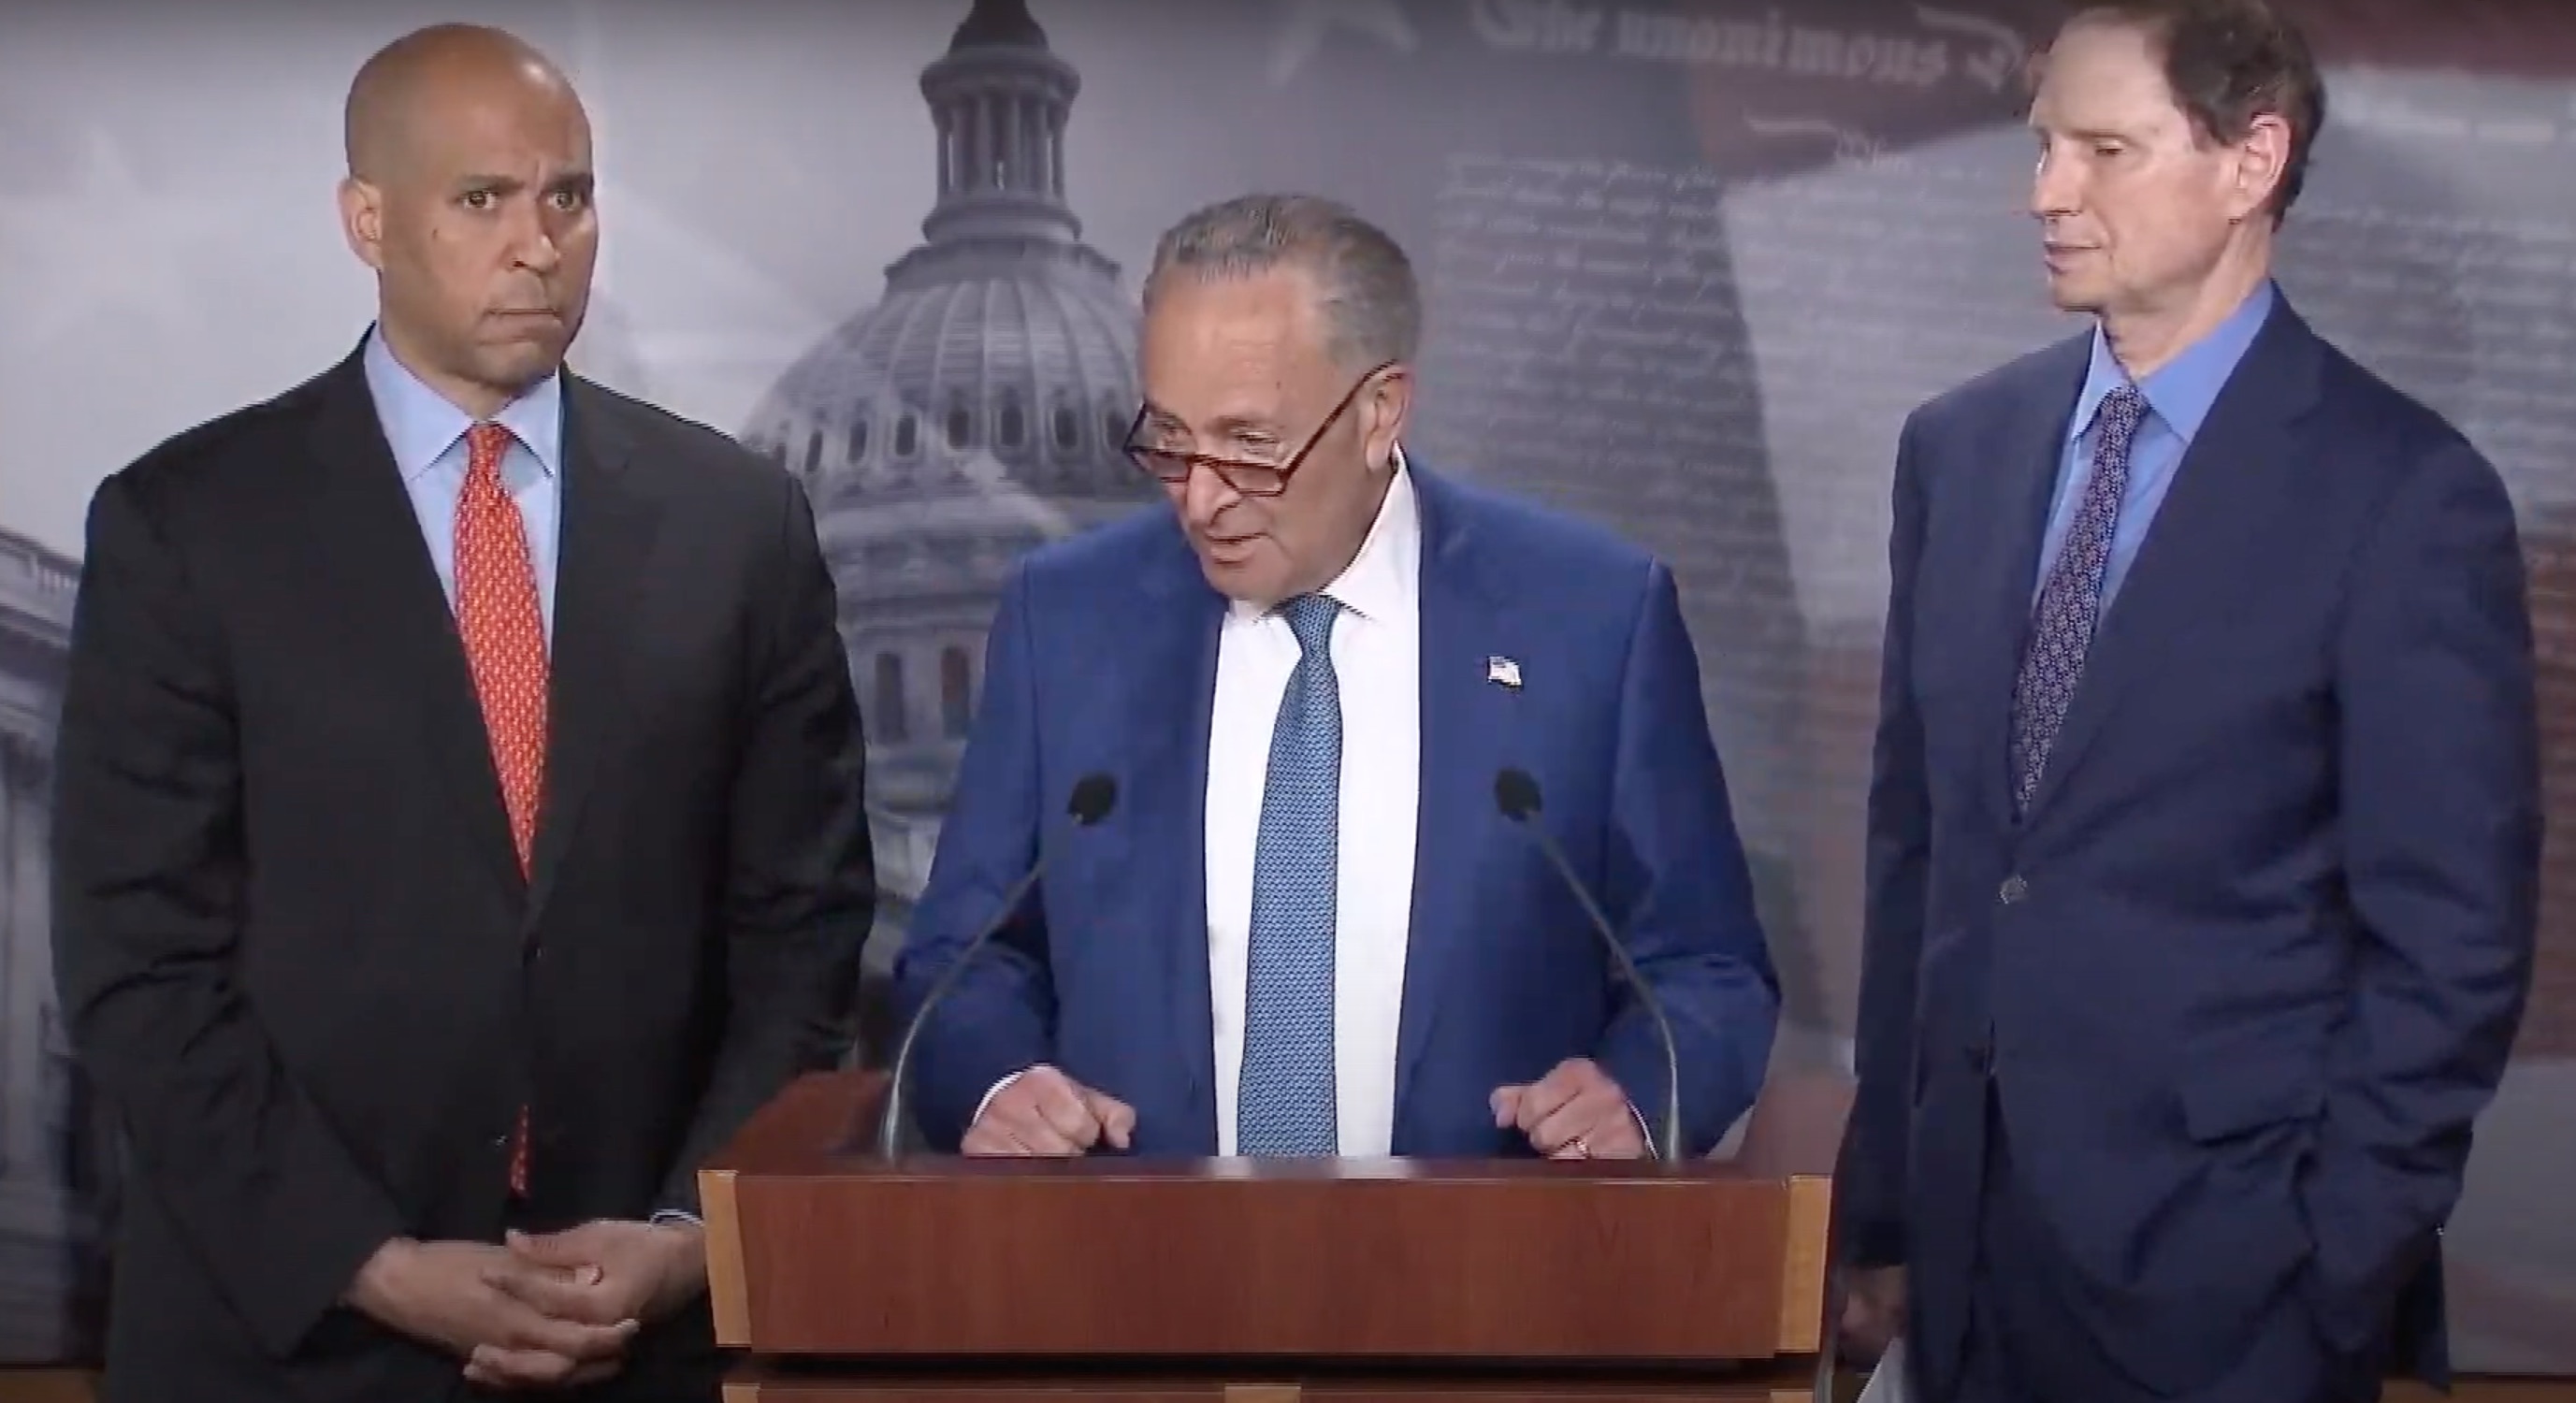
Sen. Schumer unveiling the Cannabis Administration and Opportunity Act
Another piece of legislation we anticipate seeing in the 118th Congress is Rep. Nancy Mace’s (R-SC) States Reform Act. Coming from a state without any cannabis laws, the freshman congresswoman introduced a measure that would federally decriminalize cannabis by fully deferring to state powers over prohibition and commercial regulation and regulate cannabis products like alcohol. In 2022, the bill received positive feedback from the industry and dominated the discussions during the Developments in State Cannabis Laws and Bipartisan Cannabis Reforms congressional hearing. With its bold cannabis sponsor, who will now serve as the House Oversight Subcommittee on Civil Rights and Civil Liberties chair, the States Reform Act will undoubtedly take center stage in 2023.
3. MORE Act.
Sponsored by Rep. Jerry Nadler (D-NY), the MORE Act will also be reintroduced in 2023; however, it remains to be seen how much attention the bill will receive. The MORE Act aims to decriminalize cannabis by removing the drug from the CSA and eliminating criminal penalties for anyone who manufactures, distributes or possesses cannabis. In the 117th Congress, Rep. Nadler served as the chair to the House Judiciary Committee and was able to advance his measure through the chamber with ease. But since the House majority has flipped, and Rep. Jim Jordan (R-OH) is likely to serve as the chair, getting the MORE Act to the floor for a vote may be challenging—especially given Rep. Jordan’s opposition to the cannabis sector.
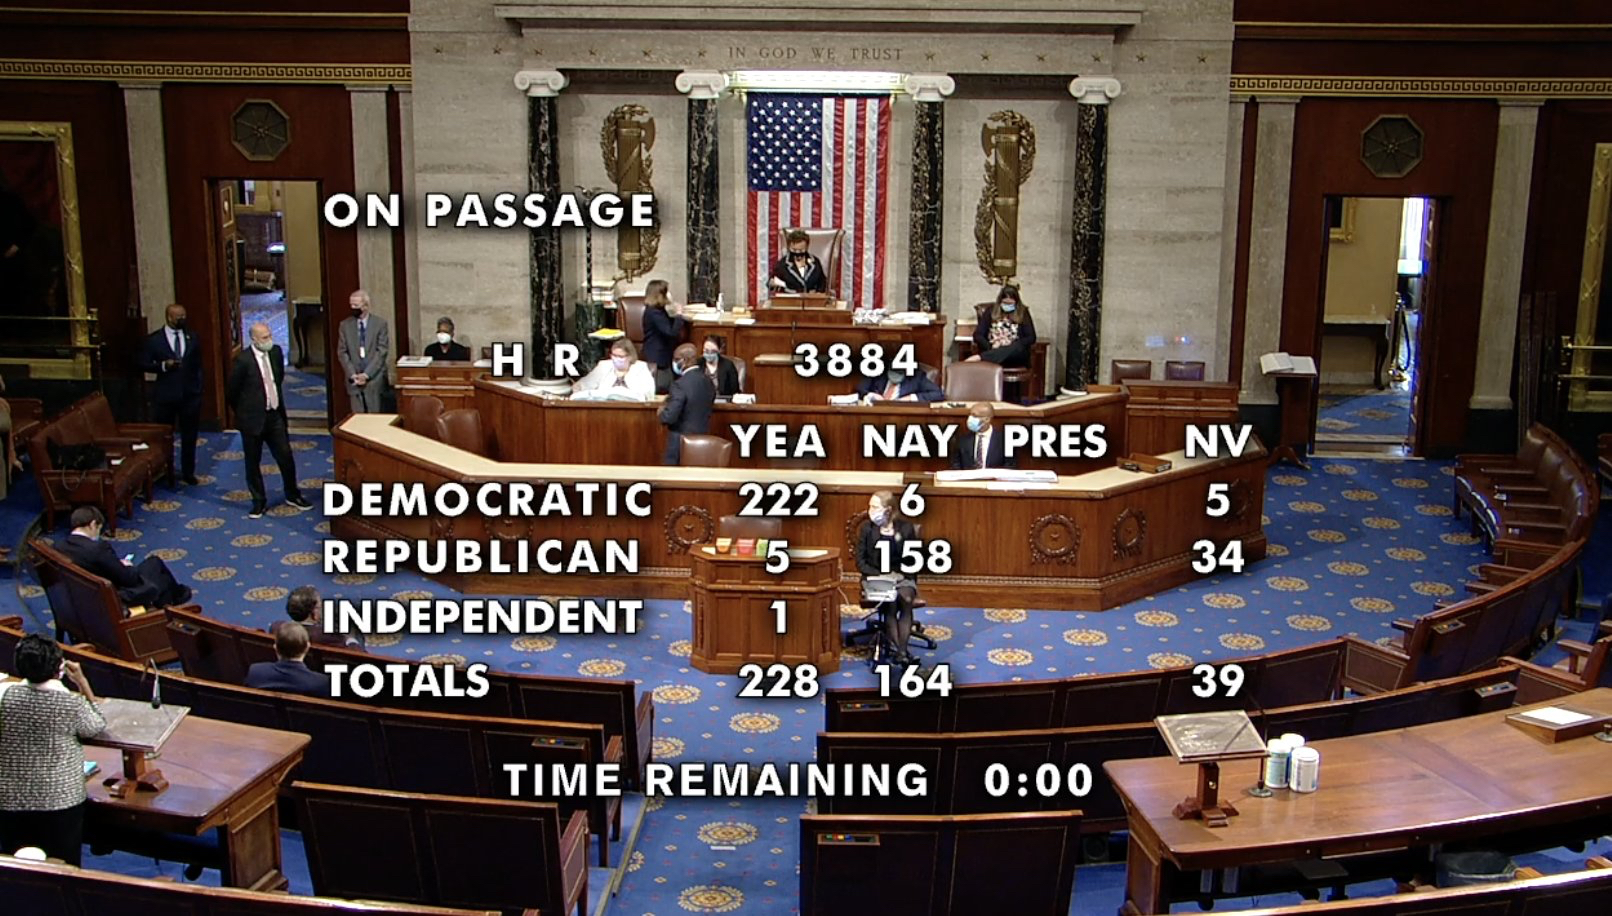
The House passing the MORE Act back in 2020
4. HOPE Act.
The HOPE Act often flies under the radar, but this Republican-sponsored bill made headlines during the 117th Congress. Sponsored by Co-Chair of the Congressional Cannabis Caucus (CCC), Rep. Dave Joyce (OH), the bipartisan legislation aims to help states with expunging cannabis offenses by reducing the financial and administrative burden of such efforts through federal grants. Although it was not considered in the House, the language of the bill was heavily debated by the Senate, particularly toward the end of the year when the chamber was negotiating the final text for end-of-year must-pass packages, like the National Defense Authorization Act (NDAA), the Omnibus and the Continuing Resolution (CR). Alongside the SAFE Banking Act, the HOPE Act was one of the only cannabis bills that had a realistic chance of advancing as part of a larger legislative vehicle, so there is no question that the congressman will reintroduce the measure in the upcoming congressional session.
5. SAFE Banking Act.
And last, but certainly not least, is the most discussed cannabis bill this year: the SAFE Banking Act. The legislation aims to create a safe harbor for financial institutions to provide traditional banking services to cannabis businesses in states that have legalized the drug. It also allows cannabis businesses to access lines of credit, loans and wealth management. It has now passed in the House seven times, with bipartisan support. And although the SAFE Banking Act was debated by the House several times throughout the year, the Senate did not tackle the bill until November. By the time discussions for the bill’s language had taken off, Sen. Booker remained firm that he would only support a cannabis bill if it included criminal justice and social equity reform language. In an attempt to satisfy the senator’s demands, Majority Leader Schumer considered marrying the SAFE Banking Act and the HOPE Act as part of a larger package.
However, and much to the cannabis industry’s detriment, not only was the timeline for those bills a little too late, but Democrats were, unfortunately, unable to fix the money laundering and cash legacy concerns of Sen. Chuck Grassley (R-IA) and other Republicans.
Sen. Cory Booker (D-NJ) Photo: Nick Fisher, Flickr
After attempting to attach the SAFE Banking Act to multiple vehicles, retiring Congressman Ed Perlmutter (D-CO), sponsor of the legislation, and Sen. Schumer were unsuccessful in getting the bill over the finish line. In a final Hail Mary, Sen. Schumer attempted to include the language to the Omnibus, but compounded with the technical assistance report from the Department of Justice (DOJ) and ongoing media flurry, he and the Democratic party yet again came up empty-handed.
The question now is: who will carry the SAFE Banking Act and Rep. Perlmutter’s legacy in 2023? Many will look toward cannabis industry champions like Reps. Joyce, Mace, Earl Blumenauer (D-OR) and Brian Mast (R-FL). However, it would be worth considering other members of the CCC and some of the incoming freshmen, particularly those from a state with legal cannabis laws. It is also entirely possible that Sen. Jeff Merkley (D-OR) finds his own sponsor to carry his companion bill in the House since he has already announced that he looks forward to working on the legislation in the upcoming year. Regardless, it is highly likely that the SAFE Banking Act will be reintroduced in 2023 and considered throughout the year.
6. Other Measures
Other measures that are likely to reappear in 2023 are the Capital Lending and Investment for Marijuana Businesses (CLIMB) Act, Veterans Equal Access Act, the GRAM Act, Common Sense Cannabis Reform for Veterans, Small Businesses and Medical Professionals Act, VA Medicinal Cannabis Research Act and the Homegrown Act. Additionally, the passage of the Medical Marijuana and Cannabidiol Research Expansion Act and the advancement of many of these federal bills have opened the gates for new legislation related to medical and recreational cannabis, research, veterans’ access, financial services, criminal justice reform and social equity, and public health and safety to emerge.
For states with legal cannabis laws, bills related to enhancing the state’s medical or medical and recreational programs, preventing industry oversaturation and price gouging, expanding licensing opportunities, criminal justice reform, youth and advertising protections and impaired driving are likely to be introduced. States where cannabis ballot measures failed will likely see those measures resurface.
The continued growth of legalization across the country is all but inevitable. In the nearer term, the industry will focus on how to remain viable in the face of high taxes and oversupply in 2023. New Congressional leadership could lead to bipartisan cannabis legalization if enough members are willing to rally behind their colleagues who are pushing for cannabis legislation. While the road is long before we will see the full impact from President Biden’s Oct. 6 announcement, the action proves those in power cannot ignore the ever-growing numbers of Americans across party lines and demographics who agree that cannabis use should be legal and regulated.
As the former CEO of Partner Colorado Credit Union (PCCU), Sundie Seefried has been in the credit union space for 39 years. Established in 2015, Safe Harbor Financial is now a leading provider for banking and financial services in the cannabis industry.
Seefried founded Safe Harbor as a cannabis banking program for PCCU, and since then it has withstood scrutiny of 16 separate federal and state exams. Entering its ninth year as a cannabis banking program, they have almost 600 accounts in 20 states and have processed over $14 billion in transactions for the cannabis market. In September, Safe Harbor began trading on Nasdaq under the symbol SHFS. The company has also announced a definitive agreement to acquire Abaca, an industry-leading cannabis financial technology platform.
Seefried has seen it all in the cannabis banking world. We wanted to get her thoughts on some current events, the future of cannabis banking and lending, and what the next few years might hold in store for an industry ready to grow.
Cannabis Industry Journal:Tell us a bit about yourself. What is your background and how did you find yourself in the cannabis industry? How did you get to become president and CEO of SHF?
Sundie Seefried, President & CEO of Safe Harbor Financial
Sundie Seefried: I’ve been in banking in the credit union space since 1983. I became CEO of Partner Colorado Credit Union in 2001 and stayed there for 21 years. Everything I do, I have a very conservative nature just from being in the banking world and doing things methodically and building good foundations that endure long term. In 2014 when FinCen issued guidance, I was supposed to retire, and I had dinner with some old friends that were attorneys who couldn’t get bank accounts for their clients in the cannabis industry. They asked me to help and I looked into it for them. I assumed the regulator would shut me down but he didn’t; he actually encouraged me to move forward and look further into things. As I educated the board, we saw just how unsafe Colorado was and the serious need for the community to figure things out with respect to banking and cannabis. Coming from that credit union perspective, I said I think we can do this, let’s try and I’ll go through the third parties necessary. And that’s how we got into this, just looking to try and help solve Colorado’s problems and get banking access for cannabis companies.
CIJ: Tell me about your company’s mission. What is your financing strategy in cannabis and of the companies you do business with, what do you look for most?
Seefried: Our mission remains the same, and that is to normalize banking in the cannabis industry as much as possible. Because the black market still exists, the issue becomes sorting the legal entities out from the illicit actors in the industry. We know that the illicit market is trying to hide amongst the legal environment, which really makes things difficult for upstanding cannabis businesses. We can normalize banking by making sure we help legitimize the compliant entities and sort out the bad actors. We really only want to work with legitimate players with licenses, who are fulfilling expectations on the regulatory level and have no problems with compliance. We have been able to do that on the depository side.
We have always been a low-cost provider and our clients count on that. As we move into the lending part of the industry, we’re looking to do the same thing. There are lenders who charge one-to-three percent per month, 18 to 36 percent per year. We, on the other hand, are targeting more of an eight to thirteen percent annual rate. More of a conservative approach. Real debt underwriting. No extremely high interest rates. We look for the collateral, we look for well-organized businesses and solid documentation. Those are the businesses we are trying to bring into the fold and offer them normal loans. Cannabis will always have a premium on it simply because it is illegal at the federal level and there are additional hoops we have to jump through. Because of the potential forfeiture and seizure, if there are bad actors, etc., it really behooves any clients coming to us to also place their depositary services with us so we can prove their legitimacy and provide loans to them.
CIJ: Let’s talk about the Canopy Growth news. They announced they are pulling the trigger on acquiring Wana Brands, Acreage Holdings and Jetty Extracts, under the Canopy USA holding company and ahead of federal legalization. On the surface, it looks like they are bypassing a lot of the hurdles American cannabis companies currently face with financial red tape. As a foreign company trading on the NASDAQ dealing with a schedule 1 substance, do you expect Canopy to have a significant, some would say unfair, competitive advantage with their early entry? Or is this perhaps more of a rising tide lifting all boats scenario? What effect will this have on the current market landscape?
Seefried: I find it a very interesting move on their part. Certainly, they have a big advantage in comparison to other companies. The consolidation in the industry is moving so quickly. Other players will keep up with this just as fast as Canopy is moving in. That’s my opinion in terms of what I see in the consolidation area of the market. I think what it really hurts is small businesses. My heart goes out to them. So many of them worked so many years to build excellent small companies with boutique shops, and this whole move will really change that part of the industry.
I see a lot of these small players, non-vertically integrated companies, being impacted in a negative way due to such mass consolidation and the entry of foreign businesses. We need to get more competitive on a global level in order for our companies to grow and thrive. This happened back in 2018, when so many companies started doing those reverse takeovers onto the Canadian Securities Exchange and suddenly, they were putting tens of millions of dollars into the U.S. market. People didn’t see that as a competitive disadvantage for American companies, but now this move by Canopy may really show that we have to look at things more globally.
CIJ: Biden’s announcement regarding the scheduling review for cannabis has a lot of industry folks very hopeful that federal legalization is closer to a reality than before. Do you share their optimism?
Seefried: Closer than before, yes. But how close? I am not convinced it will happen quickly. If they are really going to consider rescheduling or descheduling, everything happens in Washington very incrementally. Eight years and seven attempts at the SAFE Banking legislation and still no movement on that front. Tomorrow, we’re going straight to legalization? I have a hard time swallowing that one. I just don’t see that big of a jump all at once. I think it is interesting coming just before the midterms and votes are really needed now more than ever.
What Biden did was a great start. Especially for those people in prison for possession. The interesting part of it is, we are very serious about people who have used it, but the people who have sold it and are in prison might be in the same situation. Given how the laws worked for so long, just based on the amount of cannabis you had could get you automatically labeled as a dealer, which isn’t the case for a lot of incarcerated folks.
The fact is, the social equity and justice issue, who do you free or who do you not free from prison, is a very difficult issue to get through. I think it is a great step forward and it will help some people who were treated unjustly, but there is still a lot of work to be done.
“I believe we’ll start seeing pressure from the global market on the United States to move things along a little faster in our own country.”As far as rescheduling, if they go from a Schedule I drug to a Schedule II drug, that will do no good, but it certainly is a bone to throw to the industry if you want to look like you are making some progress. Schedule II is still subject to 280E tax code so it will only do so much. If they want to make things more equitable and actually level the playing field, they have to do something about the 280E issue hindering every cannabis business in the country.
As far as full legalization, I am not optimistic because of all the players that need to be involved. Full legalization will require a change to the IRS tax code 280E as well as other tax issues. I think there are too many players: The DOJ, FinCen, the DEA, the FDA, the IRS. All of these agencies will have to agree on full legalization and moving forward in unison. The DEA is trying to fight illicit actors and illicit drugs. FinCen is trying to follow the money to find illicit actors. As long as there is an illicit market it will make their job tough, and on top of all of that, we have politics in play. That is just my take on legalization. It is going to be a much more complex problem than just legalizing the plant and moving on. Rescheduling seems like lower hanging fruit, but they will have to move it higher than a Schedule II.
CIJ: With the midterm elections here, there are a number of legalization measures in a handful of states, along with political control of Congress on the ballot. How do you think a Republican or Democrat controlled Congress will affect cannabis legalization progress?
Seefried: I just finished doing some lobbying in September in DC and spoke to some Senator offices in person, and I heard a lot of interesting topics being discussed. One of the things that keeps popping up is that social equity and justice is a huge issue. If we can’t solve this injustice in our system that has been going on for decades and decades, maybe they’ll hold banking legislation hostage. You can’t correct 50-60 years with one piece of legislation. Everything has to be incremental, unfortunately, so there will be some give and take there. I think that was a primary focus, especially with the Democrats and I do think it is a worthy cause.
On the Republican side, economically improving our competitive advantage as a country. They are starting to see the jobs being created and the tax revenue coming in and the growth of the industry. They will have to make that decision at some point in time whether they are going to leave the American cannabis industry behind or allow them to compete on a global level. I really think everything will move slowly and continue as it has happened in the past.
I believe we’ll start seeing pressure from the global market on the United States to move things along a little faster in our own country.
CIJ: As we inch closer to 2023, what do you expect the next year to offer for the cannabis financing market?
Seefried: I would say, with or without legislation, they’re finding greater access to banking. And the reason they are getting better access to banking is because none of us have been prosecuted for simply engaging in cannabis banking. I think we have set a precedent over the past eight years, not only us but other service providers in the industry and that we are not being prosecuted.
I see more financial institutions entering the market slowly. The second reason access to capital and banking will increase is because every financial institution in the country wants that lending relationship. In order to get there, they want to start with the depository relationship, and they don’t want smaller players presently doing it and getting all of those relationships before they enter the market. I think the competitive nature of the financial industry to land that lending relationship is going to force them into the game sooner than later.
Despite the US making cannabis regulations challenging to navigate, the industry is snowballing toward profitability. New Jersey legalized adult use cannabis on April 21 this year. One month earlier, The Garden State began accepting applications for Class 5: Retailers, Dispensing and Delivery.
Although New Jersey isn’t shy about its licensing requirements and standards, many people want to know how retailers can stay in the game for the long run. So, let’s talk about risk management considerations New Jersey retailers need to know.
Top Risks Cannabis Retailers Face in New Jersey
Regardless of what kind of retailer you operate —medical or adult use — it’s critical to know what you’re up against. The following are the most common risks we’ve watched cannabis retailers face daily in New Jersey, making a customized risk management strategy necessary.
Theft
Like other retailers, New Jersey cannabis retailers are vulnerable to theft. Unfortunately, theft can come from various angles, such as in-store, in-transit and insider crime. Besides cannabis retailers typically having a well-stocked inventory, it’s not uncommon for them to have more cash on hand than most other businesses.
Although the SAFE Banking Act could positively impact the cannabis industry, it’s in a notorious stall yet again. Briefly, the SAFE Banking Act would no longer allow financial institutions, such as banks and credit card companies, to refuse to do business with cannabis companies. However, cannabis retailers must operate in a cash-only environment, for now, forcing them to make bank runs multiple times a day. We probably don’t have to explain how enticing a significant inventory and fat bank bags look to criminals.
Cybersecurity
Since the onset of the global health crisis, the cyber liability landscape has nearly spun into a death spiral. In other words, cybercriminals sat on the edge of their seats during the pandemic, waiting to pounce on anything that looked slightly vulnerable. Remote workers, small businesses, and emerging industries were hard-hit.
It’s no surprise that New Jersey cannabis retailers face many cybersecurity risks through their point of sale (POS) systems. Additionally, retailers often gather and store personal information, such as email addresses, credit card numbers, shipping addresses, etc. Hackers and cybercriminals gravitate to this vital data rapidly.
Property Damage
In addition to the risk of theft, as mentioned above, cannabis retailers must protect their property from losses. Without adequate protection, damage to equipment or buildings could add up to high out-of-pocket costs. Consider the damage a weekend office fire or late-night vandalism would cause. If property damage occurs, retailers must figure out how to sustain business operations while recovering from the loss simultaneously. As a result, New Jersey retailers must protect their property and maintain business continuity.
How to Customize a Risk Management Strategy
Watch or listen to any news reports and there’s a decent chance that you’ll feel some slight sense of doom and gloom. And sure, a lot is going wrong in our world; however, that doesn’t need to impact how you perceive your businesses. Instead of casting a massive net over every possible risk that you can imagine, we recommend trying the following 5-step approach. Here’s the gist:
Identify: Pinpoint high-level risks that are specific to the cannabis industry. Then, let the process trickle down to focus on company-specific exposures.
Analyze: Determine how badly a particular risk could harm your retail company. How much will this hurt should the “what-ifs” play out?
Evaluate: Categorize risks according to how risk tolerant your company is. Will you avoid, transfer, mitigate or accept the risk?
Track: Use your history or the stats from a similar retailer to map out how you’ve handled the risk over time. Older retailers have an advantage over younger retailers, of course, but you can still get a feel for your risk management style.
Treat: Make good on your evaluation promises by avoiding, transferring, mitigating, or accepting the various risks you identified.
Recommended Insurance for New Jersey Retailers
Sales totals in the first month of New Jersey’s adult use market
The New Jersey Cannabis Regulatory Commission issued detailed requirements for new cannabis businesses. That said, part of the application requirements considered is the plan for companies to obtain liability insurance. Many new retailers opted for a “letter of commitment” as opposed to a certificate of insurance (COI), stating their plans for obtaining the following coverages:
Commercial general liability: Protects cannabis companies against basic business risks.
Product liability: Protects against claims alleging your product or service caused injury or damage.
Property: Reimburses cannabis companies for direct property losses.
Workers’ compensation: Covers employees if they are injured on the job and can no longer work.
In addition to the required insurance coverages, we recommend New Jersey retailers customize their risk management package with these policies:
Crime: Protects your cannabis company against specific money theft crimes.
Cyber: Protects your cannabis company against damages from specific electronic activities.
Directors & officers: Protects corporate directors’ and officers’ personal assets if they are sued.
Employment practices liability: Protects cannabis companies against employment-related lawsuits.
Professional liability: Protects cannabis companies against lawsuits of inferior work or service.
With more states in the US entering the marketplace soon, New Jersey is doing its fair share of the heavy lifting by spearheading the onboarding process. Remember, doing your due diligence at the start pays off in the long run — New Jersey retailers are proving that. Consider teaming with a commercial insurance broker calibrated to the cannabis industry, so you get the most out of your broker, marketplace and the cannabis industry as a whole.
Like this article and want to see more? Subscribe to our free newsletter here The cannabis industry could receive a significant boost if the recently introduced Capital Lending and Investment for Marijuana Businesses (CLIMB) Act passes Congress. The bipartisan bill was introduced by Rep. Troy A. Carter, Sr., a Democrat from Louisiana, and Rep. Guy Reschenthaler, a Republican from Pennsylvania. It is intended to boost the cannabis industry by creating greater access to capital, banking insurance and other business services. Unlike the SAFE Banking Act (which specifically addresses banking services for the cannabis industry), the CLIMB Act was introduced “to permit access to community development, small business, minority development and any other public or private financial capital sources for investment in and financing or cannabis-related legitimate businesses.”
Rep. Troy A. Carter, Sr.
Currently, the cannabis industry faces a serious dilemma with regard to accessing not only traditional banking services, but also essential capital and financing sources. The latest member of the cannabis bill alphabet soup attempts to remedy this by addressing two key issues.
First, the CLIMB Act would permit access to key “business assistance” programs from various financial institutions by prohibiting any federal agency from bringing any civil, criminal, regulatory or administrative actions against a business or a person simply because they provide “business assistance” to a cannabis state-legal company. The CLIMB Act defines “business assistance” broadly to include, among other things, management consulting work, accounting, real estate services, insurance or surety products, advertising, IT and other communication services, debt or equity capital services, banking or credit card services and other financial services.
This provision of the CLIMB Act would immediately create more access to traditional insurance, lending and credit. This broad protection would not only apply to private entities providing “business assistance,” but arguably means that the U.S. Small Business Administration (SBA) could not be penalized by Congress or another government agency for providing loans to state-legal cannabis companies. Moreover, currently the cannabis industry does not have access to use credit cards, as major credit card companies refuse to permit such transactions. The CLIMB Act could pave the way for major credit card providers to begin permitting cannabis transactions. Permitting the use of major credit cards like American Express, Mastercard and Visa could result in an increase in sales for cannabis retailers.
The second, and possibly the most important, aspect of the CLIMB Act is that it would amend the Securities and Exchange Act of 1934 to create a “safe harbor” for national securities exchanges like Nasdaq and the New York Stock Exchange (NYSE) to list cannabis companies and would permit the trading of these cannabis businesses stock. Currently, plant-touching cannabis companies with operations in the U.S. can only be listed on a Canadian-based exchange and can also only be traded in the U.S. via the over-the-counter (OTC) markets. Trading securities on the OTC markets does not provide the same level of security as securities traded on a national exchange like Nasdaq or NYSE. Specifically, the CLIMB Act delineates that the federal illegality of cannabis is not a bar to listing or trading of securities for legitimate cannabis-related businesses.
Rep. Guy Reschenthaler
This provision of the CLIMB Act has two immediate effects. First, the CLIMB Act would allow for U.S. cannabis companies currently listed in Canada to list on the Nasdaq or NYSE. Second, this provision would allow more traditional, “blue-chip” industry companies currently listed on Nasdaq or the NYSE who haven’t been able to operate within the cannabis industry as a plant-touching entity, to enter the cannabis industry as an active participant.
In announcing the CLIMB Act, Representative Reschenthaler stated that “American cannabis companies are currently restricted from receiving traditional lending and financing, making it difficult to compete with larger, global competitors. The CLIMB Act will eliminate these barriers to entry, and provide state-legal American cannabis companies, including small, minority, and veteran-owned businesses, with access to the financial tools necessary for success.”
It is important to note that the CLIMB Act, like the SAFE Banking Act, only represents one small, but important step toward cannabis reforms. Neither proposal would legalize, de-schedule or reschedule cannabis. Rather, the CLIMB Act addresses very real-world, operational issues facing the cannabis industry. With that in mind, the CLIMB Act would certainly provide much needed clarity for issues facing all cannabis companies.
Passage of the CLIMB Act is not a forgone conclusion, but rather is quite uncertain. Other pieces of cannabis-related legislation, like the SAFE Banking Act, have passed the House of Representatives multiple times without the U.S. Senate taking any action. Moreover, the CLIMB Act was introduced with only two legislative supporters.
By Tamara L. Kolb, Amy Bean, Caitlin Strelioff No Comments
As the legal cannabis market expands, banks and nonbank financial institutions (NBFIs) across the United States continue to explore how to safely provide banking and other financial services to cannabis-related businesses (CRBs) and other CRB ecosystem players. At the same time, these organizations are taking into account changes they might need to consider relative to their Bank Secrecy Act ( BSA), anti-money laundering (AML) and related compliance programs.
Regulatory conundrum
The Controlled Substances Act (CSA) identifies the cannabis plant and all its derivatives as a Schedule 1 controlled substance. Schedule 1 controlled substances have a “high abuse potential with no accepted medical use,” and they cannot be “prescribed, dispensed, or administered.” Because cannabis remains classified as a Schedule 1 controlled substance, the CSA “imposes strict controls on possession, manufacturing, distribution, and dispensing” of cannabis.
Under the Money Laundering Control Act of 1986 (MLCA) and the BSA as amended, covered banks and NBFIs are prohibited from providing financial services to businesses that are engaged in illicit activities. Because federal law prohibits the distribution and sale of cannabis, financial transactions involving CRBs are therefore deemed to be transactions that involve funds derived from illegal activities.
As of Feb. 3, 2022, 18 states, two territories, and the District of Columbia have enacted legislation to regulate cannabis for adult use. Thirty-seven states, the District of Columbia and four territories have approved comprehensive, publicly available medical and cannabis programs. Eleven states allow for the use of low-THC, high-CBD substances for medical reasons in limited situations or as a legal defense.
The growing divide between federal prohibition and state legalization of the cannabis industry creates a precarious position for federally regulated banks and NBFIs with the main concern involving exposure to legal, operational and regulatory risk. The situation begs the question: How might the federal government and regulators pursue and prosecute players in the legal cannabis industry?
The current economic trajectory predicts that retail sales of legal cannabis products in the U.S. will surpass an estimated $41.5 billion annually by 2025, and many banks and NBFIs are eagerly awaiting the federal green light to do business with CRBs without fear of prosecution or legal ramifications.
From 2018 forward, Congress has made several attempts to pass legislation that would protect CRBs when cultivating, distributing, marketing, and selling cannabis products in their state-legalized form. These efforts to declassify cannabis-related activity as a specified unlawful activity have thus far been unsuccessful.
The House passing the MORE Act back in 2020
Passage of the Secure and Fair Enforcement Banking Act of 2021 (SAFE Banking Act) and the Marijuana Opportunity Reinvestment and Expungement Act of 2021 (MORE Act) would enable banks and NBFIs to provide financial services to CRBs. The SAFE Banking Act would provide a safe harbor for banks and NBFIs that provide financial services to CRBs. The MORE Act would deschedule cannabis from the CSA entirely.
Questions to ask
Banks and NBFIs interested in providing financial services to CRBs should ask these questions:
Do we adequately understand our risk, and what are the implications for our organization? How should we augment our risk assessment process and our controls?
To what extent are we willing to accept the risk of banking CRBs? Do we have the ability to identify CRB customers, and if so, do we have any?
How should we advise the board of directors about setting risk appetite?
What customer due diligence (CDD) and enhanced due diligence (EDD) will we need to safely continue with existing customers and onboard new ones?
How will we monitor for unusual and suspicious activity? What will be the alerting and judgmental criteria?
How will our resource needs change so that we stay abreast of new processes and controls?
Risk appetite considerations
In order to determine whether to accept or prohibit CRBs, banks and NBFIs should identify the level of acceptable risk they are willing to take on. Several key components need to be considered, such as:
The board of directors’ stance on legal cannabis, given that good governance recommends and regulators expect that the board sets risk appetite
Cannabis laws in states within the customer footprint and the impact on customers’ communities
Risk profile, customer base, geographic location, products, and services
Relationship with regulators and any recent deficiencies or weaknesses in the BSA and associated compliance programs
Ability to implement appropriate controls and staffing
Developing a strategic road map
If the decision is made to bank CRBs, banks and NBFIs should perform an assessment of compliance maturity for existing BSA/AML program processes and controls to identify potential gaps and develop a strategic road map that helps the organization achieve its vision for future state compliance and sustainable operations.
A well-developed and well-articulated strategic road map visualizes what actions or key outcomes are needed to help organizations achieve their long-term goals. When creating the road map, banks and NBFIs need to demonstrate a keen understanding of their desired strategy, outcomes, markets, and products for onboarding and banking CRB customers. Specifically, banks and NBFIs need to define and explain how desired outcomes and business strategies create risk and exposure.
In addition to a road map, banks and NBFIs should develop and document a detailed risk-based approach that is aligned to the organization’s risk tolerance to determine necessary compliance steps when banking CRB customers.
Specifically, the following activities should be considered when developing a CRB banking program that meets regulatory expectations:
Identifying BSA/AML control gaps related to CRB risk identification and mitigation and formulating a plan to address them
Updating a board-approved policy framework
Updating detailed operating policies and procedures
Planning for capacity, developing job descriptions, and onboarding new personnel
Training for all three lines of defense, senior management, and the board
Developing and documenting a phased or full approach to acceptance of CRB customers
Developing and documenting a CRB program oversight policy
This framework is intended to help banks and NBFIs differentiate types of CRBs and their corresponding risks, and it separates CRBs into three tiers and details risks for each tier. The following exhibit summarizes the approach:
Risk framework by tier
Level
Risk
Tier 1
Direct
Tier 2
Indirect with substantial revenue from Tier 1
Tier 3
Indirect with incidental revenue from Tier 1
Source: CRB Monitor
Even the most conservative of risk appetites equivalent to outright prohibition is not devoid of significant risk considerations. Residual risk frequently encompasses a large number of indirect connections in the total CRB ecosystem. Common examples are printers, lawyers, accountants, landlords, and even utilities and taxing authorities, and all of these are subject to regulatory scrutiny and, importantly, visibility to law enforcement. Also, policies to prohibit or restrict will be audited and examined for compliance, and exceptions will require explanations.
This panorama necessitates expertise and prudence in identifying and evaluating risks within the many layers of CRBs. For example, consider a bank or NBFI that banks a CRB’s employee or vendor. If a bank fails to properly implement controls that would allow it to identify and mitigate risk associated with banking CRBs, it will be susceptible to severe violations of the BSA, including civil money penalties, criminal penalties, and regulatory enforcement actions.
Implementing necessary precautions
A well-developed road map should consider and implement the following activities:
Understanding the most current state and federal cannabis laws and regulations to ensure the bank or NBFI’s compliance
Understanding the local, state, or tribal program to ensure CRB customers are compliant with the program
Implementing a CRB risk assessment
Implementing executive approval practices for direct CRBs
Developing adequate risk ratings (possibly through a risk-based, tiered approach) and corresponding monitoring for CRB customers that includes:
Integrating various customer onboarding and AML solutions at both onboarding and periodic levels
Scheduling regular reviews to include recurring enhanced due diligence, site visits, and transaction monitoring
Monitoring for suspicious activity, including red flags, via open sources for adverse information about the CRB customers and related parties such as beneficial owners
Performing adequate CDD and EDD that will validate that the CRB-offered products, services, and programs are compliant with most current state laws and regulations by:
Collecting appropriate documentation as evidence of compliance, perhaps including a comprehensive onboarding questionnaire, beneficial ownership information, and contracts for the growing, harvesting, transporting and processing of the product
Reviewing applications and supporting documentation used to obtain a legal cannabis state license
Understanding the normal and expected activity of the organization’s CRB customers and their product usage
Developing adequate training programs and governance and oversight programs to address this customer type by:
Updating existing policies and procedures to review inherent risk presented by banking CRB customers
Updating annual training for employees
Auditing initial program design and periodic operational effectiveness
Moving forward cautiously
The ins, outs, and unknowns of cannabis banking are complex, and they require banks and NBFIs to be extremely vigilant with current policy and aware of new developments. Overall, the idea of creating a cannabis program might seem like a daunting task, but with appropriate guidance and care, organizations can provide services in compliance with laws and regulations.
Crowe disclaimer: Qualified organizations only. Independence and regulatory restrictions may apply. Some firm services may not be available to all clients. Given the continued evolution and inconsistency of various state and federal cannabis-related laws, any company should seek competent legal advice relating to its involvement in the cannabis industry, including when considering a potential public offering as a cannabis-related company.
Federal regulations have made compliant credit processing in the cannabis industry difficult to achieve. As a result, most cannabis retailers operate a cash-only model, limiting their ability to upsell customers and placing a burden on customers who might rather use credit. While some dispensaries offer debit, credit or cashless ATM transactions, regulators and traditional payment processors have been cracking down on these offerings as they are often non-compliant with regulations and policies.
Two companies, KindTap Technologies and Aeropay, are addressing the cannabis industry’s payment processing challenges with innovative digital solutions geared towards retailers and consumers.
We interviewed both Cathy Corby Iannuzzelli, president at KindTap Technologies and Daniel Muller, CEO at Aeropay. Cathy co-founded KindTap in 2019 after a career in the banking and payments industries where she launched multiple financial and credit products. Daniel founded AeroPay in 2017 after a career in digital product innovation, most recently at GPShopper (acquired by Financial), where he oversaw the design and development of over 300 web and mobile applications for large scale Fortune 500 companies.
Green: What is the biggest challenge your customers are facing?
Cathy Corby Iannuzzelli, co-founder and president at KindTap Technologies
Iannuzzelli: Our customers include both cannabis retailers and their end consumers. As long as cannabis is illegal at the federal level, normal payment solutions such as debit and credit cards cannot be accepted for cannabis purchases. This has resulted in heavy cash-based sales and unstable, transient work-around ATM payment solutions that can be ripped out with little notice, disrupting the entire business. The lack of a mature payment network to support retail payments for cannabis purchases is a huge challenge for all stakeholders. Cannabis retailers bear the high cost and safety issues of operating a heavily cash-based retail business. Consumers encounter several friction points that require them to change their behavior when purchasing cannabis relative to how they purchase everything else.
Muller: Our cannabis business customers have faced a constantly changing and, frankly, exhausting financial services environment. From the need to move and manage large amounts of cash, to card workarounds, added to the disappointment from legislation around the SAFE Banking Act, these inconsistencies have acted as a roadblock to their potential growth and profitability. Aeropay is in the position to be a stable, long-term, reliable payments partner ready to help them scale their businesses. We believe these opportunities are limitless.
Green: What geographies have got your attention and why?
Daniel Muller, CEO and founder of Aeropay
Iannuzzelli: KindTap’s focus is on the U.S. market where federal policy has created the need for alternatives to traditional payment networks. KindTap is available in every U.S. state where cannabis is legally sold. In terms of our distribution channels, KindTap’s digital payment solution was brought to market during the COVID-19 pandemic when curbside pick-up and delivery became critically important. These channels are where the exchange of cash at pick-up posed the greatest security risk to employees and customers. Our early integrations were with e-commerce platforms focused on delivery and pick-up orders, and our integration partners have strong customer bases in California and the northeast. So, while KindTap can provide its “Pay Later” lines of credit and “Pay Now” bank account solutions anywhere, we have heavier penetration in those regions.
Muller: California, for its established tech culture and how it plays into the cannabis industry – your product simply has to live up to their tech standards to be heard. Also, Chicago, our headquarters, with its newly emerged commitment to financing the cannabis industry and bringing with it a more traditional business approach. In Chicago, you have to have elevated standards of professional practices in any industry you enter. And of course, we love to watch emerging markets like New York and Florida as they head towards adult-use and what shape cannabis and payments will take.
Green: What are the broader industry trends you are following?
Iannuzzelli: We continue to see a strong transition from cash and ATM transactions over to digital payments. Since KindTap has a fully-integrated payment “button” on e-commerce checkout screens, the adoption rate of end consumers to that one-click experience is quite strong. We are also seeing trends of more “express lines” in the retail environment – for those KindTap users who paid online/ahead – and faster/safer delivery experiences to people’s homes since there is no longer the need to collect any payment upon delivery. We are firm believers in the delivery/digital payments combination and a strong increase of that trend as more states allow for delivery.
Muller: The cannabis industry is starting to normalize payments and mirror traditional online and brick-and-mortar. With bank-to-bank (ACH) payments, cannabis businesses can now offer modern customer shopping experiences including pre-payment for delivery orders without the need for a cash exchange at the door, offering the option to buy online pickup in-store and contactless in-store QR scan-to-pay customer experiences. With these familiar and customer-driven options now available, we are seeing widespread adoption, as well as meaningful increases in spend and returning customers.
Green: Thank you both. That concludes the interview!
About KindTap: KindTap Technologies, LLC operates a financial technology platform that offers credit and loyalty-enabled payment solutions for highly-regulated industries typically driven by cash and ATM-based transactions. KindTap offers payment processing and related consumer applications for e-commerce and brick-and-mortar retailers. Founded in 2019, the company is backed by KreditForce LLC plus several strategic investors, with debt capital provided by U.S.-based institutions. Learn more at kindtaptech.com.
About AeroPay: AeroPay is a financial technology company reimagining the way money is moved in exchange for goods and services. Frustrated with the current, antiquated payments landscape, we believe there is a better way to pay and a better way to get paid. AeroPay set out to build a payments platform that works for all- businesses, consumers, and their communities. Learn more at aeropay.com.
Practicing Law Institute Press’s Legal Guide to the Business of Marijuana: Cannabis, Hemp and CBD Regulation is a one-of-a-kind deep dive into the many regulations governing the industry. Aimed at attorneys representing clients in this space, the treatise offers guidance on a range of interrelated topics including state regulation of medical and non-medical cannabis; federal law, enforcement and preemption and their implications for employment, taxes and banking; and the various aspects of establishing and managing a cannabis enterprise, from growth to licensing, transport and distribution. We spoke with co-authors James T. O’Reilly, professor of Public Health Policy at the College of Medicine of the University of Cincinnati and author of leading references on food and drug law, and Edgar J. Asebey, a founding partner of Keller Asebey Life Science Law and a life sciences attorney with over twenty years of experience, about the intersection of the cannabis business and the law.
Q: From the legal industry’s perspective, how has this area of the law evolved over the past few years – and what would you advise clients in cannabis to look for when engaging legal assistance for their businesses?
James T. O’Reilly & Edgar J. Asebey: Over the past few years, we have seen a growing acceptance of the idea that lawfully serving the needs of cannabis consumers is a commendable business initiative. This evolution in thinking – tied to the myriad business opportunities cannabis presents – has given large, mainstream corporate law firms the incentive to grow practices and develop specialists in this area, which is a very positive development.
But it is not enough for lawyers to know their way around M&A and the capital markets; they must also have experience with federal regulatory bodies. As regulations continue to evolve, it is essential for practitioners to be familiar with the Food, Drug and Cosmetics Act as well as the Federal Trade Commission Act. The framework for regulating cannabis products already exists, as can be seen in the Warning Letters sent to hemp and CBD companies by both the Federal Trade Commission and Food and Drug Administration (as well as, most recently, the FDA and CDC’s warning about delta-8 THC). If a client places their hemp or CBD product into the stream of commerce, that product will be subject to FDA, FTC and relevant state laws. We strongly recommend seeking out advisors who truly understand these regulations and how they align with the regulatory agencies’ procedures and agendas.
Q: What are the most urgent legal and regulatory topics the industry is watching these days?
O’Reilly & Asebey: Our treatise follows and analyzes the most pressing legal issues facing those in the cannabis and hemp space. In our most recent edition, we add discussion of the Final Rule for the establishment of a domestic hemp production program. We think this is a significant development in that it attempted to address some of the industry’s criticism of some provisions found in the Interim Final Rule, particularly around issues of sampling and testing for THC content. The Final Rule clarified issues around THC percentage testing methodologies, but disappointed many in the industry by leaving in place the low 0.3% dry weight threshold for an acceptable hemp THC level. On the other hand, The Final Rule raises the threshold for a negligent violation from 0.5% to 1.0% total THC and limits the number of violations a grower can receive in one year to one, easing potential penalties for violations.
Of course, the regulation of CBD products is on the minds of many in the industry. Key questions remain about whether cannabinoids such as delta-8 THC can be lawfully sold. Since the FDA has provided no clear guidance with regard to the sale and use of CBD and other hemp-derived cannabinoid-containing products, well-meaning businesses find themselves operating in a regulatory gray area. While some states have raced to place delta-8 THC on their controlled substances lists or otherwise regulate it, at the federal level it remains unclear. Our book provides a legal argument showing that current regulations support the lawful production and sale of delta-8 THC. To date, this and other legal arguments have not been tested in the courts and, without FDA guidance, the delta-8 THC sector will remain gray.
Editor’s Note: The Legal Guide to the Business of Marijuana: Cannabis, Hemp and CBD Regulation is now available for purchase here.
About James T. O’Reilly
James T. O’Reilly of the University of Cincinnati College of Medicine is former chair of the 8,000-member Section of Administrative Law & Regulatory Practice of the American Bar Association and has been active in numerous ABA, Federal Bar Association, and state and local bar activities. He retired as Associate General Counsel of The Procter & Gamble Company to teach full-time, and served as a consultant to three federal agencies and to the Deputy Secretary General of the European Commission. He has authored fifty-six texts and more than 230 articles, and his work was cited numerous times in appellate opinions, including “The experts have written . . . ” in a March 2000 opinion of the U.S. Supreme Court (Food & Drug Administration v. Brown & Williamson Tobacco Corp., 120 S. Ct. 1291). He has received numerous honors and awards for his professional and electoral activities and has been listed in Who’s Who in American Law for twenty-five years. He is a graduate of Boston College and the University of Virginia School of Law.
About Edgar J. Asebey
Edgar J. Asebey, a partner at Asebey Life Sciences Law PLLC, is a regulatory and transactional attorney with over two decades of experience in federal regulation of pharmaceutical, biotechnology, medical device, food, dietary supplement and cosmetics companies. Since 2015, he has been working on cannabis-related matters and transactions, and since 2018, he has provided regulatory compliance, business transactional, venture finance and international trade services to hemp/CBD companies. Mr. Asebey practices before the FDA, the USDA, the CBP, the EPA, and the FTC, representing client companies on regulatory compliance, product approval/registration and FDA enforcement defense matters. He founded and served as president of Andes Pharmaceuticals, Inc., a natural products drug discovery company, from 1994 to 2000, and has served as in-house counsel to two life sciences companies. Mr. Asebey is a member of the American Bar Association (Section on Administrative Law & Regulatory Practice: Food and Drug Committee and International Committee), the Food & Drug Law Institute (FDLI), the Dade County Bar Association, and BioFlorida.
Few people will disagree that financial compliance isn’t the most exciting topic within the cannabis industry. But compliance is, and always will be, the engine grease to the legal cannabis market. Cannabis operators have the arduous task of dealing with multiple layers of compliance, both operational (maintaining and adhering to regulations enforced by the state licensing board) and financial. These compliance measures include managing everything from seed-to-sale systems for all plant-related activity to on-site requirements like facility access points and alarms systems to name a few.
With complex compliance requirements for the business, the last thing cannabis operators want to think about is financial compliance. We created Confia on this notion. Just as cannabis regulators impose the tracking of plants through the supply chain via a seed-to-sale system, we have developed a storyboard similarly designed to follow the money, which is the equivalent of a transaction-to-deposit system.
Having experience in regulatory technology, artificial intelligence and machine learning, we’ve been fortunate enough to work with some of the world’s largest banks across multiple countries. This experience has afforded us the luxury of working alongside regulators, chief compliance officers and chief risk officers, understanding how risk is perceived by financial institutions and how it ought to be mitigated. It was this access and knowledge that allowed us to effectively reform, enhance and improve the antiquated BSA programs with a technology-enabled process. Leveraging technology is a necessity, almost a requirement, for the cannabis industry as legalization nears and banking access begins to broaden.
Jamming cannabis requirements into an existing BSA program doesn’t scale well. BSA programs are very manual, descriptive and process oriented. So, we’ve taken our prior experience and success in banking to form Confia, distilling the complexities and simplifying the deliverables surrounding cannabis banking compliance. To best articulate cannabis banking requirements, I break it down into three pillars.
Pillar One: KYC-Enhanced Due Diligence
The first pillar is the client-onboarding bucket or KYC – Know Your Customer. In the complex world of cannabis banking, banks must know and understand their clients to great depths. It’s not enough to simply know that the client exists; you also have to understand whether or not that client could be a potential risk to the bank, and one step further, the financial system. Cannabis is a high-risk industry, so the KYC requirement is escalated to a deeper diligence and review, called Enhanced Due Diligence (EDD).
Cannabis is a high-risk industry so extra due diligence is needed
Banks need to know and understand their customers’ story, and all the key parties (officers, directors, and those with key decision-making powers or access to the bank accounts) within that organization. This includes reviewing personal, business, and legal history – not to mention watchlists and negative news presence. An initial onboarding review must then be followed with daily screening and monitoring of all watchlists and adverse media. Typically, banks do KYC refreshes every three years. In cannabis, a full refresh should be done annually with the daily monitoring systems in place.
The high-risk nature of the industry also requires a level of diligence on all parties to a transaction, even if one of the parties, whether a payer or recipient, is not a client of your bank. Unlike traditional banking sectors, reliance on other banks’ KYC programs is far less defensible in the cannabis industry.
Pillar Two: Transactional Monitoring & Detection
Tracking and monitoring the actual financial transactions comprises the second pillar required for cannabis banking. At Confia, we have focused on streamlining processes, so the cannabis operator can seamlessly support the compliance obligation for every transaction. A bank must demonstrate supporting documentation for every cannabis transaction, and gathering such information is a large undertaking in and of itself and can pose future issues if not done properly, see the pitfalls for lack of compliance. Banks are obligated to understand the nature and reason for each transaction, the source of funds, ensure cannabis licenses are in good standing for all parties, and collect evidence such as accounting records and seed-to-sale data.
Core to transaction monitoring in the traditional sense, is the overarching support through anomaly detection. Relying on information is important, but testing those inputs keeps everyone honest. It is important to evaluate transactions from a holistic point of view relative to peers and relative to the general contents of a transaction. This anomaly detection layer is your last line of defense, and as new information is collected, it continues to refine itself.
Pillar Three: Filing and Reporting Requirements
The third component to compliant cannabis banking is regulatory filing and reporting. Once a client is onboarded, the account requires an initial suspicious activity report or SAR-Initial within 30 days of that client being approved by the bank. Then, a report must be filed every 90 days after that for all the transactions of that cannabis operator. Banks must file the SAR-Initial and the Continuing-SAR reports for each cannabis client they have.
The high-risk nature of the industry requires a level of diligence on all parties to a transaction
Solutions like Confia automate the filing process and support the filing with transactional data evidenced on our distributed ledger of record. This provides immutable audibility and simplifies the process for all parties involved.
Compliance Requirements After US Legalization
The anticipation of federal legalization and banking reform bills has many operators hoping for easier banking. Yet, in my opinion, regulatory oversight and audits will likely increase after such reform or legalization. As other financial institutions start to support cannabis, it will inadvertently create greater opportunity and expose the financial system to nefarious or illegitimate transaction activity. This is why cannabis banking will be carefully monitored by regulators, and more so, why banks will be slow and pragmatic in standing up their internal cannabis banking programs. Some banks may forever avoid the cannabis industry due to the known pitfalls of an industry specific program, while others may simply mitigate the possible exposure to reputational risk.
Choose Wisely: Pitfalls for Lack of Compliance
Financial compliance is the responsibility and duty of the banks, but the real losers and result of non-compliance always fall on the cannabis operators. Regulatory action against an institution may result in the bank shutting down its cannabis program or may require them to complete a remediation of all their cannabis transactions for a certain period from its clients. At the end of the day, regardless of action, the cannabis operator is the one being punished. Operators either lose their bank account and have business massively disrupted, or they are asked to provide all the compliance docs for a historic period, which is a huge undertaking and operational distraction, ultimately impacting business and productivity. So, choose your banking partner wisely.
Summarizing Key Banking Requirements
In summary, banking in the cannabis industry will undoubtedly remain a high-risk industry, with or without legalization. Although banking opportunities may expand as US policies change, there will be continued compliance and regulatory requirements for the foreseeable future.
Onboarding and ongoing screening are critical
Evidence for every transaction is a significant portion of compliance and must not be dismissed
Evaluating activity with broader strokes is essential in mitigating against money laundering
Managing the staggered filing timelines and due dates for each client
Compliance is the most crucial factor in cannabis banking at this point. It cannot be overlooked or taken for granted. Cannabis operators must take an active role in evaluating the compliance programs of their financial providers. To open a bank account is one thing, but the consideration and effort that goes into keeping a bank account is the difference that will protect your business in the long run.
Cannabis is still federally illegal and is included on Schedule 1 of the Controlled Substances Act (CSA), along with such other substances as heroin, fentanyl and methamphetamines.1 It is a federal crime to grow, possess or sell cannabis.
Despite being federally illegal, 36 U.S. states and the District of Columbia have legalized the sale and use of cannabis for medical and/or adult use purposes,2 and both direct and indirect cannabis-related businesses (CRBs) are growing at a rapid rate. Revenue from medical and adult use cannabis sales in the US in 2019 is estimated to have reached $10.6B-$13B and is on track to reach nearly $37B in 2024.3
Because the sale of cannabis is federally illegal, financial institutions face a dilemma when deciding to provide services to CRBs. Should they take a significant legal risk or stay out of the market and miss out on a significant revenue opportunity? So far, the vast majority of financial institutions have been unwilling to take the risk, resulting in a dearth of options for CRB’s. Until recently, cannabis business operators had few options for financial services, but times are changing.
This piece will discuss current trends in banking for cannabis-related businesses. We will cover differences in legality at state and federal levels, complexities in dealing in cash versus digital currencies, Congressional actions impacting banking and CRBs and how banking is changing. The explosion of state legalization of cannabis over the past several years has had a strong ripple effect across the US economy, touching many industries both directly and indirectly. Understanding the implications of doing business with a CRB is both challenging and necessary.
Feds Versus States
Money laundering is the process used to conceal the existence, illegal source or illegal application of funds.4 In 1986 Congress enacted the Money Laundering Control Act (MLCA), which makes it a federal crime to engage in certain financial and monetary transactions with the proceeds of “specified unlawful activity.”5 Therefore, CRB transactions are technically illegal transactions under the MLCA.
Financial institutions therefore face a risk of violating the MLCA if they choose to do business with CRBs, even in states where cannabis operations are permitted. In addition, financial institutions could also face criminal liability under the Bank Secrecy Act (BSA) for failing to identify or report financial transactions that involve the proceeds of cannabis businesses operating legally under state law.6
Federal authorities continued to aggressively enforce federal cannabis laws
In short, because cannabis is illegal at the federal level, processing funds derived from CRBs could be considered aiding and abetting criminal activity or money laundering. States, however, began legalizing cannabis in 1996, and by 2009, thirteen states had laws allowing cannabis possession and use.7 Despite this legislation, federal authorities continued to aggressively enforce federal cannabis laws.8 That changed under the Obama administration when, shortly after being elected, President Obama stated that his administration would not target legal CRB’s who were abiding by state laws.[9] In an attempt to provide clarity in this murky environment, beginning in 2009, the Department of Justice (DOJ) issued three memos designed to guide federal prosecutors in this area. However, none of the DOJ memos issued from 2009 through 2013 addressed potential financial crime related to the legal sale or distribution of cannabis in states allowing the use of medicinal or recreational cannabis.
To assist financial institutions in navigating potential financial crime implications of banking CRBs, the Financial Crimes Enforcement Network (FinCen) issued guidance in 2014 that clarified how financial institutions could conduct business with CRBs and maintain compliance with their Bank Secrecy Act requirements (2014 Guidance).9 According to the 2014 Guidance, financial institutions may choose to interact with CRBs based on factors specific to each institution, including the institution’s business objectives, the evaluated risks associated with offering such services, and its ability to manage those risks effectively.
The 2014 Guidance requires those who choose to provide services to CRBs to design and implement a thorough customer due diligence review that includes, in part, analyzing the licensing of the entity, developing an understanding of the business operations of the entity, and ongoing monitoring of the entity.9 In addition, financial institutions are required to file a Suspicious Activity Report (SAR) for every transaction they process for a CRB, should they choose to accept the business.
Although the 2014 Guidance does outline a path for financial institutions to engage with CRBs, it does not change federal law and, therefore, does not eliminate the legal risk to financial institutions.10 By its very nature, the 2014 Guidance was a temporary fix, subject to changing views of different administrations, evidenced by the fact that all three of the DOJ guidance documents noted above were rescinded by then Attorney General Jeff Sessions on January 4, 2018.12 The DOJ enforcement posture could change once again in a Biden administration. Biden is on record as favoring decriminalization, and Attorney General candidate Merrick Garland has stated that if confirmed he will deprioritize enforcement of low-level cannabis crimes. Garland also believes using limited government resources to pursue prosecution of cannabis crimes states where cannabis is legal does not make sense.12
Because of the uncertainty and high risk, most banks remain unwilling to serve CRBs. Those that do serve CRBs charge exorbitant fees (fees of $750-$1,000 or more per account per month are not uncommon), pricing many smaller operators out of the financial services market.
Cash is King – Or Is It?
Cannabis operators have discovered the old adage “cash is king” is not necessarily true when it comes to the cannabis space. Bank-less CRBs are forced to utilize cash to pay business expenses, which can be particularly difficult. Utility companies, payroll companies, and taxing authorities are just some of the providers that are difficult, if not impossible, to pay in cash. For example, cannabis operators have been turned away from IRS offices when attempting to pay large federal tax obligations in cash. Likewise, cannabis operators have been unable to utilize payroll processing companies to administer payroll and benefits for their businesses because the processors won’t take cash. CRBs can’t use Amazon or other online retailers because online providers cannot accept cash.
Because dealing in cash is so difficult, CRB operators look for workarounds such as using personal credit/debit cards to purchase business equipment and supplies. This doesn’t eliminate the cash problem, however, because the credit card holder will likely have to accept cash as reimbursement. Such transactions could be considered an attempt to hide the source of the cash, which is, by definition, money laundering.
CRBs often have large sums of money onsite
Some bank-less CRBs try to skirt the system by obtaining bank accounts in the name of management companies or other entities one step removed from the actual business. While operators often choose this route in an effort to streamline business and operate out of the shadows, it again runs afoul of banking laws. Transferring cannabis related financial transactions to another entity is actually the very definition of money laundering – which, as noted above, is defined as the process used to conceal the existence or source of “illegal” funds.
In addition to the difficulties in making payments or purchasing business supplies, operating in a cash-heavy environment poses significant safety risks for cannabis operators. CRBs often have large sums of money onsite and transport large sums of cash when purchasing product or paying bills, making them a target for robbery. In 2017, there was a spate of dispensary robberies across the Phoenix Metro area, including one at Bloom Dispensary that took place during operating hours.13
Managing all that cash increases the cost of doing business as well, in the form of increased labor, insurance, and security costs. Cash must be counted and double counted, which can be time consuming for staff, not to mention the time it takes to deliver physical cash payments to hither and yon. Ironically, lack of banking significantly decreases transparency and clouds the waters of compliance, as operating strictly in cash makes it easier to manipulate reported financial results.
Potential Congressional Solutions
In recent years Congress has undertaken several efforts to pass legislation designed to address the state/federal divide on cannabis, which would likely clear the way for financial institutions to provide services to CRBs, including:
R. 1595 – Secure and Fair Enforcement Banking Act of 2019 (“SAFE Act”);
1028 & H.R. 2093 – Strengthening the Tenth Amendment Through Entrusting States Act (STATES Act); and
2227 – Marijuana Opportunity Reinvestment and Expungement Act of 2019 (MORE Act).
The climate in Washington DC, however, did not allow any of these initiatives to pass both houses of congress. Had any been sent to the White House, President Trump was unlikely to sign them into law.
The cannabis industry has new reason to believe reform is on the horizon with shift in political leadership in the White House and Senate. Newly anointed Senate Majority Leader Chuck Schumer recently committed to making federal cannabis reform a priority, and President Biden appears committed to decriminalization, reviving the hope of passage of one of these pieces of legislation.
The Changing Banking Landscape
Even though there is little in the way of formal protections for financial institutions, and with the timeline for a legislative fix unknown, an increasing number of banks are working with cannabis operators.
According to FinCen statistics, there were approximately 695 financial institutions actively involved with CRBs as of June 30, 2020. It is important to note that these statistics are based on SAR filings, which banks are required to file when an account or transaction is suspected of being affiliated with a cannabis business. However, some of these SARs may have been generated on genuine suspicious activity rather than on a transaction with a known cannabis customer.
Number of Depository Institutions Actively Banking Cannabis-Related Businesses in the United States (Reported in SARS)14
There are arguably more banking institutions offering services to CRBs than ever before. The challenges for CRBs are (1) finding an institution that is willing to offer services; (2) building/maintaining a compliance regime that will be acceptable to that institution; and (3) cost, given the high fees associated with these types of accounts.
How CRBs Get Accepted by Banks
The gap between CRBs’ need for banking and the financial services providers’ sparse and expensive offerings to the sector has created an opportunity for third-party firms to intervene and provide a compliance structure that will satisfy the needs of the financial institutions, making it easier for the CRB to find a bank.
These third-party firms perform extensive BSA-compliant due diligence on applicants to ensure potential customers are following FinCen guidance required to receive banking services. After the completion of due diligence, they connect the CRBs with financial institutions that are willing to do business with CRBs and provide checking/savings accounts, check writing capability, and merchant processor accounts. These firms often provide additional services such as armored car and cash vaulting services. Some of these firms also offer vendor screening, pre-approving vendors before any payments can be made.
One such firm, Safe Harbor Private Banking, started as a project implemented by the CEO of Partners Credit Union in Denver, Colorado, who set out to design a cannabis banking program that would allow Partners to do business with Colorado CRBs.15 The program was successful and has since expanded into other states who have legalized cannabis. Other operators include Dama Financial and NaturePay.
While these services offer hope for many CRBs, the downside is cost. These services perform the operations necessary to find, open, and maintain a compliant bank account; however, the costs of compliance are still high, pricing some small operators out of the market.
Is Digital Currency an Answer?
Digital currency is also making its way into the cannabis world. Digital currency, or cryptocurrency, is a medium of exchange that utilizes a decentralized ledger to record transactions, otherwise known as a blockchain. One of the largest benefits of blockchain is that it is a secure, incorruptible digital ledger used for, among other things, financial transactions.16 Blockchain technology offers CRBs a transparent and immutable audit trail for business and financial transactions. Several cannabis-specific cryptocurrencies have sprung up in the past several years, including PotCoin, CannabisCoin, and DopeCoin, to name a few.
In July 2019, Arizona approved cryptocurrency startup ALTA to offer services to the state’s medical cannabis operators.17 ALTA describes itself as a “digital payment club where cash-intensive businesses pay each other using digital tokens instead of cash.”18 ALTA members purchase digital tokens that are used to pay other members using a proprietary blockchain based system. The tokens are redeemable for US dollars at a stable rate of 1:1, and CRBs do not need a bank account to participate in the ALTA program.
ALTA proposes to pick up members’ cash and exchanges it for tokens, which are then used to pay other members for goods and services. Tokens may be redeemed for cash at any time.18 The company has been approved by the Arizona State Attorney General, and one of the first members they hope to enlist is the Arizona Department of Revenue (ADOR). Enlisting ADOR into the program would allow dispensary members to pay state taxes digitally rather than hauling large amounts of cash to ADOR offices.
Similarly, Nevada recently contracted with Multichain Ventures to supply a digital currency solution to the Nevada cannabis industry. Nevada Assembly Bill 466 requires the state create a pilot program to design a “closed loop” system like Venmo in an effort to reduce cash transactions in the cannabis sector. Like ALTA, Nevada’s proposed system will convert cash to tokens which can then be transacted between system participants.19
While both proposals are promising for Arizona and Nevada CRBs, the timeline as to when, or if, these offerings will come online is unknown. Action on cannabis reform at the federal level may render these options moot.
Looking to the Future
Although states are legalizing cannabis in one form or another in growing numbers, the fact that cannabis is still federally illegal poses a significant barrier to accessing the financial services market for CRBs. While most banks are still reluctant to offer services to this rapidly growing industry, there are more banks than ever before willing to participate in the cannabis industry. Recent changes in leadership in Washington DC offer a positive outlook for cannabis reform at the federal level.
As the “green rush” continues to envelop the country, financial services options available to CRBs are slowly growing. Many new options are now available to help CRBs find a bank, develop compliance programs, and manage the cash related problems encountered by most CRBs. However, these solutions may be out of reach for the budget-conscious small operator. Also, there are a number of cryptocurrency solutions designed specifically for CRBs; however, when, or if, these solutions will gain significant traction is still unknown.
References
Controlled Substances Act, 21 U.S.C., Subchapter I, Part B, §812.
“State Marijuana Laws”; National Conference of State Legislatures, February 19, 2021.
“Exclusive: US Retail Marijuana Sales On Pace to Rise 40% in 2020, near $37B by 2024”. Marijuana Business Daily, June 30, 2020.
Kaufman, Irving. “The Cash Connection: Organized Crime, Financial Institutions, and Money Laundering”. Interim Report to the President, October 1984.
S. Code § 1956 – Laundering of Monetary Instruments.
Rowe, Robert. “Compliance and the Cannabis Conundrum.” ABA Banking Journal, September 11, 2016.
“History of Marijuana as a Medicine – 2900 BC to Present”. ProCon.org, December 4, 2020.
Truble, Sarah and Kasai, Nathan. “The Past – and Future – of Federal Marijuana Enforcement”. org, May 12, 2017.
Sessions, Jefferson B. “Memorandum for All United States Attorneys”. January 4, 2018.
“Attorney General Nominee Garland Signals Friendlier Marijuana Stance”. Marijuana Business Daily, February 22, 2021.
Stern, Ray. “Robbers Hitting Phoenix Medical Marijuana Dispensaries: Is Bank Reform Needed?” The Phoenix New Times, April 11, 2017.
FinCen Marijuana Banking Update, June 30, 2020.
Mandelbaum, Robb. “Where Pot Entrepreneurs Go When the Banks Just Say No.” The New York Times, January 4, 2018.
Rosic, Ameer. “What is Blockchain Technology? A Step-by-Step Guide for Beginners.” com, 2016.
Emem, Mark. “Marijuana Stablecoin Asked to Play in Arizona Fintech Sandbox.” CCN.com, October 25, 2019.
http:\\Whatisalta.com\
Wagner, Michael, CFA. “Multichain Ventures Secures Public Sector Contract with Nevada to Supply Tokenized Financial Ecosystem for the Legal Cannabis Industry”, January 26, 2021.
This website uses cookies so that we can provide you with the best user experience possible. Cookie information is stored in your browser and performs functions such as recognising you when you return to our website and helping our team to understand which sections of the website you find most interesting and useful.
Strictly Necessary Cookies
Strictly Necessary Cookie should be enabled at all times so that we can save your preferences for cookie settings.
We use tracking pixels that set your arrival time at our website, this is used as part of our anti-spam and security measures. Disabling this tracking pixel would disable some of our security measures, and is therefore considered necessary for the safe operation of the website. This tracking pixel is cleared from your system when you delete files in your history.
We also use cookies to store your preferences regarding the setting of 3rd Party Cookies.
If you disable this cookie, we will not be able to save your preferences. This means that every time you visit this website you will need to enable or disable cookies again.