Tag Archives: California

HACCP

Implementing a HACCP Plan to Address Audit Concerns in the Infused Market

By Daniel Erickson
1 Comment
HACCP

The increasing appeal and public acceptance of medical and recreational cannabis has increased the focus on the possible food safety hazards of cannabis-infused products. Foodborne illnesses from edible consumption have become more commonplace, causing auditors to focus on the various stages of the supply chain to ensure that companies are identifying and mitigating risks throughout their operations. Hazard Analysis and Critical Control Points (HACCP) plans developed and monitored within a cannabis ERP software solution play an essential role in reducing common hazards in a market currently lacking federal regulation.

What are cannabis-infused products?

Cannabis infusions come in a variety of forms including edibles (food and beverages), tinctures (drops applied in the mouth), sprays (applied under the tongue), powders (dissolved into liquids) and inhalers. Manufacturing of these products resembles farm-to-fork manufacturing processes common in the food and beverage industry, in which best practices for compliance with food safety regulations have been established. Anticipated regulations in the seed-to-sale marketplace and consumer expectations are driving cannabis infused product manufacturers to adopt safety initiatives to address audit concerns.

What are auditors targeting in the cannabis space?

The cannabis auditing landscape encompasses several areas of focus to ensure companies have standard operating procedures (SOP’s) in place. These areas include:

  • Regulatory compliance – meeting state and local jurisdictional requirements
  • Storage and product release – identifying, storing and securing products properly
  • Seed-to-sale traceability –  lot numbers and plant identifiers
  • Product development – including risk analysis and release
  • Accurate labeling –  allergen statements and potency
  • Product sampling – pathogenic indicator and heavy metal testing
  • Water and air quality –  accounting for residual solvents, yeasts and mold
  • Pest control – pesticides and contamination

In addition, auditors commonly access the reliability of suppliers, quality of ingredients, sanitary handling of materials, cleanliness of facilities, product testing and cross-contamination concerns in the food and beverage industry, making these also important in cannabis manufacturers’ safety plans.

How a HACCP plan can help
HACCPWhether you are cultivating, harvesting, extracting or infusing cannabis into edible products, it is important to engage in proactive measures in hazard management, which include a HACCP plan developed by a company’s safety team. A HACCP plan provides effective procedures that protect consumers from hazards inherent in the production and distribution of cannabis-infused products – including biological, chemical and physical dangers. With the lack of federal regulation in the marketplace, it is recommended that companies adopt these best practices to reduce the severity and likelihood of compromised food safety.

Automating processes and documenting critical control points within an ERP solution prevents hazards before food safety is compromised. Parameters determined within the ERP system are utilized for identification of potential hazards before further contamination can occur. Applying best practices historically used by food and beverage manufacturers provides an enhanced level of food safety protocols to ensure quality, consistency and safety of consumables.

Hazards of cannabis products by life-cycle and production stage

Since the identification of hazards is the first step in HACCP plan development, it is important to identify potential issues at each stage. For cannabis-infused products, these include cultivation, harvesting, extraction and edibles production. Auditors expect detailed documentation of HACCP steps taken to mitigate hazards through the entire seed-to-sale process, taking into account transactions of cannabis co-products and finished goods at any stage.

Cultivation– In this stage, pesticides, pest contamination and heavy metals are of concern and should be adequately addressed. Listeria, E. coli, Salmonella and other bacteria can also be introduced during the grow cycle requiring that pathogenic indicator testing be conducted to ensure a bacteria-free environment.

Harvesting– Yeast and mold (aflatoxins) are possible during the drying and curing processes. Due to the fact that a minimal amount of moisture is optimal for prevention, testing for water activity is essential during harvesting.

Extraction – Residual solvents such as butane and ethanol are hazards to be addressed during extraction, as they are byproducts of the process and can be harmful. Each state has different allowable limits and effective testing is a necessity to prevent consumer exposure to dangerous chemical residues.

Edibles– Hazards in cannabis-infused manufacturing are similar to other food and beverage products and should be treated as such. A risk assessment should be completed for every ingredient (i.e. flour, eggs, etc.), with inherent hazards or allergens identified and a plan for addressing approved supplier lists, obtaining quality ingredients, sanitary handling of materials and cross-contamination.
GMPFollowing and documenting the HACCP plan through all of the stages is essential, including a sampling testing plan that represents the beginning, middle and end of each cannabis infused product. As the last and most important step before products are introduced to the market, finished goods testing is conducted to ensure goods are safe for consumption. All information is recorded efficiently within a streamlined ERP solution that provides real-time data to stakeholders across the organization.

Besides hazards that are specific to each stage in the manufacturing of cannabis-infused products, there are recurring common procedures throughout the seed-to-sale process that can be addressed using current Good Manufacturing Practices (cGMP’s).  cGMPs provide preventative measures for clean work environments, training, establishing SOPs, detecting product deviations and maintaining reliable testing. Ensuring that employees are knowledgeable of potential hazards throughout the stages is essential.Lacking, inadequate or undocumented training in these areas are red flags for auditors who subscribe to the philosophy of “if it isn’t documented, it didn’t happen.” Training, re-training (if necessary) and documented information contained within cannabis ERP ensures that companies are audit-ready. 

Labeling

The importance of proper labeling in the cannabis space cannot be understated as it is a key issue related to product inconsistency in the marketplace. Similar to the food and beverage industry, accurate package labeling, including ingredient and allergen statements, should reflect the product’s contents. Adequate labeling to identify cannabis products and detailed dosing information is essential as unintentional ingestion is a reportable foodborne illness. Integrating an ERP solution with quality control checks and following best practices ensures product labeling remains compliant and transparent in the marketplace.

Due to the inherent hazards of cannabis-infused products, it’s necessary for savvy cannabis companies to employ the proper tools to keep their products and consumers safe. Utilizing an ERP solution that effectively manages HACCP plans meets auditing requirements and helps to keep cannabis operations one step ahead of the competition.

Soapbox

Cannabis Pioneers vs. Cannabis Innovators: Who Has the Advantage?

By Jeff Arbour
No Comments

In today’s innovation marketplace, everybody wants to be the first. Tech and non-tech companies alike are racing to raise capital for crypto, blockchain and AI, yet these sectors and technologies are still not even close to mass adoption.

Today’s entrepreneurs are obsessed with disruption. While this is obvious in the world of tech, it may soon be overshadowed by the nascent cannabis industry in the United States. Every time a new state opens an application submission period for a new cannabis dispensary, hundreds of companies apply. Each new market and state have pre-existing demand. Until recently, obtaining cannabis was difficult for many and illegal.

Often, the latecomers who learn from pioneers’ mistakes are the ones who earn the greatest successes.

Most of these companies apply in good faith, only to run into unforeseen problems as the regulatory landscape changes. This is part of the risk inherent to pioneering and disrupting industries. Often, the latecomers who learn from pioneers’ mistakes are the ones who earn the greatest successes.

The Difference Between Pioneering and Innovating

In the world of commerce, paving the way for a new product to hit the market is usually a thankless, time-consuming task. It exposes the weaknesses of the market’s operators and invites newcomers to disrupt the already unstable status quo.

Although household names like Levi’s and Wells Fargo owe their success to the California Gold Rush, historians pay relatively little attention to the hundreds of thousands of casualties the Gold Rush caused. Pioneers paved the way, and innovators – like Levi Strauss – profited from the result.

Similarly, when it comes to cars, Peugeot and Tatra are not household names like Ford and Honda. Henry Ford’s assembly line innovations and Honda’s unbeatable factory flexibility led to those younger companies becoming far more successful than their older counterparts.

Pioneers change the way an industry operates. Airbnb did not succeed because it offered superior service compared to the powerful and deep-pocketed hotel industry. It succeeded because it improved the model that HomeAway and VRBO launched years prior – and did so in a way that undermined the hotel’s typical strengths while capitalizing on their weaknesses.

Pioneering disruption is not equal to innovation, and the cannabis industry will follow the same course.

Although pioneering the creation of new business models is an admirable thing to do, it’s not for everyone. Airbnb has been fighting regulators since the very beginning. The company has been forced to pay fines and taxes that simply didn’t exist until Airbnb’s business model came into being.

Uber’s regulatory troubles regularly make headlines around the world. Although it successfully disrupts every market it enters, established taxi companies and newcomers like Taxify often get the last laugh when they implement Uber-like functionality into existing business models. Uber found it too difficult to compete in China and sold its business to local newcomer Didi Chuxing.

All of these cases demonstrate that being the first or early to introduce a business concept comes with many challenges. Pioneering disruption is not equal to innovation, and the cannabis industry will follow the same course.

Cannabis Industry Pioneers vs. Innovators

In the cannabis industry, being the first often meant living in constant fear of being arrested. During the early years of medical cannabis legislation, it was unclear whether federal authorities would raid and prosecute cannabis cultivators and dispensaries.

Every new cannabis market offers important, expensive lessons to future cannabis entrepreneurs:

  • California changed its cannabis product packaging laws several times before its market went live.
  • Oregon’s lack of state inspectors led to a laboratory testing bottleneck and an upsurge in black market cannabis diversion that the state’s last audit called “currently unstoppable.”
  • The two largest medical marijuana cultivation facilities in Illinois cost about $40 million to build, yet they compete over a market of less than $10 million.
  • Major pioneers like Medmen have paid enormous sums of money to gain entrance into regulatory environments they can’t accurately predict profits from.

Newer cannabis industry entrepreneurs are taking notice of all these obstacles and implementing plans to overcome them. It’s likely that the next generation of medical and recreational dispensaries will have far greater success than today’s biggest names, primarily due to this fact.

Consider the fact that all three of the S&P’s biggest cannabis industry companies have valuations far in excess of their actual sales. It is possible that these large, deep-pocketed organizations will generate enough revenue to justify their valuations, but in the meantime, newer players will enter the picture with greater responsiveness and startup efficiency.

Newcomers to the cannabis industry are setting themselves up for success with highly targeted business objectives, strong executive teams and high-impact advisors. They are navigating the regulatory landscape with more agility than early cannabis pioneers can muster, obtaining lower price-to-sales ratios in the process.

Cannabis entrepreneurs need to be creative in their assessment of the opportunities these new environments create.

This is the hallmark of innovation. While disruptions and inventions typically take the form of new products or services, innovations expand marketplaces and lay the groundwork for new interactions between economic actors in those marketplaces.

What Tomorrow’s Cannabis Innovators Can Do Now

States like Pennsylvania, New York, and New Jersey are currently leaning towards recreational marijuana legislation like those currently in place in Colorado and California. Cannabis entrepreneurs need to be creative in their assessment of the opportunities these new environments create.

Opening a cannabis company is no small task. As regulators gradually come to agree on the requirements each state will ask its business owners to meet, the next generation of pioneering cannabis entrepreneurs will have to adapt. At the same time, a relatively small contingent of innovators – the new generation of Levi Strauss’s – will coincide to provide much-needed products and services to the incoming rush.

These innovators will not be limited to one side of the industry. Innovation thrives on integration, and tomorrow’s cannabis entrepreneurs are going to develop streamlined solutions for tackling today’s inefficiencies in ways that simply are not possible right now. These lean, sophisticated startups will use that path paved by the first generation of cannabis industry incumbents.

Cannabis innovators will need to develop solutions for minimizing the costs and complications of setting up companies in highly regulated environments. This can mean anything from developing superior seed-to-sale tracking POS integrations to building a more efficient supply chain and a path to the consumer.

With luck, the next generation of cannabis entrepreneurs will look to the past when informing their strategic decisions for the future.

Matt Engle
Soapbox

Insurers Must Play Catch-Up to Meet Cannabis Industry Needs

By Matt Engle
No Comments
Matt Engle

As the cannabis industry continues to grow, demand for insurance products is also increasing. While insurers have been cautious about entering a market that carries the stigma of a Schedule I drug, the cannabis industry is clamoring for insurance coverage options tailored to meet the needs of key players— distributors, growers, processors and retail dispensaries.

The escalating need for insurance products tailored to these cannabis business sectors has not expedited an increase in coverage offerings. The slow entry of insurance carriers into the cannabis sector can be tied to a reluctance to insure an industry with emerging and often unknown risks. This will begin to change as more information becomes available on what loss ratio trends look like in the cannabis industry.

For now, there is a wait-and-see stance held by insurance carriers. This presents a major concern for cannabis-related businesses that are subject to risk at every stage of the supply chain, with particular exposure for theft, general liability, crop loss, and product liability.some degree of crime and theft coverage is needed for these enterprises to help manage the risks associated with a cash-based business

Theft

For cannabis companies, the use of paper currency is a huge part of their risk exposure. Federal banking regulations have limited these businesses to dealing mostly in cash, which makes them a prime target for crime and fraud. Currently, only one carrier will insure coverage for cash and theft risk, and the policy is limited to $1 million for most risks. This is inadequate coverage since many operators have more than that amount on-site.

In states with legislation legalizing cannabis, the cannabis sector will be able to move away from operating in cash if Congress passes the Secure and Fair Enforcement (SAFE) Banking Act, which would protect financial institutions from liability for federal prosecution that could arise from servicing cannabis-related businesses authorized under state law. Until banking regulations give the cannabis industry the ability to operate as legitimate businesses with the stability and safety that would deter criminal activity, some degree of crime and theft coverage is needed for these enterprises to help manage the risks associated with a cash-based business.

General Liability

Cannabis-related businesses need the same general liability coverage as other businesses to protect their premises and operations from lawsuits involving public contact. However, standard general liability policies—which exclude Schedule I substances from coverage—were not created with cannabis businesses in mind. It is still difficult for these businesses to obtain adequate general liability as a result of the legal uncertainty associated with the industry.

Product Liability

Product liability exposures for cannabis businesses encompass a wide range of areas, including edibles, vaporizers, pesticides, mold/fungus, misrepresentation, label claims, breach of warranty, deceptive practices, and failure to warn.

A major area of exposure concerns accidents resulting from impairment. A cannabis cultivator, processor, distributor, or retailer potentially may be considered liable in the event a product defect results in injury after reasonable use or when label defects fail to warn users that a product may have psychoactive effects.

Another area of risk exposure involves products that contain THC, the psychoactive compound that gives cannabis users a high. As the number of THC-containing products such as edibles and tinctures increases, so does the potential exposure to product liability claims for manufacturers and retailers.

The California Cannabis Track-and-Trace (CCTT) system also has implications for product liability. The CCTT is a statewide system used to record the inventory and movement of cannabis and related products through the commercial supply chain. All state cannabis licensees, including those with licenses for cultivation, manufacturing, retail, distribution, testing labs and microbusinesses, are required to use this system. The product liability impact lies in its capacity to determine responsibility along the supply chain from seed to sale.

For example, if a plastic vape pen explodes, a product liability lawsuit could have repercussions for many touch points across the supply chain beyond the manufacturer of the pen–all of which can be identified through CCTT. Entities that touch cannabis products such as soil suppliers or delivery persons also have product liability risk exposure. Personal injury attorneys can find incident-related parties easily and determine liability. This makes it particularly important to add these parties to the policy as additional insureds to help reduce claims exposure.

Crop Loss

Another area of concern for risk exposure is crop loss. Crop insurance is generally hard to obtain due to the significantly different nature of cannabis crops compared to traditional crops like corn or soybeans.

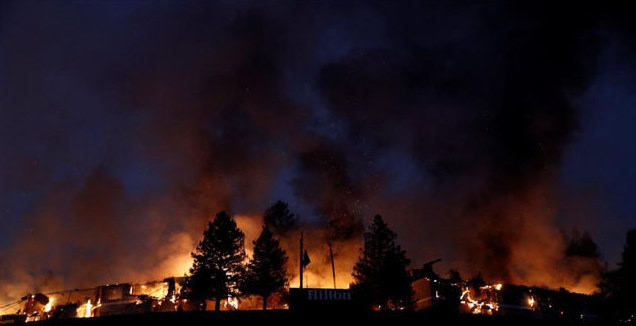
Fires in Sonoma County devastated cannabis crops in Northern California back in 2017.

An indoor crop insurance policy covers cultivators when there is loss resulting from threats such as fire, theft, and sprinkler leakage. However, crop insurance policies generally do not cover losses resulting from mold, rot, disease, changes in climate, or fertilization issues. Many growers forgo this coverage and instead elect to absorb losses and regrow their crops.

Outdoor crop coverage is generally unavailable, or the cost is prohibitive. Any potential for writing outdoor crop insurance for the cannabis industry essentially disappeared as a result of the recent wildfires in California. These devastating fires highlighted the pressing need for property damage and business interruption coverage for growers and dispensaries and other downstream businesses whose supply was disrupted. This lack of available outdoor crop insurance is one of the more notable gaps in available cannabis business insurance coverage.

While cannabis businesses operating in states that have legalized medical and/or recreational cannabis use have challenges getting adequate insurance coverage, there is some good news on the insurance front for those in California. Last year, California’s insurance commissioner announced approval for carriers to offer insurance coverage specifically to cannabis businesses. The state also approved a cannabis business-owners policy (CannaBOP) program that provides a package policy containing both property and liability coverage for qualifying dispensaries, distributors, manufacturers, processors and storage facilities. Colorado is on the verge of being the second state to approve its version of a CannaBOP program.

While more insurance carriers are beginning to write cannabis coverage, the limited insurance options and policies with restrictive plans currently offered todaydo not meet the needs of the cannabis industry. Insurers must catch up to the coverage requirements of this sector by offering more options tailored to growers, retail dispensaries, processors and distributors with better terms and better pricing.

european union states

Why International Trade Agreements Are Shaping The Cannabis Industry

By Marguerite Arnold
No Comments
european union states

If you have wondered over the past several years, why the big Canadian companies (in particular) are following the global strategy they are, there is actually a fairly simple answer: Newly implementing trade agreements, particularly between Europe and North America.

More specifically, they are highly technical trade agreements that are also called Mutual Recognition Agreements, (or MRAs).

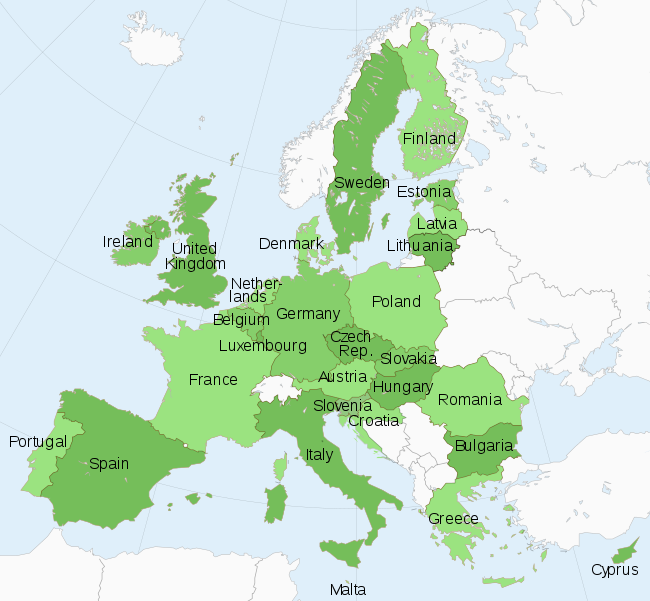
In fact, look at the schedule of the MRA agreements signed between the U.S. and individual EU countries over the last several years, and it also looks like a map of the countries that have not only legalized at least medical cannabis, but where the big Canadian companies (in particular) have begun to establish operations outside of their home country.

But what is going on is actually more than just CETA-related and also will affect cannabis firms south of the Canadian-U.S. border.

All of these swirling currents are also why the most recent MRA to come into full force in July this year, between the U.S. and Europe, is so interesting from the cannabis perspective. Even before federal reform in the U.S. If this sounds like a confusing disconnect, read on.

What Are MRAs?

MRAs are actually a form of highly specialized trade agreement that allow trading countries to be certain that the pharmaceuticals they purchase from abroad are equivalent to what is produced at home. This includes not only ingredients but processing procedures, production plant hygiene, testing, labeling and more.

When it comes to the  EU-US MRA agreement, this means that individual states of the EU can now recognize the American Food and Drug Administration (or FDA) as an effective federal regulator of American pharmaceutical production that is equal to the procedures in Europe. US GMP standards, in other words, will be recognized as equal to those of EU states.

This will now also, by definition, include GMP-certified medical cannabis formulations.

What is so intriguing, however, is how this development will actually place certain American (and Canadian) manufacturers in a first place position to import cannabis into Europe ahead of the rest of the American cannabis industry.

What Are Mutual Recognition Agreements All About?

One of the most important quality and consumer safety aspects of establishing a clean supply chain is tied up in the concept of GMPs (Good Manufacturing Practices). These are procedures, established by compliant producers of pharmaceuticals, to ensure seed (or source) to sale reliability of the medication they make. In the cannabis industry, particularly in the advent of Canadian-European transatlantic trade in cannabis, this has been the first high hurdle to accept and integrate on the Canadian side.

GMPIf European countries recognize a country’s GMP certifications are equivalent to its own, in other words, and cannabis is legal for export, a country can enter the international cannabis market without facing bans, in-country inspections and the like. In the interim, imported products still have to be batch tested until the agreements are fully accepted and operational.

Israel, for example, already had an MRA with the EU, and medical cannabis is legal in the country. However, Israel was prevented from selling cannabis abroad until a legislative change domestically, passed on Christmas Day.

That is why the MRA agreement between the US and EU with Canadian companies in the middle also put both Israeli and U.S. firms at an extreme disadvantage in comparison. Both in entering the market in the first place, and of course associated discussions, like the German tender bid. That is now changing- and as of this year.

A Specialized Map Of Global Medical Cannabis Exporters

Ironically, what the new US-EU MRA could also well do is create a channel for pharmaceutical cannabis from the United States to Europe (certainly on the hemp and CBD front) just as Israel is expected to enter the international cannabis export industry (later this summer or fall). It could well be also, particularly given the Trump Administration’s tendency to want to not only “put America first” if not pull off “a better deal” in general and about everything, that this is why President Trump offered the delay to Israel’s president Benjamin Netanyahu in the first place.

Regardless of the international individual developments and subtleties however, what is very clear that from the time the first bid stalled in Germany in the summer of 2017 until now, the U.S.-EU MRA has been in the room even if not named specifically as a driver.

For example, the FDA confirmed the capability of Poland and Slovenia to carry out GMP inspections in February of 2019.  It was only last fall that Aurora pulled off its licensing news in the former (on the same day licensing reform was announced by the government). Denmark was recognized in November of last year during the first year of its “medical cannabis pilot progam.” Greece was recognized in March 2018. Italy, Malta, Spain and the UK came online in November of 2017.

Overlay this timetable with a map of cannabis reform (and beyond that, cannabis production) and the logic starts to look very clear.

The upshot, in other words, is that while cannabis still may be “stigmatized” if not still “illegal” in many parts of the world, more generalized, newly negotiated and implementing, specialized global trade agreements between the US, Europe and Canada in particular have been driving the development of certain segments of the cannabis industry globally and since about 2013.

The Biggest News?

As of this year, as a result, expect at least from the GMP-certified front at least, that such international trade will also include medical cannabis from the U.S.

Want an example of the same? First on that list if not early in the game will now undoubtedly be Canadian-based Canopy Growth, with Acreage on board, headquartered in New York.

Water Policy in California: Six Key Takeaways from the State Water Board’s New Cannabis Cultivation Policy

By Amy Steinfeld
No Comments

Cannabis is the most highly regulated crop in California, and the state just added another layer of regulation. This article breaks down the State Water Resources Control Board’s (SWRCB) recently updated Cannabis Cultivation Policy – Principles and Guidelines for Cannabis Cultivation (“Policy”) into six key takeaways.1 These guidelines impose new rules on cannabis cultivation activities that have the potential to impact a watercourse (stream, creek, river or lake). Most of these rules apply to cultivation of sun-grown cannabis, which is currently allowed in some form in 12 counties. Compliance with these new requirements will be implemented through the CalCannabis Cultivation Licensing Program.

  1. When developing farmland, hillsides should be avoided and erosion must be controlled.

The Policy provides specific rules for growing pot on undisturbed land. To prevent erosion, numerous limitations are placed on earthmoving and activities in sensitive areas, and cultivators are not allowed to grade hillsides that exceed a 50% slope.2

Cultivation prepping activities must minimize grading, dust, soil disturbance, erosion, and impacts on habitat, especially during the winter season.3 No vehicles or heavy equipment may be used within a riparian setback4 or watercourse,5 and cultivators must avoid damaging native riparian vegetation6 and oak woodlands.7 All farm equipment, fuel, and hazardous materials must be carefully stored away from creeks and sensitive habitat.8 The Policy also governs road construction.9

  1. Cultivators should avoid work in or near a surface waterbody.10

If a cultivator’s activities impact a river, stream, or lake, they must consult with the California Department of Fish and Wildlife (CDFW).11 Cultivators must maintain minimum riparian setbacks for all cannabis activities, including grading and ancillary farm facilities. Before grading land, a biologist must identify any sensitive flora or fauna, and if any is located, consult with CDFW and provide a report to the Regional Board.12 No irrigation runoff, tailwater, chemicals or plant waste can be discharged to a waterbody.13 Diversion facilities for the irrigation of cannabis may not block fish passage, upstream or downstream, and must be fitted with a CDFW-approved fish screen; new facilities are subject to all applicable permits and approvals.

  1. During the dry season, cultivators may not use surface water.

The use of surface water supplies in California requires a valid water right and the use of water for cannabis cultivation is no different.14 Anyone seeking to appropriate “water flowing in a known and defined channel” or from a watercourse must apply to the SWRCB and obtain a permit or license.15 Alternatively, a landowner whose property is adjacent to a watercourse may have a riparian right to divert the water for use on her land. Riparian users do not need permission from the SWRCB to divert water, but they must report water use annually.16

The biggest obstacle that growers face under this Policy is that they cannot divert anysurface water during the dry season—the growing season (April 1 through Oct. 31). It should be noted:

  • The seasonal prohibition of surface water diversion applies regardless of the nature of the water right or what has been historically used to irrigate other crops.
  • During the dry period, cultivators may only irrigate using stored water (see no. 5 below) or groundwater.
  • It remains to be seen whether a legal challenge will be brought against the state for their draconian prohibitions on irrigating cannabis during the six-month growing season. Because this prohibition applies to all watersheds in California, singles out one low-water use crop, and ignores established water rights, it is overly broad and may constitute a constitutional “taking” of property rights.
  1. During the wet season, surface water diversions must be monitored closely.

Cannabis-specific restrictions also apply during the wet season. From Nov. 1 to March 31, cultivators must comply with instream flow requirements and check in with the state daily. All surface water diversions for cannabis are subject to “Numeric and Narrative Instream Flow Requirements,” to protect flows needed for fish migration and spawning. To ensure diversions do not adversely impact fish flows, cultivators must also “maintain a minimum bypass of at least 50% of the streamflow.”17,18

While valid appropriative right holders may divert more than 10 gal./min. for cannabis irrigation during the wet season, riparian right holders are not allowed to exceed that diversion rate.19 All cultivators (including small diverters <10 acre-feet (“AF”)/yr) are required to employ water-saving irrigation methods, install measuring devices to track diversions daily, and maintain records on-site for at least five years.20 Cultivators must inspect and repair their water delivery system for leaks monthly,21 and inspect sprinklers and mainlines weekly to prevent runoff.22

  1. Cannabis cultivators may obtain a new water storage right for use during the dry season.

To address dry season irrigation limitations, cultivators are urged to store water offstream during the wet season, including rainwater, for dry season use. Growers may not rely on onstreamstorage reservoirs, except if they have an existing permitted reservoir in place prior to Oct. 31, 2017.23 Alternatively, small growers (storage is capped at 6.6 AF/yr) may benefit from the new Cannabis SIUR Program, an expedited process for cultivators who divert from a surface water source to develop and install storage offstream. Only diverters with a valid water right that allows for diversion to storage between Nov. 1 and March 31 qualify.

  1. Groundwater is less regulated, but cultivators should avoid drilling or using wells near waterbodies.

Groundwater is generally the recommended water supply for cannabis because, unlike surface water, it may be used during the dry season and is not subject to many of the restrictions listed above. It should be noted however:

  • Many groundwater basins are now governed by California’s Sustainable Groundwater Management Act (“SGMA”), which requires water agencies to halt overdraft and restore balanced levels of groundwater pumping from certain basins. Thus, SGMA may result in future pumping cutbacks or pumping assessments.
  • In some counties, moratoriums and restrictions on drilling new wells are on the rise.
  • Under this Policy, the state may step in to restrict groundwater pumping in the dry season in watersheds where there are large numbers of cannabis groundwater, wells located close to streams, and areas of high surface water-groundwater connectivity.24

In short, groundwater pumpers are at risk of cutback if the state deems it necessary to maintain nearby creek flows.Noncompliance can bring lofty fines, revocation of a grower’s cultivation license, or prosecution

Final Takeaways

This cannabis policy presents one of California’s most complex regulatory schemes to date. Before investing in a property, one must understand this Policy and have a robust understanding of the water rights and hydrology associated with the cultivation site. Growers looking to reduce permitting time and costs should invest in relatively flat, historically cultivated land with existing wells and ample groundwater supplies, or alternatively, grow indoors.

This article attempts to synthesize the maze of water supply and water quality regulations that make compliance exceedingly difficult; more detailed information can be found here. Noncompliance can bring lofty fines, revocation of a grower’s cultivation license, or prosecution. Growers are encouraged to contact a hydrologist and water lawyer before making major investments and to designate a water compliance officer to monitor and track all water diversions and water used for irrigation. Growers should also consult with their local jurisdiction regarding water use restrictions and stream setbacks before moving any dirt or planting cannabis.


References

  1. The Policy is available at: https://www.waterboards.ca.gov/water_issues/programs/cannabis/cannabis_policy.html (will go into effect on or before April 16, 2019.)
  2. Policy, Appendix A, Section 2, Term 4. The Policy defines “Qualified Professional” as a: California-Licensed Professional Geologist, including Certified Hydrogeologist and Certified Engineering Geologist, California-Licensed Geotechnical Engineer, and Professional Hydrologist. (Policy, Definition 72, p. 11.)
  3. Policy, Appendix A, Section 2, Terms 4 and 10.
  4. Policy, Appendix A, Section 2, Term 3.
  5. Policy, Appendix A, Section 2, Term 40.
  6. Policy, Appendix A, Section 2, Term 33.
  7. Policy, Appendix A, Section 2, Term 34.
  8. Policy, Appendix A, Section 2, Term 7.
  9. Policy, Appendix A, Section 2, Terms 15 to 29.
  10. Policy, Appendix A, Section 1, Term No. 41.
  11. Policy, Appendix A, Section 1, Term No. 3; see also 1602.
  12. Policy, Appendix A, Section 1, Term No. 10.
  13. Policy, Appendix A, Section 1, Term No. 326.
  14. Policy, Appendix A, Section 2, Term 69.
  15. Wat. Code §1225; See alsoWat. Code §1201 [providing that the state shall have jurisdiction over, “[a]ll water flowing in any natural channel” except water that is appropriated or being used for beneficial purpose upon land riparian to the channel.”]
  16. Wat. Code §§ 5100–02.
  17. Policy, p. 12.
  18. Policy, Attachment A, pp. 60, 63.
  19. Policy, Section 2, Term 78.
  20. Policy, Section 2, Term 82.
  21. Policy, Section 2, Term 95.
  22. Policy, Section 2, Term 99.
  23. Policy, Section 2, Term 79.
  24. Policy, p. 11.

Taxes & Cannabis: 280E, R&D Credits, 199A & Qualified Opportunity Funds: Part 2

By Zachary Gordon, Jason Hoffman
No Comments

Editor’s Note: This is the second piece in a two-part series delving into tax issues. Part one discussed tax code 280E as it pertains to cannabis businesses. Part two will go into research and development credits, 199A and a discussion of risk as it relates to Qualified Opportunity Zones. 


While 280E is the most influential code section for the cannabis industry, structuring never happens in a vacuum. There are many open questions that each business must answer for themselves without court adjudication. We believe that among the riskiest of questions is whether a cannabis business can claim research and development credits.

There is no clear legal authority that either allows these credits or disallows them but certainly utilizing such credits comes at great risk. At the beginning of this article we talked about Congress and the purpose of 280E. Congress’s intention was to make sure that only the minimum required tax deductions were available to Schedule 1 and 2 sellers. A cannabis business receiving a research and development credit would not be with the intension of Congress. While the credits would be computed based on COGS expenditures, at this time we do not believe that a cannabis business should take this credit. Disallowance of COGS would create a constitutional challenge which is why Congress allowed the COGS deduction. Disallowance of Research and Development Credits does not open up the same constitutional issue since the credit is not part of COGS although calculated based on COGS expenditures. 280E states very clearly that credits arising from other code sections are disallowed in the entirety.

More recently the Tax Cut and Jobs Act (TCJA) opened up new issues for cannabis companies that are still unfolding. Two of the most publicized are Qualified Opportunity Funds and Section 199A, the 20% deduction (Qualified Business Deduction).

The 199A deduction allows eligible pass-through entities to claim an additional deduction of 20% of the income (subject to certain limitations) at the individual level potentially lowering the tax rate from 37% to 29.6%. While the American Institute of Certified Public Accountants (AICPA) and others have asked the IRS to clarify if 280E would make a cannabis business ineligible, the final regulations on the subject did not address this issue. There are other significant limitations and hurdles in 199A regulations that any business would have to first pass to be considered for the rate deduction. If a cannabis business meets all other eligibility and limitation criteria, should the pass-through income to their investors be qualified income under 199A? The answer will depend on whether the courts will treat this “deduction” as falling under the general prohibition of 280E.

We believe that there is a reasonable chance that the courts will allow the 199A deduction for cannabis companies. That does not mean, however, that we advise cannabis companies to claim this on their pass-through returns as Qualified Business Income. Much like everything else, it depends on the particular business and the risk profile that management is willing to tolerate. This is one area of tax law that is sure to be challenged in court. The more risk-averse business should pass on claiming this deduction on their returns, but monitor development with an eye to amending at a later date if favorable precedent emerges. If the amounts are large enough, consideration should be given to applying for a Private Letter Ruling, but that also has its own tax risks.

Another new tax incentive that was in the TCJA was Section 1400Z or Qualified Opportunity Zones (QOZ). The incentive allows for the deferral of capital gains until December of 2026. The use of 1400Z also results in up to a 15% decrease in capital gains tax- and tax-free appreciation if all requirements are met. While the IRS has only released proposed regulations and we anticipate significant changes to them when they are released as final, there was nothing in the proposed regulations limiting cannabis businesses from using Qualified Opportunity Funds (QOF) in their structure. It is interesting to note that the TCJA and proposed regulations did list other types of businesses that could not make investments under 1400Z along with all its benefits. Liquor stores, golf courses and sun tan parlors were among those listed but cannabis growers and dispensaries were not.

As the industry continues to mature, new issues and precedents will require CPAs and attorneys to find new solutions to best serve the industry.Using Opportunity Zones to entice investors sounds like a great opportunity, but there are significant risks. The first risk is that the proposed regulations, while currently proposed, may not be final. There is always a chance that the IRS will take a different position when the final regulations are released and add cannabis to the type of businesses that do not qualify. Another risk, and one that was previously mentioned as part of 199A and other areas of structuring, is that the IRS and the courts can always disagree with the taxpayer’s position. This is a new area of tax law and will eventually be litigated. The loss of the Opportunity Zone benefits can significantly change the return to the investors and lead to other issues.

All of these issues come into play when structuring businesses in this industry. These issues must be evaluated as they pertain to the business needs. This can be very complex and requires a great deal of research for each business opportunity. We have found that professionals operating in this industry like to know about all of their options. The most important thing we can do for the industry is to continue to educate the professionals working in it.

Accountants should be available to assist their clients and their clients’ attorneys with structuring techniques aimed at asset protection and minimizing 280E disallowances. Accountants should also be ready to speak to the questions outlined above and be prepared to explain the risks associated with each choice. As the industry continues to mature, new issues and precedents will require CPAs and attorneys to find new solutions to best serve the industry.

Introducing the Cannabis Quality Conference & Expo

By Aaron G. Biros
1 Comment

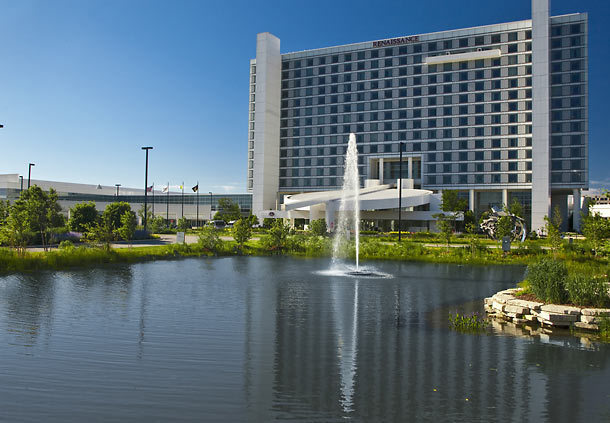
An educational and networking event for cannabis safety and quality solutions: Innovative Publishing and Cannabis Industry Journal are pleased to present the first annual Cannabis Quality Conference & Expo (CQC). The conference will take place October 1-3, 2019, hosted at the Renaissance Schaumburg Convention Center in Schaumburg, Illinois.

The inaugural CQC will consist of two separate tracks: The Cannabis Labs track, focused on all things cannabis lab testing, and the Cannabis Quality track, focusing on quality in cannabis product manufacturing.

Sharing an exhibit hall and meeting spaces right alongside the Food Safety Consortium Conference & Expo, the CQC allows cannabis professionals to interact with senior level food quality and safety professionals, as well as regulators. Visit with exhibitors to learn about cutting-edge solutions, explore two high-level educational tracks for learning valuable industry trends, and network with industry executives to find solutions to improve quality, efficiency and cost effectiveness in a quickly evolving cannabis marketplace.

The CQC will be hosted at the Renaissance Schaumburg Convention Center in Illinois (just outside of Chicago)

With the cannabis industry in the Midwest growing at a rapid pace, the CQC offers attendees, exhibitors and sponsors unparalleled access to explore these emerging markets, their regulations, opportunities for business growth and best practices from the more established food industry.

For information on speaking opportunities and to submit an abstract, click here to view the Call for Proposals. The CQC will be accepting abstracts for consideration until June 3, 2019. For information on exhibiting, as well as additional sponsorship opportunities, contact RJ Palermo, Sales Director, rj@innovativepublishing.net, (203) 667-2212.

Take advantage of this chance to connect with cannabis industry and food safety professionals in the Greater Chicago Area. Don’t miss this opportunity to network with hundreds of industry stakeholders, get the latest on regulatory developments and see the newest technology disrupting the cannabis space.

Taxes & Cannabis: 280E, R&D Credits, 199A & Qualified Opportunity Funds: Part 1

By Zachary Gordon, Jason Hoffman
3 Comments

Editor’s Note: This is the first piece in a two-part series delving into tax issues. Part one discusses tax code 280E as it pertains to cannabis businesses. Part two will go into research and development credits, 199A and a discussion of risk as it relates to Qualified Opportunity Zones. Stay tuned for Part two coming next week!


When building a knowledge base in the cannabis industry as a CPA, one’s tax research typically starts with Internal Revenue Code (IRC) Section 280E. For those that are unfamiliar, 280E is only three lines long. With this in mind, we at Janover realized that we needed to understand the context for this highly influential tax section.

The genesis of 280E dates back to 1981 with a Tax Court case: Jeffrey Edmonson v. Commissioner. The decision in this case was that a seller of cocaine, amphetamines and cannabis could deduct most business expenses, cost of goods sold, packaging, home, phone and automobile expenses relating to the seller’s illegal business.

In 1982, 280E was enacted to reverse the Edmonson decision and deny sellers of Schedule 1 or 2 controlled substances the right to deduct business expenses. Under the Controlled Substances Act, the federal government defined Schedule 1 drugs as drugs that have no currently acceptable medical use and a high potential for abuse. Since cannabis is classified as a Schedule 1 drug, cannabis businesses were unable to deduct most business expenses.

To get a better understanding of what the legislators were trying to accomplish, House and Senate reports provided insight into what their goals might have been. Under the Explanation of Provision, the Senate Report reads:

All deductions and credits for amounts paid or incurred in the illegal trafficking in drugs listed in the Controlled Substances Act are disallowed. To preclude possible challenges on constitutional grounds, the adjustment to gross receipts with respect to effective costs of goods sold is not affected by this provision of the bill.

As the Senate Report explanation provides, 280E specifically excluded cost of goods sold (COGS) from the disallowance of deductions. This treatment was affirmed by the Tax Court in 2012 in Olive v. Commissioner (139 T.C. 19 2012).

To date, there are not many cases that have dealt with the tax issues of 280E. In a 2007 decision involving Californians Helping to Alleviate Medical Problems (CHAMP), the Tax Court ruled that a taxpayer may deduct expenses allocable to an affiliated business that was separate from the entity “trafficking in a controlled substance.” In CHAMP, the legal caregiving business, which was a separate business, was able to deduct the allocated portion of shared expenses. This set a legal precedent that allowed a taxpayer engaged in the selling of a Schedule 1 or 2 controlled substance to distinguish expenses incurred on behalf of other non-prohibited business lines and deduct these expenses.

In addition to these court cases, tax professionals can rely on IRS Chief Counsel Memorandum CCA 201504011. The IRS Chief Counsel released this memorandum in January 2015 in order to respond to questions the IRS was receiving from practitioners.

Although Chief Counsel Memoranda, in general, may not be cited by taxpayers as precedent, this memorandum is the current and best authority outlining the IRS’s position with respect to the extent to which a cannabis business may deduct business expenses. The memorandum also refers to IRC Section 162, ordinary and necessary business expenses that would be disallowed, as well as separately identifying certain direct and indirect business expenses that would be allowed. Citing methods in Treas. Reg. 1.471, the memorandum states that a cannabis producer may allocate to inventory and COGS direct production costs, including direct material costs (Cannabis seeds or plants), direct labor costs (e.g., planting, cultivating, harvesting, sorting, etc.), and transportation or other costs to acquire of the cannabis. It also indicates certain indirect costs that may be taken as COGS.

As the industry continues to mature, more cases are finding their way to the Tax Court. On June 13, 2018, the Tax Court issued a ruling in Alterman v. Commissioner that specifically disallowed the use of 263A under 280E and applied only Section 471 to determine COGS. While we need to follow the facts and circumstances of each case, the broad language used might very well disallow capitalizing of inventoriable costs for companies subject to 280E.

IRC Section 471 is the general rule for inventory accounting for tax. IRC Section 263A is the uniform capitalization rules for tax. Most businesses need to utilize both 471 and 263A when accounting for inventory and to properly capitalize costs into COGS.This opinion may have lasting effects on the part of the industry trying to create brands associated with their cannabis products.

Many resellers and retailers of cannabis thought they could use 263A to capitalize more costs into inventory decreasing their tax burden. The Chief Counsel Memorandum disagreed and more recently the Tax Court in Patients Mutual Assistance Collective Corp v Commissioner sided with the IRS and upheld some of the precedents set in Alterman v. Commissioner. In siding with the IRS, the judge concluded that a taxpayer who is subject to 280E can only deduct costs of goods sold under 471 as the IRC existed when 280E was enacted (in 1982). The taxpayer in the case used two arguments that were not new to the cannabis industry, but to no avail. The first argument was that the business was not trafficking in a controlled substance because the government had abandoned a civil forfeiture action. The second argument that was rejected was that a portion of the business involved branding, marketing and the sales of other non-illegal products. The claimant tried to convince the court that deductions related to these operations should not be subject to the same disallowance of deduction as outlined in 280E.

This second argument is very important for structuring purposes. The court used a significant portion of its opinion to address why the entire business is integrated and completely subjected to 280E. This opinion may have lasting effects on the part of the industry trying to create brands associated with their cannabis products.

This case has even more implications given part of the ruling in which the courts stated that being state licensed in no way effected the Schedule 1 determination at the federal level and, therefore, subjected them to 280E. The judge went so far as to separate the Department of Justice, which enforces the Schedule 1 status of cannabis, and the Department of the Treasury, which has full authority and enforcement rights to treat cannabis as a Schedule 1 drug subject to 280E for income tax purposes. This ruling made it clear that even if the Department of Justice is not pursing criminal charges against state-licensed cannabis businesses the IRS is not precluded from fully enforcing the Internal Revenue Code.

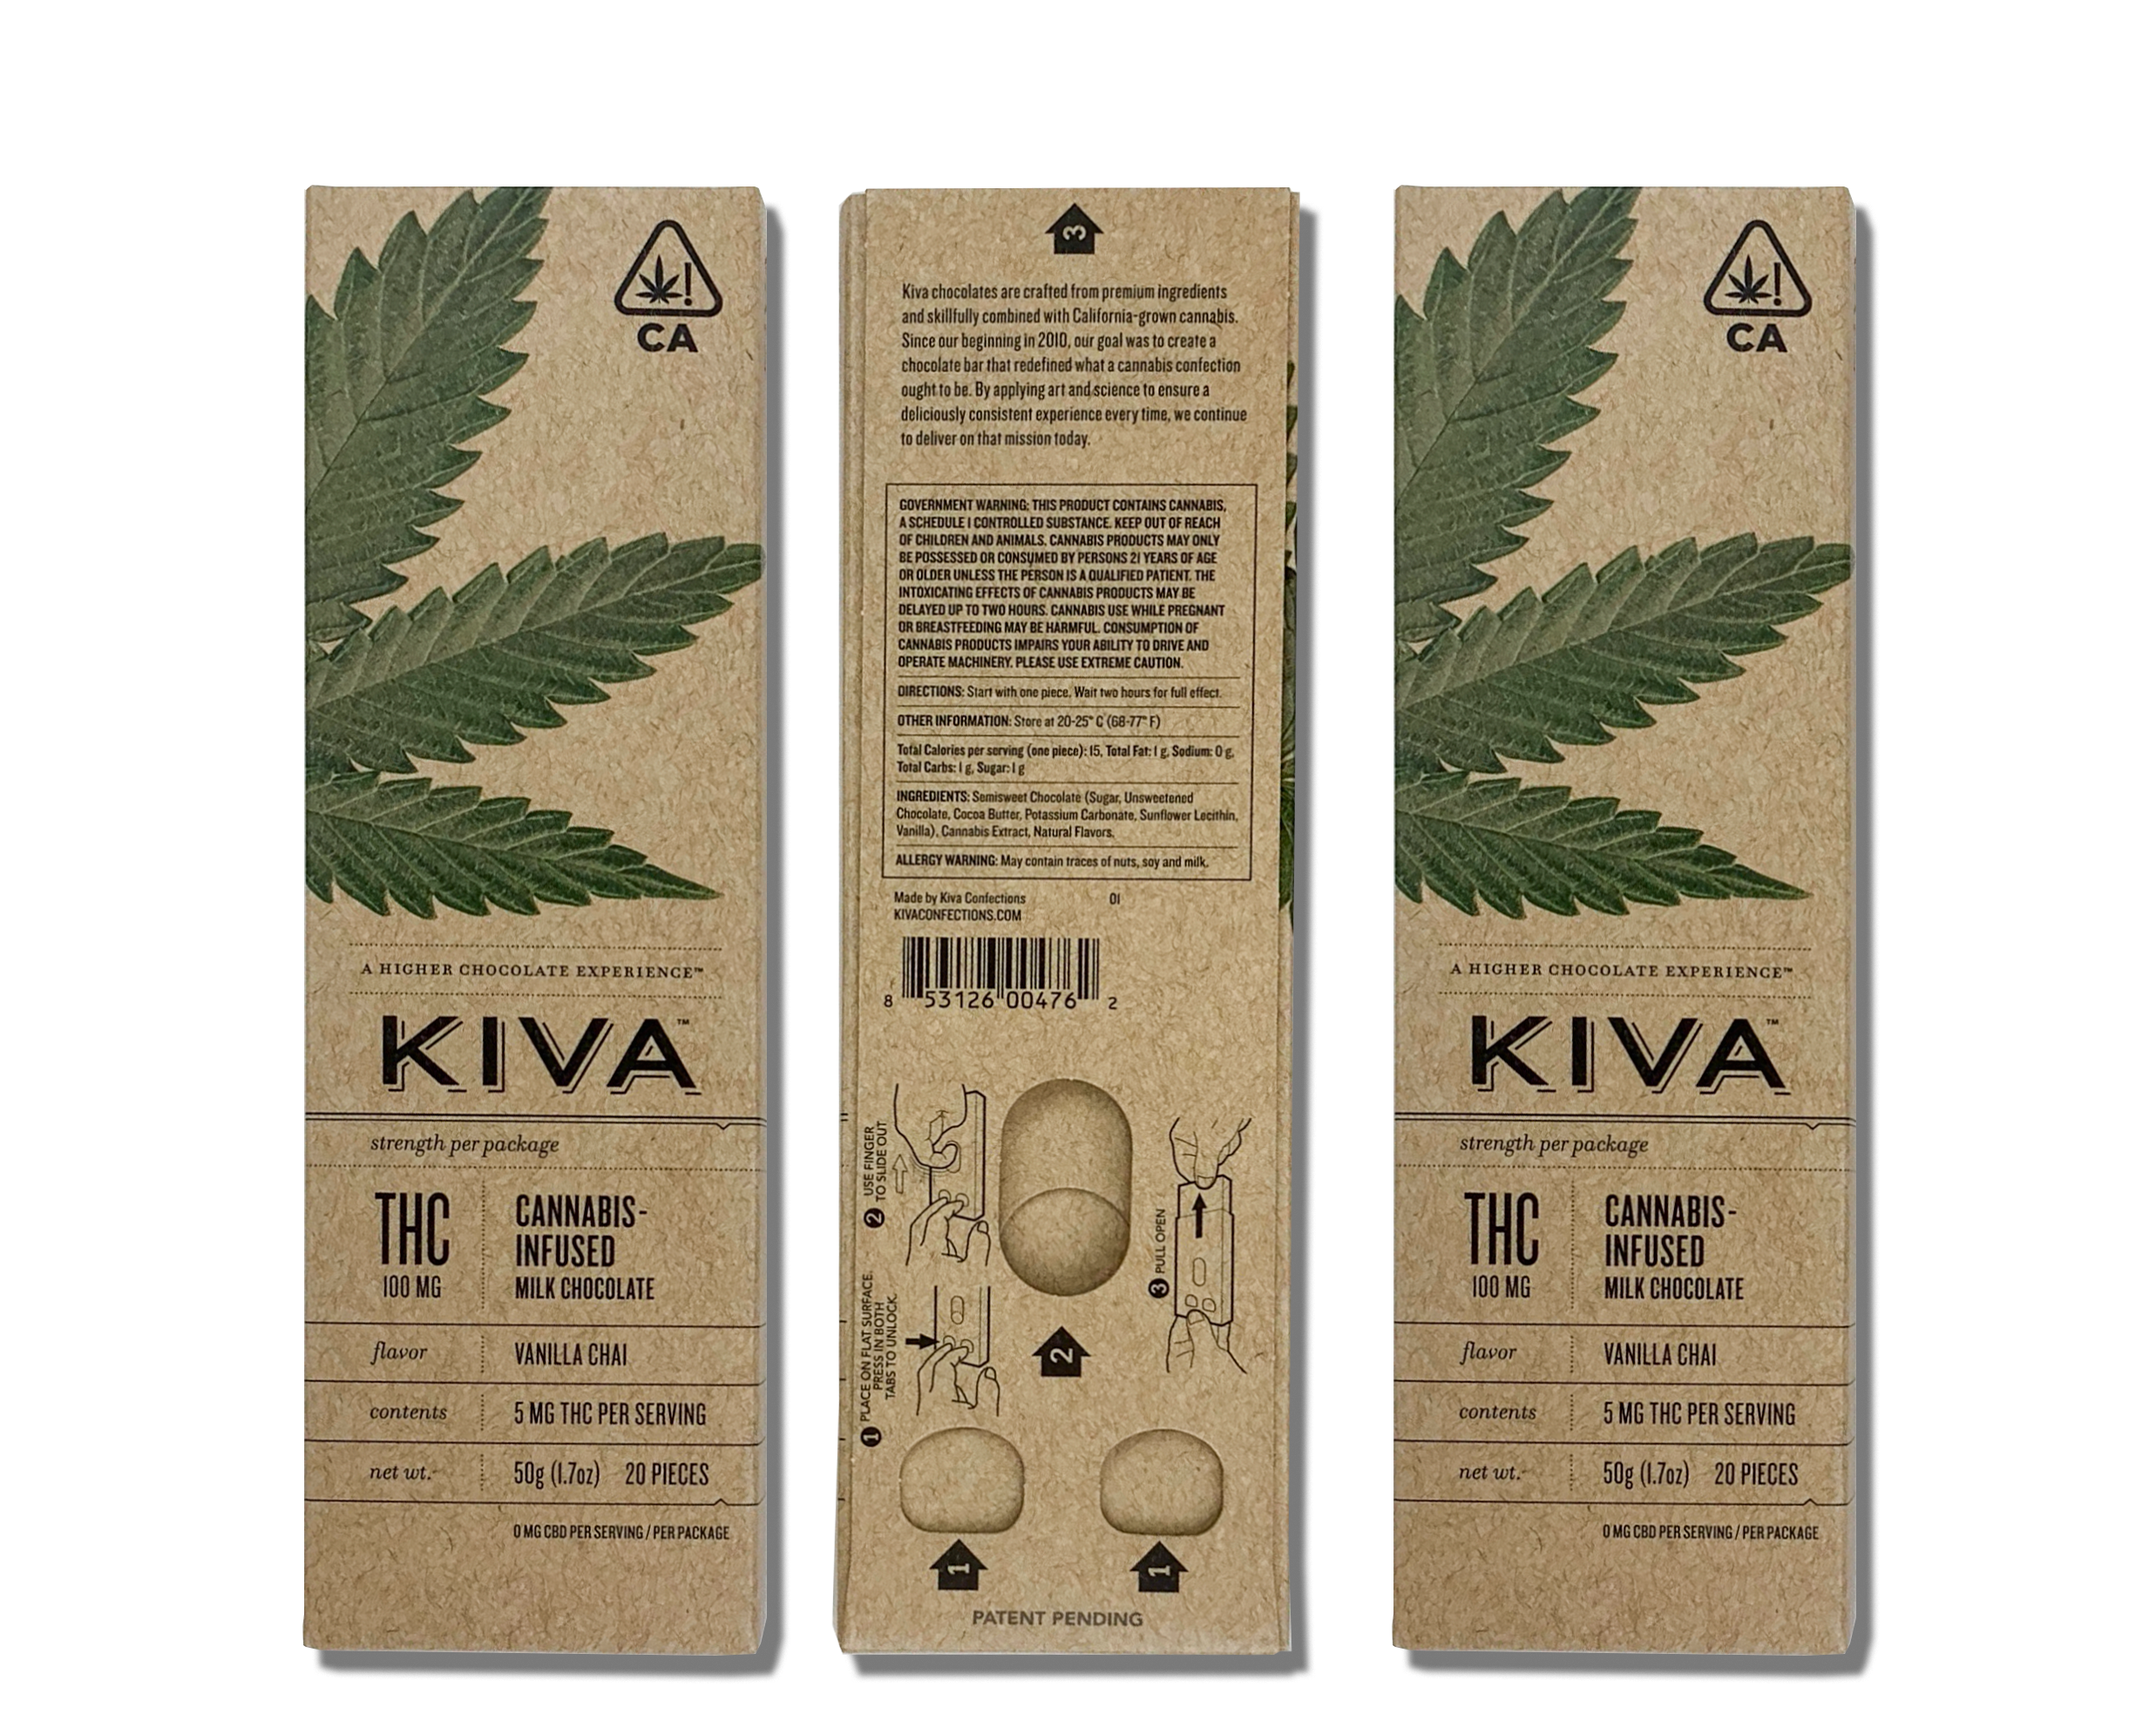
Child-Resistant Packaging Designed for Adults

By Pate Gustafson
9 Comments

As the cannabis industry grows so does the crucial need for child-resistant (CR) packaging solutions. There’s a long list of federal regulations that are required for any cannabis product to ensure that the package is both difficult for children to open, yet easily accessible for adults. This formula can often be difficult; add design into the mix and your packaging solution just got extremely complex.

However, brand image and appeal does not need to be sacrificed over packaging requirements. With the use of print effects, interactive elements, and captivating colors and designs, companies can create the ideal paperboard packaging for cannabis products while staying within federal regulations.

Let’s start with the packaging requirements first.

Child-resistant packaging can look aesthetically pleasing with the right design

CR Packaging Requirements for Cannabis Products

Depending on the state you do business in, your cannabis product is subject to a variety of child-resistant regulations that will keep children safe from potentially harmful materials. These regulations create packaging that is unappealing and inaccessible to children. Key elements of CR packaging for cannabis include:

  • Packaging must have resealable features
  • Packaging must exhibit a clear and detailed information label
  • Packaging must have an opaque appearance
  • Packaging must make product unappealing and unattractive to children

CR compliance requires that packaging undergo rigorous tests. The general concept is for the packaging to be difficult for children under 5 to open, while simultaneously being easy for adults to open and close.

These regulations create an immensely safer product for children. However, these same regulations limit the creative opportunities that normal packaging can provide, making most packaging for cannabis unattractive for adults.

CR Regulations & Packaging Challenges

Although CR regulations for cannabis products are vital to keeping children safe, these regulations cause a lot of roadblocks in the creative department.

Follow these tips to create a high-quality, CR-compliant cannabis carton packaging that the market will love.One of the most significant impacts these regulations have made on cannabis companies is the difficulty to align a brand image with these regulations. Every company has a brand image with which they need to align their entire marketing plan, including packaging designs. Add in strict CR regulations, and it becomes extremely difficult to balance the two.

Another key challenge in this process is structural design limitations. Businesses use inventive and innovative structural designs to help differentiate their products in a growing and crowded market. Cannabis products experience a significant disadvantage here. Cannabis companies must incorporate an opaque appearance and resealable features while also attempting to design a packaging structure that is attractive and eye-catching to consumers.

Designing CR-Compliant Cannabis Packaging that is Appealing to Adults

Although CR requirements make it challenging for companies to inject creativity into packaging designs, innovative solutions in the market do exist. These offer the best of both worlds by meeting the necessary CR guidelines, while maximizing branding, structural elements and print effects.

Incorporate Captivating Colors

Since there are no color restrictions for CR packaging, one of the best ways for a brand to express itself is through color. Companies are free to express themselves to tell a brand story utilizing unique colors in their packaging.

Before choosing a color palette, brands should ensure that packaging designs meet overall branding requirements. Consistency across branding, marketing and other avenues, will make any brand more recognizable and memorable. Colors can also set cannabis products apart from the hundreds of other products.

Smart packaging design can be simple with some good printing effects

Get Creative with Structural Design

Although CR regulations seem extremely restricting structurally, there are plenty of ways to still have a structurally appealing cannabis carton packaging while still in compliance with CR regulations. Just remember that cannabis packaging must be resealable and opaque.

In order to capitalize on your structural design process, experiment with different carton structures. Generally, carton packaging is rectangular or square but there’s ample opportunity for a variety of forms. Experimenting with designs, whether a straight carton or cartons with built-in trays, is an important step in finding the best packaging design that protects, promotes and differentiates the product it holds.

Never Overlook Print Effects & Finishes

Print effects and finishes are often an afterthought for cannabis carton packaging. Print effects and specialty finishes can make all the difference when looking for ways to set any cannabis product apart. The perfect finishing can take an average cannabis carton to the next level. Popular print effects include:

EmbossingJust because you have to stay aligned with CR regulations doesn’t mean that packaging should be plain and unattractive. 

Embossing is the art of incorporating a raised image, design, or pretty much any textural component in a packaging’s design. The process of embossing allows for artwork and specific elements to stand out against the background of the paperboard material.

Debossing

Debossing, as its name implies, is the opposite of embossing. Instead of creating a raised pattern, debossing creates a pressed imprint. It’s a great way to create a tactile experience and bring something extra to a packaging design while staying compliant with CR regulations.

Embossing and debossing can be used in conjunction with a variety of foil effects and other print finishing processes.

Making Interactive Experiences

The packaging is only as memorable as the process of opening it. Making packaging memorable requires focusing on creating an experience. Elements such as reveal flaps, tear-aways, doors and more are unique ways to add interactivity to a package design. This is great for increasing engagement and brand loyalty within your target market. Who says adults can’t have fun too?

Just because you have to stay aligned with CR regulations doesn’t mean that packaging should be plain and unattractive. Follow these tips to create a high-quality, CR-compliant cannabis carton packaging that the market will love.

Soapbox

Third-Party Cannabis Safety Audits & How to Prepare in 7 Steps

By Tyler Williams
2 Comments

Unlike the food industry, the cannabis industry is still in its infancy. Which means there is not a push from retailers demanding cannabis farmers, extractors or manufacturers to get third-party audits. In fact, most grow operations supply into their own dispensaries. So why should a cannabis farmer, extractor or manufacturer get a third-party audit? Third-party audits are crucial to maintaining product safety and quality by providing a third set of eyes to verify what is working and what is not. Besides regulatory requirements and customers requiring your facility to get a third-party audit, there are numerous other benefits to receiving an audit. Some of these benefits include:

  • Improvement to product safety
  • Improvement to product quality and consistency
  • Meeting regulatory compliance
  • Eliminating potential risks and possible recalls
  • Marketing advantages over competitors who are not audited by a third-party
  • Improvement to consumer confidence and an increase to brand loyalty

How to Prepare for a Third-Party Audit

Working for a certification body, I am in the unique position to see numerous sites go through the certification process. In this position I have seen both extremes: Sites that spend 6-8 months and a lot of resources preparing for an audit, as well as sites that wait until the day before to even look at the audit standard. Unfortunately, the latter is almost always going to fail the audit. Here are seven steps for preparing for your next third-party audit.“By failing to prepare, you are preparing to fail.”– Benjamin Franklin

  1. Start Preparing Early

Think of your third-party audit as a college exam one month away. You could start studying for the exam now and get a real understanding of the material or you could wait until the day before to start your no-sleep, energy drink-fueled, 24-hour cram session. We all know which preparation method will get a better score on the exam. Now let’s apply that same strategy to your third-party audit. Once you have decided what audit is best for your site and have those specific standards in your hand, the clock starts ticking and you should already be preparing for the audit, whether it is one month or six months away.

  1. Get Management Commitment

It is essential to the entire cannabis safety and quality system to have commitment from top down. Without this, the site will not get the resources (people, equipment, money, time, etc.) they need to pass a third-party audit. Management commitment is so important that it is often seen as its own section in most modern audit standards. It is very easy for third-party auditors to identify when there is a lack of management commitment in a site. Therefore, if you don’t get management commitment, then you are already starting off the audit on a bad note.

  1. Create a To-Do-ListGMP

Think of the entire audit checklist or standard as your long to-do list. Some things, like attaining a certificate of analysis (COA) from a supplier, may only need to be done annually. While other things, such as ensuring employees are following Good Manufacturing Practices (GMPs), will need to be done continuously throughout day to day operations. Go through the audit checklist and separate what needs to be done annually, semiannually, quarterly, monthly and continuously throughout day to day operations. This will give you a list with all of the frequencies of each different requirement.

  1. Teamwork“Teamwork makes the dream work, but a vision becomes a nightmare when the leader has a big dream and a bad team.” – John C. Maxwell

The preparation of an audit should never rest on the shoulders of one person. Yet this is something I tend to see too often in both food and cannabis facilities alike. Your site should establish a cannabis safety and quality team of multidiscipline personnel that have an impact on product safety and quality. Once the team is established, various tasks from the to-do-list can be disbursed among all the members of the team. Collaboration is key to successfully preparing for a third-party audit, especially when the timelines are very stringent.

  1. Training

Training is essential to preparing for your third-party audit. This is what closes the gaps between what the safety and quality department have developed and what your front-line employees are applying. All employees should know what part of the audit standard applies to them. Additionally, employees should be trained on interview questions that the auditor might ask them during the audit. Helping them prepare for these types of questions will help ease their nerves and allow them to answer the questions with self-assurance when it comes time to the actual audit.

  1. Conduct Internal Audits

Conducting internal audits is not only a great way to prepare for your third-party audit, it’s a requirement. You should always use the audit checklist to observe your documents and facility to see where there are gaps. If possible, the person or team conducting the internal audit should never review their own work. Additionally, all issues or non-conformances should be noted, evaluated, corrected and closed out.

  1. Third-Party Pre-Assessment or Mock Audit (Optional)

A third-party pre-assessment or mock audit is the closest thing you can get to an actual audit. This is where a company would come in and evaluate your site to the specific standards and give a formal report over any deficiencies found during the assessment and how to fix them. This is a great way to test your preparedness before the actual audit.