Tag Archives: europe

EU Regulations Address Heavy Metals In Consumer Products

By Christopher Dacus
No Comments

RoHS 3 (EU Directive 2015/863) adds a catch-all “Category 11” of regulated products that includes electronic nicotine delivery systems (ENDS), e-cigarettes, cannabis vaporizers and vape pens. This category becomes effective July 22, 2019. The most significant restricted substance applicable to this category is lead, and RoHS requires regulated products to contain less than 1000 parts per million (ppm). This follows on the heels of California’s new 2019 regulations requiring the testing of contents of cannabis vape cartridges using even stricter limits for lead (which makes sense because it applies to the product being consumed, not the separate electronic components). These regulations may seem unrelated, but anecdotally there have been widespread reports of higher than expected lead content in China-sourced electronic components, including both cartridges and related electronics. Whether metal used in e-cigarette type products is the source of any lead in the actual nicotine, cannabis or other concentrated product is an entirely different topic, but new laws, and in particular the new RoHS catch-all category, make 2019 an important year for any company responsible for certifying or testing lead levels in e-cigarette or vape products.

Background on EU RoHS

RoHS (Restriction of Hazardous Substances) originated in the EU in 2003 as a restriction on hazardous substances in specified categories of electronics and electronic products. Other countries have passed laws styled after RoHS, but only the EU RoHS is addressed here. Unlike some environmental laws, RoHS is not only focused on the safety of products during their life cycle of consumer use, but is designed to keep restricted substances out of landfills and recycling centers.

The original RoHS restricted the use of lead, cadmium, mercury, hexavalent chromium, PBB and PBDE. RoHS now restricts the use of a total of ten substances after the EU added four types of phthalates to its restricted substance list. Compliance with RoHS became a requirement for the use of the CE mark in 2011, and replaced a RoHS compliant mark on restricted products.

RoHS specified categories for regulation include large household appliances, small household appliances, computer equipment, lighting, power tools, toys, certain medical devices, control equipment (smoke alarms, thermostats and their industrial equivalents), and ATM machines. Newly added Category 11, the “catch all” category, includes all other electronic and electrical equipment not covered in the previous categories, including electronic nicotine delivery systems, cannabis vaporizers and vape pens.

RoHS Lead Exemptions Complicate Compliance

RoHS provides numerous exceptions to its strict 1000ppm lead standard that are slated to expire in phases from 2021 through 2024. Most Category 11 exceptions will not expire until 2024. For example, RoHS permits different levels of lead for lead in glass and ceramics, lead in high temperature solders, and lead in copper and aluminum alloys. So, an e-cigarette may contain some parts that are held to the highest level of lead restriction, it may but contain isolated components that (at least through 2024) are held to more permissive standards. While this leeway may reduce manufacturing costs for certain components, it creates greater complexity in testing. Anecdotal reports suggest that especially for products that compete heavily on price, sourcing from lesser-known Chinese foundries has resulted in unpredictable lead levels.

Take Away Points

As vape and e-cigarette companies compete with new features and design elements each year, and companies rely on new manufacturers, keeping up with regulations has proven to be difficult for both U.S. and for EU regulated products. For example, a company has to comply with numerous regulations regarding the oil or concentrate that will ultimately be inhaled by a consumer, and with regulations like RoHS that regulate parts a consumer may never touch or see. Each year, some company comes out with a new set of electronic features that may interact with newly formulated oils or concentrates, other companies compete for features or price points, making these products a moving target when it comes to testing.

Adding lead to many metals makes them easier to work with and therefore cheaper. Anecdotal reports suggest that especially for products that compete heavily on price, sourcing from lesser-known Chinese foundries has resulted in unpredictable lead levels. This can be the result of any number of causes: changes in sub-contractors, uses of industrial equipment for other products that permit higher lead content, or simply unscrupulous management that is willing to risk a contract to save money manufacturing a batch of components. There is speculation that some lead may leach into oil or concentrates in e-cigarette and vape products from the contact between the oil or concentrate and internal heating elements in certain type of products. RoHS compliance with regard to lead levels may reduce the chance of inadvertent lead contamination by such means, and compliance may therefore yield benefits on several regulatory fronts.

Compliance with RoHS for each part of an e-cigarette or vape therefore requires knowing your supplier for each component, but given increased regulation of these products (both the hardware and consumable elements) this can only help compliance with regulations in every relevant jurisdiction.
The Need for Standardization in Medical Cannabis Testing

By Andrew James
2 Comments

There has been a move towards the legalization of cannabis for medical and/or recreational use across many countries and US states in recent years, leading to greater demand for accurate potency and safety testing. Despite this, there are currently no standardized regulations between states or countries for quality control including content, composition, adulterants, potency or levels of toxic residues. As such, in many cases where regulations are in place, testing is generally carried out at a small number of approved independent testing laboratories.

The need for self-regulation has led to the growth of portable gas chromatography (GC) being used in the field of cannabis testing.This lack of clarity makes it difficult for consumers to make informed decisions about what they are purchasing, an issue which could be damaging to the industry’s changing reputation. As it stands, producers of cannabis and cannabis-derived products can supply goods with potentially harmful contaminants such as fungi or pesticide residues, which are potentially threatening to human health. Most cannabis products sold legally in the US are required to be tested and labelled for THC, the chemical responsible for most of cannabis’s psychoactive effects. A US study found that as few as 20% of recreational cannabis products are accurately labelled with only 17% of products reviewed accurately labelled for THC content (i.e. within 10% of the labeled value). It also found 23% were under labelled, and 60% were over labelled.

If cannabis were to be categorized as a regulated pharmaceutical drug, it would be rigorously tested to comply with stringent rules and regulations regarding quality and safety of the product, as are all other drugs. However, as there is currently no centralized regulatory body that oversees this, the responsibility of quality assurance falls to the grower, manufacturer and sometimes the consumer.

The Need for Cannabis Analysis

The most common requirement when testing cannabis is positive identification and quantification of the total THC:CBD ratio. In a highly competitive marketplace, this information is important, as cannabis consumers tend to equate THC levels with price. In many instances, lower THC products are cheaper and higher THC concentrations make products more expensive. Without robust systems in place for sufficient testing, this information cannot be accurately determined, meaning the customer often cannot make an informed decision.

Pesticide use is surprisingly common in the cannabis cultivation industry

In addition to potency testing, one of the core issues facing the industry and by extension, the end consumer, is the prevalence of pesticides in cannabis products. In the Netherlands, the Ministry of Environment and Health reported that over 90% of cannabis plants tested had pesticides on them. While steps have been taken to tackle this, the lack of cohesion in testing standards combined with the onus on individual labs to carry out testing, has led to some issues within the industry.

Many individual retailers in the U.S. and internationally are self-testing for impurities such as pesticides, heavy metals and microbials. While there is a clear need for standard testing across all locations, the need for self-regulation at present has led to the growth of portable gas chromatography (GC) being used in the field of cannabis testing.

Using GC as an analytical tool 

With the increased need for quality control and quality assurance in the largely unregulated cannabis industry, technology is now more accessible to smaller companies and to people with minimal laboratory experience. There are a range of cannabis testing packages available for smaller individual labs which offer more mobile testing with affordable packages. The lower entry price makes GC analysis affordable for more laboratories while still delivering reliable, high quality results.

Portable GC instruments can offer high quality potency testing, pesticide screening, terpene and flavor profiling, and residual solvents analysis. These instruments can give growers and processors an accurate result of cannabinoid percentages, a fundamental piece of information for growers and dispensaries. Systems can be configured for manual injection or a range of autosampler options can be added.

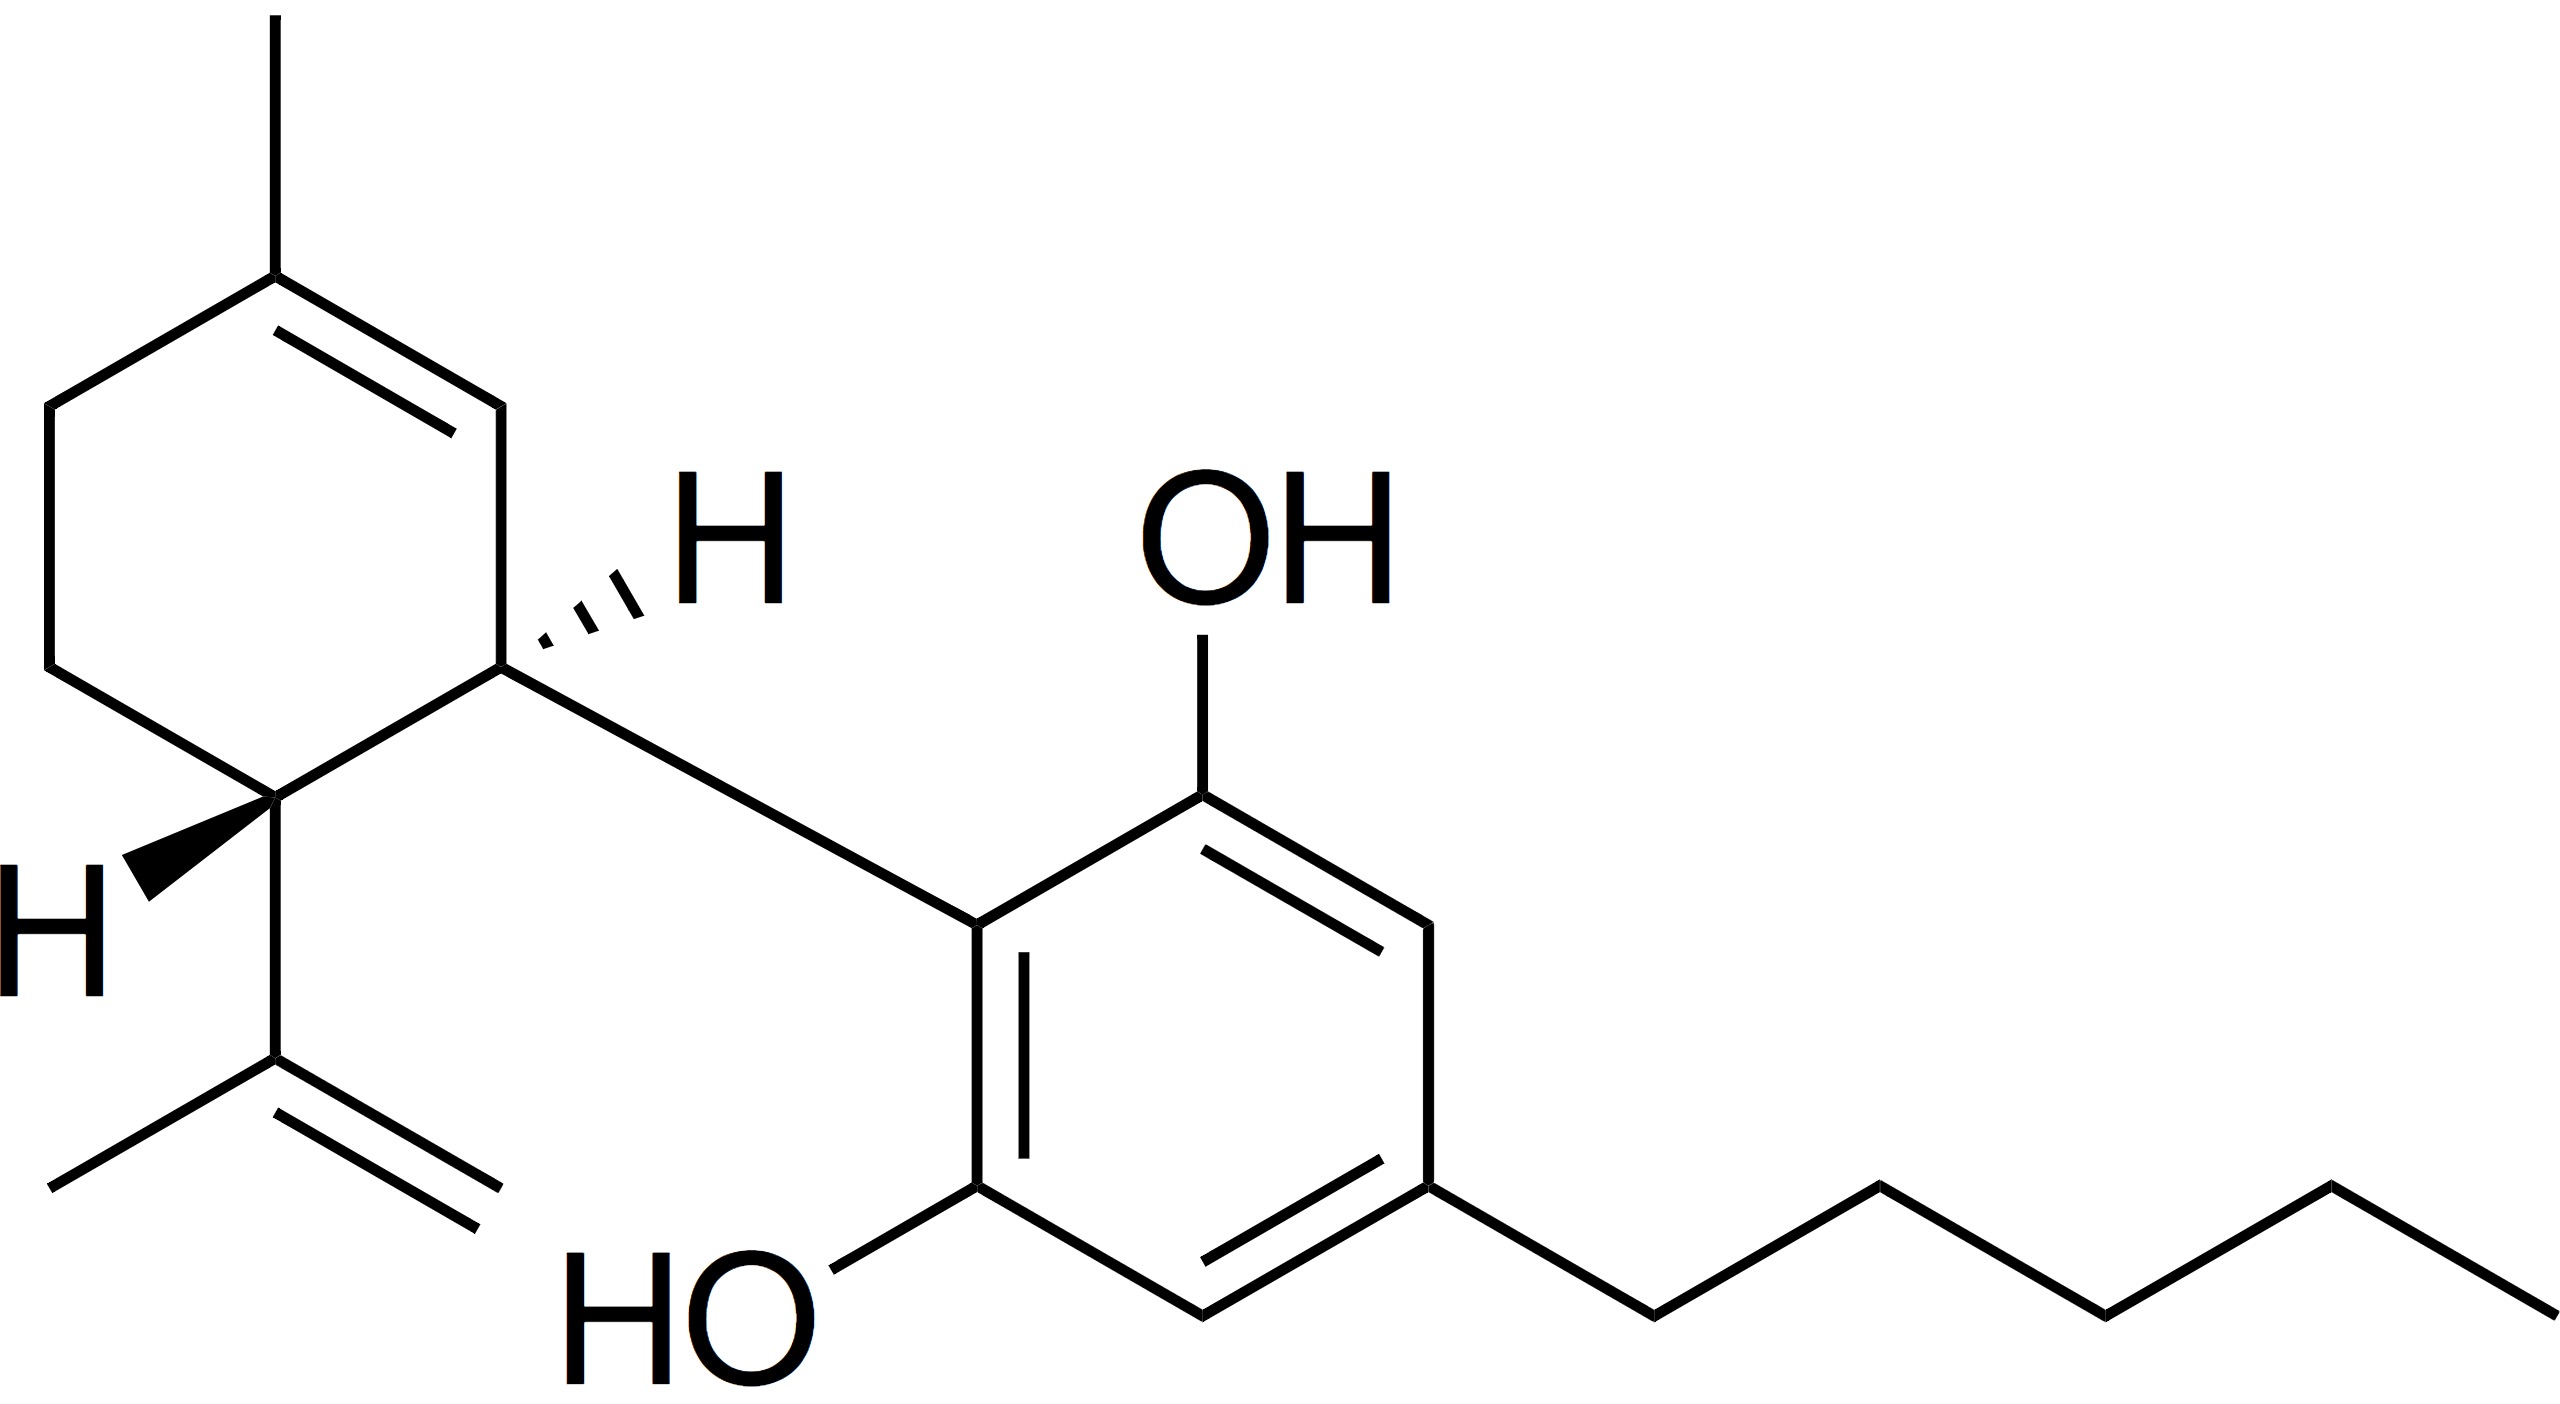
The structure of cannabidiol (CBD), one of 400 active compounds found in cannabis.

GC enables the rapid and accurate identification and quantification of the THC:CBD ratio. This is important for companies which are carrying out self-testing as it allows their customers to have assurances in the short term over the quality of their product, as well as reducing any potential risks to public health.

An example of this in practice is the use of GC by Dutch company Shamanics which carries out testing service for coffee shops in the Netherlands. The company conducts terpene analysis and potency testing to assure the quality of the products it supplies, with a portable GC, which offers the flexibility required without any established guidelines on testing in place.

When testing for potency using the GC, they look for total THC and CBD by converting the acidified versions of the cannabinoids into neutral forms within the heat of the GC injector. The process has flexibility which means that if they need to see both the acidified and neutral versions, they can do this by derivatizing the sample. The accuracy of this process is crucial to Shamanics and similar companies within the industry so that they can accurately judge the quality of a product, and relay this information to retailers and consumers.

The future of GC in standardized testing

While the growing availability of portable GC instruments and the increasing sophistication of individual labs means more companies are able to self-test products, there is still a significant hurdle to overcome in terms of standardising and regulating both the medical and recreational cannabis markets. Where regulation is brought in it should be consistent across states and countries and most importantly, it should be monitored and enforced. In the meantime, responsible producers are using the technology available to them to provide consumers with guarantees that their cannabis products are safe and of a high quality.

HACCP

Implementing a HACCP Plan to Address Audit Concerns in the Infused Market

By Daniel Erickson
1 Comment
HACCP

The increasing appeal and public acceptance of medical and recreational cannabis has increased the focus on the possible food safety hazards of cannabis-infused products. Foodborne illnesses from edible consumption have become more commonplace, causing auditors to focus on the various stages of the supply chain to ensure that companies are identifying and mitigating risks throughout their operations. Hazard Analysis and Critical Control Points (HACCP) plans developed and monitored within a cannabis ERP software solution play an essential role in reducing common hazards in a market currently lacking federal regulation.

What are cannabis-infused products?

Cannabis infusions come in a variety of forms including edibles (food and beverages), tinctures (drops applied in the mouth), sprays (applied under the tongue), powders (dissolved into liquids) and inhalers. Manufacturing of these products resembles farm-to-fork manufacturing processes common in the food and beverage industry, in which best practices for compliance with food safety regulations have been established. Anticipated regulations in the seed-to-sale marketplace and consumer expectations are driving cannabis infused product manufacturers to adopt safety initiatives to address audit concerns.

What are auditors targeting in the cannabis space?

The cannabis auditing landscape encompasses several areas of focus to ensure companies have standard operating procedures (SOP’s) in place. These areas include:

  • Regulatory compliance – meeting state and local jurisdictional requirements
  • Storage and product release – identifying, storing and securing products properly
  • Seed-to-sale traceability –  lot numbers and plant identifiers
  • Product development – including risk analysis and release
  • Accurate labeling –  allergen statements and potency
  • Product sampling – pathogenic indicator and heavy metal testing
  • Water and air quality –  accounting for residual solvents, yeasts and mold
  • Pest control – pesticides and contamination

In addition, auditors commonly access the reliability of suppliers, quality of ingredients, sanitary handling of materials, cleanliness of facilities, product testing and cross-contamination concerns in the food and beverage industry, making these also important in cannabis manufacturers’ safety plans.

How a HACCP plan can help

HACCPWhether you are cultivating, harvesting, extracting or infusing cannabis into edible products, it is important to engage in proactive measures in hazard management, which include a HACCP plan developed by a company’s safety team. A HACCP plan provides effective procedures that protect consumers from hazards inherent in the production and distribution of cannabis-infused products – including biological, chemical and physical dangers. With the lack of federal regulation in the marketplace, it is recommended that companies adopt these best practices to reduce the severity and likelihood of compromised food safety.

Automating processes and documenting critical control points within an ERP solution prevents hazards before food safety is compromised. Parameters determined within the ERP system are utilized for identification of potential hazards before further contamination can occur. Applying best practices historically used by food and beverage manufacturers provides an enhanced level of food safety protocols to ensure quality, consistency and safety of consumables.

Hazards of cannabis products by life-cycle and production stage

Since the identification of hazards is the first step in HACCP plan development, it is important to identify potential issues at each stage. For cannabis-infused products, these include cultivation, harvesting, extraction and edibles production. Auditors expect detailed documentation of HACCP steps taken to mitigate hazards through the entire seed-to-sale process, taking into account transactions of cannabis co-products and finished goods at any stage.

Cultivation– In this stage, pesticides, pest contamination and heavy metals are of concern and should be adequately addressed. Listeria, E. coli, Salmonella and other bacteria can also be introduced during the grow cycle requiring that pathogenic indicator testing be conducted to ensure a bacteria-free environment.

Harvesting– Yeast and mold (aflatoxins) are possible during the drying and curing processes. Due to the fact that a minimal amount of moisture is optimal for prevention, testing for water activity is essential during harvesting.

Extraction – Residual solvents such as butane and ethanol are hazards to be addressed during extraction, as they are byproducts of the process and can be harmful. Each state has different allowable limits and effective testing is a necessity to prevent consumer exposure to dangerous chemical residues.

Edibles– Hazards in cannabis-infused manufacturing are similar to other food and beverage products and should be treated as such. A risk assessment should be completed for every ingredient (i.e. flour, eggs, etc.), with inherent hazards or allergens identified and a plan for addressing approved supplier lists, obtaining quality ingredients, sanitary handling of materials and cross-contamination.

GMPFollowing and documenting the HACCP plan through all of the stages is essential, including a sampling testing plan that represents the beginning, middle and end of each cannabis infused product. As the last and most important step before products are introduced to the market, finished goods testing is conducted to ensure goods are safe for consumption. All information is recorded efficiently within a streamlined ERP solution that provides real-time data to stakeholders across the organization.

Besides hazards that are specific to each stage in the manufacturing of cannabis-infused products, there are recurring common procedures throughout the seed-to-sale process that can be addressed using current Good Manufacturing Practices (cGMP’s).  cGMPs provide preventative measures for clean work environments, training, establishing SOPs, detecting product deviations and maintaining reliable testing. Ensuring that employees are knowledgeable of potential hazards throughout the stages is essential.Lacking, inadequate or undocumented training in these areas are red flags for auditors who subscribe to the philosophy of “if it isn’t documented, it didn’t happen.” Training, re-training (if necessary) and documented information contained within cannabis ERP ensures that companies are audit-ready. 

Labeling

The importance of proper labeling in the cannabis space cannot be understated as it is a key issue related to product inconsistency in the marketplace. Similar to the food and beverage industry, accurate package labeling, including ingredient and allergen statements, should reflect the product’s contents. Adequate labeling to identify cannabis products and detailed dosing information is essential as unintentional ingestion is a reportable foodborne illness. Integrating an ERP solution with quality control checks and following best practices ensures product labeling remains compliant and transparent in the marketplace.

Due to the inherent hazards of cannabis-infused products, it’s necessary for savvy cannabis companies to employ the proper tools to keep their products and consumers safe. Utilizing an ERP solution that effectively manages HACCP plans meets auditing requirements and helps to keep cannabis operations one step ahead of the competition.

Soapbox

Cannabis Pioneers vs. Cannabis Innovators: Who Has the Advantage?

By Jeff Arbour
No Comments

In today’s innovation marketplace, everybody wants to be the first. Tech and non-tech companies alike are racing to raise capital for crypto, blockchain and AI, yet these sectors and technologies are still not even close to mass adoption.

Today’s entrepreneurs are obsessed with disruption. While this is obvious in the world of tech, it may soon be overshadowed by the nascent cannabis industry in the United States. Every time a new state opens an application submission period for a new cannabis dispensary, hundreds of companies apply. Each new market and state have pre-existing demand. Until recently, obtaining cannabis was difficult for many and illegal.

Often, the latecomers who learn from pioneers’ mistakes are the ones who earn the greatest successes.

Most of these companies apply in good faith, only to run into unforeseen problems as the regulatory landscape changes. This is part of the risk inherent to pioneering and disrupting industries. Often, the latecomers who learn from pioneers’ mistakes are the ones who earn the greatest successes.

The Difference Between Pioneering and Innovating

In the world of commerce, paving the way for a new product to hit the market is usually a thankless, time-consuming task. It exposes the weaknesses of the market’s operators and invites newcomers to disrupt the already unstable status quo.

Although household names like Levi’s and Wells Fargo owe their success to the California Gold Rush, historians pay relatively little attention to the hundreds of thousands of casualties the Gold Rush caused. Pioneers paved the way, and innovators – like Levi Strauss – profited from the result.

Similarly, when it comes to cars, Peugeot and Tatra are not household names like Ford and Honda. Henry Ford’s assembly line innovations and Honda’s unbeatable factory flexibility led to those younger companies becoming far more successful than their older counterparts.

Pioneers change the way an industry operates. Airbnb did not succeed because it offered superior service compared to the powerful and deep-pocketed hotel industry. It succeeded because it improved the model that HomeAway and VRBO launched years prior – and did so in a way that undermined the hotel’s typical strengths while capitalizing on their weaknesses.

Pioneering disruption is not equal to innovation, and the cannabis industry will follow the same course.

Although pioneering the creation of new business models is an admirable thing to do, it’s not for everyone. Airbnb has been fighting regulators since the very beginning. The company has been forced to pay fines and taxes that simply didn’t exist until Airbnb’s business model came into being.

Uber’s regulatory troubles regularly make headlines around the world. Although it successfully disrupts every market it enters, established taxi companies and newcomers like Taxify often get the last laugh when they implement Uber-like functionality into existing business models. Uber found it too difficult to compete in China and sold its business to local newcomer Didi Chuxing.

All of these cases demonstrate that being the first or early to introduce a business concept comes with many challenges. Pioneering disruption is not equal to innovation, and the cannabis industry will follow the same course.

Cannabis Industry Pioneers vs. Innovators

In the cannabis industry, being the first often meant living in constant fear of being arrested. During the early years of medical cannabis legislation, it was unclear whether federal authorities would raid and prosecute cannabis cultivators and dispensaries.

Every new cannabis market offers important, expensive lessons to future cannabis entrepreneurs:

  • California changed its cannabis product packaging laws several times before its market went live.
  • Oregon’s lack of state inspectors led to a laboratory testing bottleneck and an upsurge in black market cannabis diversion that the state’s last audit called “currently unstoppable.”
  • The two largest medical marijuana cultivation facilities in Illinois cost about $40 million to build, yet they compete over a market of less than $10 million.
  • Major pioneers like Medmen have paid enormous sums of money to gain entrance into regulatory environments they can’t accurately predict profits from.

Newer cannabis industry entrepreneurs are taking notice of all these obstacles and implementing plans to overcome them. It’s likely that the next generation of medical and recreational dispensaries will have far greater success than today’s biggest names, primarily due to this fact.

Consider the fact that all three of the S&P’s biggest cannabis industry companies have valuations far in excess of their actual sales. It is possible that these large, deep-pocketed organizations will generate enough revenue to justify their valuations, but in the meantime, newer players will enter the picture with greater responsiveness and startup efficiency.

Newcomers to the cannabis industry are setting themselves up for success with highly targeted business objectives, strong executive teams and high-impact advisors. They are navigating the regulatory landscape with more agility than early cannabis pioneers can muster, obtaining lower price-to-sales ratios in the process.

Cannabis entrepreneurs need to be creative in their assessment of the opportunities these new environments create.

This is the hallmark of innovation. While disruptions and inventions typically take the form of new products or services, innovations expand marketplaces and lay the groundwork for new interactions between economic actors in those marketplaces.

What Tomorrow’s Cannabis Innovators Can Do Now

States like Pennsylvania, New York, and New Jersey are currently leaning towards recreational marijuana legislation like those currently in place in Colorado and California. Cannabis entrepreneurs need to be creative in their assessment of the opportunities these new environments create.

Opening a cannabis company is no small task. As regulators gradually come to agree on the requirements each state will ask its business owners to meet, the next generation of pioneering cannabis entrepreneurs will have to adapt. At the same time, a relatively small contingent of innovators – the new generation of Levi Strauss’s – will coincide to provide much-needed products and services to the incoming rush.

These innovators will not be limited to one side of the industry. Innovation thrives on integration, and tomorrow’s cannabis entrepreneurs are going to develop streamlined solutions for tackling today’s inefficiencies in ways that simply are not possible right now. These lean, sophisticated startups will use that path paved by the first generation of cannabis industry incumbents.

Cannabis innovators will need to develop solutions for minimizing the costs and complications of setting up companies in highly regulated environments. This can mean anything from developing superior seed-to-sale tracking POS integrations to building a more efficient supply chain and a path to the consumer.

With luck, the next generation of cannabis entrepreneurs will look to the past when informing their strategic decisions for the future.

european union states

Why International Trade Agreements Are Shaping The Cannabis Industry

By Marguerite Arnold
No Comments
european union states

If you have wondered over the past several years, why the big Canadian companies (in particular) are following the global strategy they are, there is actually a fairly simple answer: Newly implementing trade agreements, particularly between Europe and North America.

More specifically, they are highly technical trade agreements that are also called Mutual Recognition Agreements, (or MRAs).

In fact, look at the schedule of the MRA agreements signed between the U.S. and individual EU countries over the last several years, and it also looks like a map of the countries that have not only legalized at least medical cannabis, but where the big Canadian companies (in particular) have begun to establish operations outside of their home country.

But what is going on is actually more than just CETA-related and also will affect cannabis firms south of the Canadian-U.S. border.

All of these swirling currents are also why the most recent MRA to come into full force in July this year, between the U.S. and Europe, is so interesting from the cannabis perspective. Even before federal reform in the U.S. If this sounds like a confusing disconnect, read on.

What Are MRAs?

MRAs are actually a form of highly specialized trade agreement that allow trading countries to be certain that the pharmaceuticals they purchase from abroad are equivalent to what is produced at home. This includes not only ingredients but processing procedures, production plant hygiene, testing, labeling and more.

When it comes to the  EU-US MRA agreement, this means that individual states of the EU can now recognize the American Food and Drug Administration (or FDA) as an effective federal regulator of American pharmaceutical production that is equal to the procedures in Europe. US GMP standards, in other words, will be recognized as equal to those of EU states.

This will now also, by definition, include GMP-certified medical cannabis formulations.

What is so intriguing, however, is how this development will actually place certain American (and Canadian) manufacturers in a first place position to import cannabis into Europe ahead of the rest of the American cannabis industry.

What Are Mutual Recognition Agreements All About?

One of the most important quality and consumer safety aspects of establishing a clean supply chain is tied up in the concept of GMPs (Good Manufacturing Practices). These are procedures, established by compliant producers of pharmaceuticals, to ensure seed (or source) to sale reliability of the medication they make. In the cannabis industry, particularly in the advent of Canadian-European transatlantic trade in cannabis, this has been the first high hurdle to accept and integrate on the Canadian side.

GMPIf European countries recognize a country’s GMP certifications are equivalent to its own, in other words, and cannabis is legal for export, a country can enter the international cannabis market without facing bans, in-country inspections and the like. In the interim, imported products still have to be batch tested until the agreements are fully accepted and operational.

Israel, for example, already had an MRA with the EU, and medical cannabis is legal in the country. However, Israel was prevented from selling cannabis abroad until a legislative change domestically, passed on Christmas Day.

That is why the MRA agreement between the US and EU with Canadian companies in the middle also put both Israeli and U.S. firms at an extreme disadvantage in comparison. Both in entering the market in the first place, and of course associated discussions, like the German tender bid. That is now changing- and as of this year.

A Specialized Map Of Global Medical Cannabis Exporters

Ironically, what the new US-EU MRA could also well do is create a channel for pharmaceutical cannabis from the United States to Europe (certainly on the hemp and CBD front) just as Israel is expected to enter the international cannabis export industry (later this summer or fall). It could well be also, particularly given the Trump Administration’s tendency to want to not only “put America first” if not pull off “a better deal” in general and about everything, that this is why President Trump offered the delay to Israel’s president Benjamin Netanyahu in the first place.

Regardless of the international individual developments and subtleties however, what is very clear that from the time the first bid stalled in Germany in the summer of 2017 until now, the U.S.-EU MRA has been in the room even if not named specifically as a driver.

For example, the FDA confirmed the capability of Poland and Slovenia to carry out GMP inspections in February of 2019.  It was only last fall that Aurora pulled off its licensing news in the former (on the same day licensing reform was announced by the government). Denmark was recognized in November of last year during the first year of its “medical cannabis pilot progam.” Greece was recognized in March 2018. Italy, Malta, Spain and the UK came online in November of 2017.

Overlay this timetable with a map of cannabis reform (and beyond that, cannabis production) and the logic starts to look very clear.

The upshot, in other words, is that while cannabis still may be “stigmatized” if not still “illegal” in many parts of the world, more generalized, newly negotiated and implementing, specialized global trade agreements between the US, Europe and Canada in particular have been driving the development of certain segments of the cannabis industry globally and since about 2013.

The Biggest News?

As of this year, as a result, expect at least from the GMP-certified front at least, that such international trade will also include medical cannabis from the U.S.

Want an example of the same? First on that list if not early in the game will now undoubtedly be Canadian-based Canopy Growth, with Acreage on board, headquartered in New York.

Marguerite Arnold

Canopy Growth Makes Multi-Billion Dollar Conditional Acquisition Deal

By Marguerite Arnold
1 Comment
Marguerite Arnold

The first German cannabis bid may have come to an end more or less, and with a whimper rather than a bang (not to mention the inevitable still-to-be-settled legal challenges). However even as the dust settles, one of the biggest “names” in cannabis and the company formerly expected to win at least a few of the tender lots is looking elsewhere.

Namely Canopy Growth, which was a finalist in the first round of the tender, has not shown up as a finalist firm in Germany this time (at least not so far).

However, it is clear the firm has other intentions afoot, namely U.S. expansion.

In an unprecedented move, Canopy announced its intent to buy the largest U.S. based producer of cannabis, a firm called Acreage Holdings, just before Easter. The conditional deal is being consummated in both cash ($300 million) plus stock swaps, and will not finally close until federal reform has come in the U.S. In fact, the deal makes the bet that the entire issue of U.S. federal reform will be solved within the next decade.

Canopy_Growth_Corporation_logoIn the meantime, however, what this also does is place one of the world’s largest cannabis companies in the middle of what is largely seen as the world’s most valuable overall cannabis market. Further it does so in an environment where the company benefits from Acreage’s considerable market and political clout. Former speaker of the U.S. House of Representatives John Boehner (a fierce opponent of legalization until it was personally convenient and profitable) is on the board of Acreage.
But there are those who might still be confused about why this deal happened. Canopy after all is fond of saying that its first focus is the “more valuable” medical rather than recreational market. And the U.S. market has many challenges still, that stem from a lack of federal reform. In fact, Canopy has frequently said in the past that they would not enter the U.S. until federal reform occurs. What gives?

What The Deal Also Does…

It is not “just” entry into the U.S. recreational market, albeit still on a state level that is significant about the deal. That starts with its timing.

When trying to understand the motivations of Canadian cannabis companies, especially ones who have eschewed the U.S. market in the past (at least until federal reform passes), it is also necessary to understand that they operate in a shifting world of global strategy that is never as straightforward as one might think. And often has nothing to do with cannabis per se.

Namely, while this deal places Canopy in the middle of the U.S. state industry it also does something else. It positions Canopy as a U.S. producer just two months after a new international pharmaceutical trade deal went into force (on February 8) called an MRA.

MRA agreements, also known as Mutual Recognition Agreements, are essentially trade deals between countries to accept the equivalency of their pharmaceutical production and supply chain.

On the cannabis front, the existence of MRAs between existing countries as cannabis has become legal, has also largely dictated the new international cannabis trade (see Canada and Germany as a perfect example) although this has been held as a closely held secret by the largest cannabis company executives (some of whom have previously denied that this was driving their expansion across Europe).

However, thanks to the agreement on this MRA in February, as of July of this year, Europe and the U.S. will formally kick off a situation where the European and therefore German health authorities will formally recognize American GMP processes.

That means that on the pharma front, Canopy has also essentially re-entered the European market, albeit by a bit of a backdoor. It also means that Canopy can immediately start to import cannabis drugs at least, made in the U.S. into the European and by extension, German market.

Cannabis drugs have been going in the opposite direction across the Atlantic to the U.S. for at least a year now (see the GW Pharma’s Epidiolex adventure last year). And further over the U.S.-Canadian border if now only bound for academic research (see Tilray).

It also may mean that they can import medical cannabis itself to be used as “medicine” or processed into one in Europe.

Does This Mean That U.S. Federal Reform Is Imminent?

Not necessarily. In fact, keeping the U.S. market in general out of the global cannabis trade, while allowing the top companies to participate both in the cross-state market and the global pharmaceutical one benefits the biggest companies. Conveniently, this also allows U.S. cannabis “pharmaceutical” producers to enter the EU in force just as Israel is expected to (third quarter this year). This also puts the “deal” U.S. President Trump and Israeli President Netanyahu cut on the subject to delay Israeli sales in an entirely new light (and one that should outrage both Americans and Israelis in the industry on this front even more). Not to mention every European hopeful producer unaware of the larger game afoot.

That said, what federal U.S. legalization will do is drop the operating costs of the larger U.S. entities now engaged in multi-state operations.

Cannabis in other words is not likely to be legalized in the U.S. before the next presidential elections for reasons that have everything to do with the profits of a few – and for that reason will certainly be a major theme in the next national political race.

And in the meantime, the biggest companies, Canopy included, are not only laughing all the way to the bank (although their shareholders are another story), but setting themselves up to be at the ground floor DNA of the global cannabis business as it establishes itself in every country of the world.

Introducing the Cannabis Quality Conference & Expo

By Aaron G. Biros
1 Comment

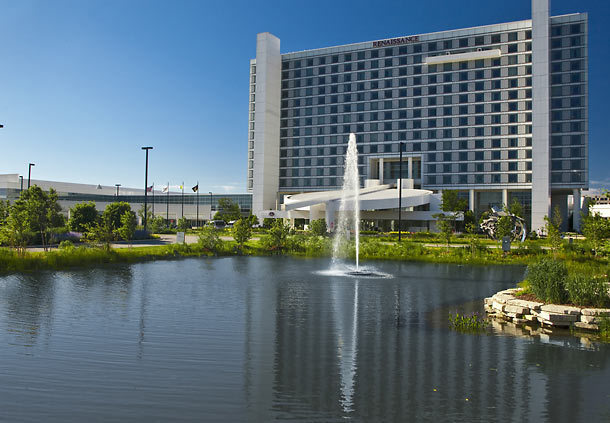
An educational and networking event for cannabis safety and quality solutions: Innovative Publishing and Cannabis Industry Journal are pleased to present the first annual Cannabis Quality Conference & Expo (CQC). The conference will take place October 1-3, 2019, hosted at the Renaissance Schaumburg Convention Center in Schaumburg, Illinois.

The inaugural CQC will consist of two separate tracks: The Cannabis Labs track, focused on all things cannabis lab testing, and the Cannabis Quality track, focusing on quality in cannabis product manufacturing.

Sharing an exhibit hall and meeting spaces right alongside the Food Safety Consortium Conference & Expo, the CQC allows cannabis professionals to interact with senior level food quality and safety professionals, as well as regulators. Visit with exhibitors to learn about cutting-edge solutions, explore two high-level educational tracks for learning valuable industry trends, and network with industry executives to find solutions to improve quality, efficiency and cost effectiveness in a quickly evolving cannabis marketplace.

The CQC will be hosted at the Renaissance Schaumburg Convention Center in Illinois (just outside of Chicago)

With the cannabis industry in the Midwest growing at a rapid pace, the CQC offers attendees, exhibitors and sponsors unparalleled access to explore these emerging markets, their regulations, opportunities for business growth and best practices from the more established food industry.

For information on speaking opportunities and to submit an abstract, click here to view the Call for Proposals. The CQC will be accepting abstracts for consideration until June 3, 2019. For information on exhibiting, as well as additional sponsorship opportunities, contact RJ Palermo, Sales Director, rj@innovativepublishing.net, (203) 667-2212.

Take advantage of this chance to connect with cannabis industry and food safety professionals in the Greater Chicago Area. Don’t miss this opportunity to network with hundreds of industry stakeholders, get the latest on regulatory developments and see the newest technology disrupting the cannabis space.

german flag

German Cultivation Bid Appears To Have Three Finalists

By Marguerite Arnold
No Comments
german flag

The Frankfurt-based newspaper Handelsblatt Zeitung is reporting that three Canadian firms (actually two Canadians and a German start-up cofounded by another Canadian company) have now been selected as the first cannabis cultivation bid finalists, however insiders on the ground say that this is not necessarily a final decision.

A Berlin-based subsidiary of Wayland in Germany called Demecan, along with Aphria and Aurora have all been named as bid finalists pending a normal review period.

However, there are other complications still looming. This is far from over.

The first issuance of the bid in 2017 went down in court over a technical fault on the part of the issuing agency. The current iteration was posted last summer and saw its application moved several times because of further legal challenges.

As Peter Homburg, partner and head of the European Cannabis Group at Dentons said when contacted by Cannabis Industry Journal, “This is of course not an official announcement. I have a tendency to believe that others involved in the tender process historically may well challenge this decision.”

BfArM, the federal German agency in charge of the cannabis cultivation tender process, did not respond to a request for a comment as of press time.

The Decision Is Far From Over

Here are the basic challenges still ahead:

There is a lawsuit pending against the bid itself from applicants that has yet to be decided. The Klage (formal hearing in court) is due next week. If that does not derail the process, here are the next considerations.

While all three firms named in the bid have international reputations, there are some pending questions.

Wayland is far ahead of the other two firms in terms of production capability in the country. Their facility in eastern Germany has just been certified GMP standard – which means they are qualified to produce the quality of flower required for medical consumption. This news is also far from a surprise.

As Ben Ward, CEO of Wayland Group, commented when contacted by CIJ for a response via email: “At Wayland, we believe in meaningful partnerships, investing in Germany from day one, demonstrating a long-term commitment to the market,” says Ward. “Wayland GmbH is a German company, operated by Germans, existing in Dresden and Munich and is committed to this market. The companies awarded lots received the allocation based on a rigorous application process, not media sensation.”

Of all the Canadian firms, in fact, despite its lack of high-flying stock price, Wayland has made the most concerted effort to show its commitment to producing in Germany by a large investment of capital and expertise. Further, the firm has shown itself to be the most culturally sensitive to German culture, including hiring a female member to the board (a hot topic far from the cannabis industry). However, there are other issues looming. On the same day that Wayland issued a press release announcing its position in the bid, it also issued one announcing the merger talks with ICC had failed.

The second is that Aphria’s main cultivation center in Canada is not EU-GMP certified although they have applied for the same and now also own one of Germany’s largest distributors (with approximately a 6% market share).

Other firms not only kicked off the entire cannabis discussion in Germany, but have established GMP-compliant facilities both in Canada and across Europe, namely Canopy Growth, which was widely believed to have also applied to the second tender. However prevailing rumours about a Canadian “crop failure” in British Columbia (described by the company as a deliberate destruction of plants created by delays in the licensing process) last fall may have also played a role in the German decision.

Canopy_Growth_Corporation_logoAurora is also in interesting waters. Having distinguished itself as Canopy’s closest rival across Europe, winning significant kudos in Denmark, Italy, Poland and Luxembourg last year, the company is also clearly not “just” a medical cannabis company and apparently was refused an opportunity to go public on the Deutsche Börse last fall. The selection of the firm by BfArm for the bid in a situation where the company is on a watch list created by the stock market regulatory agency in Frankfurt is also an intriguing one. Especially given the company’s announcement of its Polish success on the same day as the decision to import was announced, and the fact that so far it is the only Canadian cannabis company to successfully import to Luxembourg.

And The Import Game Is Just Getting Hot…

The unsurprising news that the bid appears to be moving forward is actually not the hottest news in Europe right now. The reality on the ground is already shifting. Several weeks ago, a Frankfurt-based distribution start-up announced that they had successfully imported cannabis into the country from Macedonian-based Nysk Holdings via Poland.

At the International Cannabis Business Conference (ICBC) in Berlin last weekend, Australian producers (for one) were also reporting a German demand for their product that was greater than they could fill. And there were many Israelis present for what is expected to be an official opening of their import ability by the third quarter of this year.

Price Wars Are Looming

The bid itself is going to have a powerful impact on pricing in both the German and European market beyond that. It represents the first time in any country that a government has attempted to pre-negotiate prices for the drug as a narcotic beyond Israel and in this case, it will have at least regional implications.

aurora logoAt the same time, it is also clear that producers like Nysk and beyond them, Israeli and Australian firms (in particular) are actively finding ways to have their product enter the country- and further at prices that are catching the Canadians on the hop. Indeed Aurora is reporting that it actually lowered its “usual” prices to win European contracts which have been reported as being 3.2 euros a gram in Italy and 2.5 euros a gram in Luxembourg.

To put this in perspective, this is a range of about CA$3-5 a gram of flower which is also well below what Canopy (for one) has reported selling its product even to recreational users in Canada and significantly below medical export prices as reported by recent company corporate reports.

Wayland in contrast, is reporting that its production price in Germany will be at least a euro-per-gram cheaper than this. Or in other words, more in line with prices expected to be generated from both the bid itself and the cannabis now entering the country from other sources.

And of course, this is only the first of what is expected to be a series of new tenders. The original amount, itself increased in the two years the issue has been pending, is clearly not enough to even begin to meet demand as proved by the levels of competitively priced imports now entering the country.

Beyond questions about whether this time the tender will actually stand, are those now pending about new ones potentially in the offing – and not just in Germany but across Europe as cannabis continues to see a very green spring.

Marguerite Arnold

Farmako Inks Deal To Import 50 Tonnes of Polish Cannabis Into Germany

By Marguerite Arnold
No Comments
Marguerite Arnold

The ex-im cannabis map of Europe has been promising to get interesting for some time. And in March, it’s long promised potential just bloomed a little more as Frankfurt-based Farmako announced a first-of-its kind import deal of 50 tonnes of medical cannabis (and from Poland no less) over the next four years.

Farmako was just founded in September 2018. They began distribution to German pharmacies this month. They also have an office in London and cross-European aspirations.

While Farmako is the first to announce such a unique cross-border production and distribution agreement, however, they are far from the only ones planning the same. In fact at least Tilray is expected to announce that their newly-minted Portuguese crop is being processed into oil bound for German pharmacies any day now. It is also not unrealistic to expect that (at least) Canopy Growth, of the big Canadian producers at least, will soon announce the same situation for their crops in countries across the continent, starting with Spain.

Outside Germany of course, this kind of entrepreneurial endeavour is already underway. In the UK, a new import group just announced the first bulk shipment of Dutch medical cannabis into the country, distributed directly to over 1,000 pharmacies nationwide.

There still are a couple of jaw-dropping things to consider about this new German development. Namely, that the amount of just this deal over the next four years between two (relatively new, non-Canadian) companies is approximately five times the amount currently called for in the still pending domestic cultivation bid in Germany.

The second, of course, is that the Polish company on the other side of the border and this ex-im deal, PharmaCann Polska, is a uniquely positioned conglomeration of individuals with apparently Canadian and Israeli market experience. This means that they are already positioned to access the biggest two production markets in the world and are certain to be looking to exploit other Eastern European connections (at minimum). If not ones further afield than that.

One thing is absolutely certain far beyond the particulars of this one deal. The current import limitations from Canada and the Netherlands into the German market appear to be a thing of the past. And the cross-border trade for medical cannabis is now clearly entering a new phase.

Implications

Farmako clearly intends to go after the existing Canadians in the market on price, which means both Canopy Growth and Tilray. But it also means Wayland, at this point is the largest domestic certified producer (albeit with Canadian roots and partners) and an entire licensed facility in eastern Germany ready to go. That is not an insignificant threat and sets up another looming question: Which will actually be cheaper in the long run? Domestically grown German cannabis, or that imported from adjacent countries with lower paying labor markets?

This announcement also means that the “cannabis shortage” in the country is officially over as of this spring. And that won’t just come from Farmako but others already in the market and those angling now to get in via other creative means.

Regardless, what that will do to overall sales, patient numbers and overall speed is another matter.

Other Looming Problems

There are two big issues that this development does not solve of course. The first is the ability of patients to find doctors willing to prescribe the drug, and further to make sure they spend the time filling out the paperwork and negotiating with the patient’s insurer, to make sure that patients can actually get it. Starting with affording medical cannabis in the first place. Most patients on what is known as “statutory” health insurance (90% of the country) cannot afford the out of pocket cost at pharmacies without insurance approvals. Once they get them, they pay up to $12 for a month’s supply (in the case of flower, about an ounce).

german flag
Photo: Ian McWilliams, Flickr

The second issue is that it is currently unclear, mostly due to the lack of granularity provided by the country’s statutory health insurers, what is actually being prescribed for which kind of condition and to whom. Earlier this month, new information was made available about the overall growth of coverage of medical cannabis in Germany. While the total spending, and rough breakdown of flowers vs. product was provided, it is unclear beyond that, where this is going. There were also apparently just over 46,000 patients in Germany as of December 2018. And this is a growth trend that while clearly on an upward trajectory for the last three quarters is slow and steady as she goes. The sudden uptick in the market seen in the second quarter of last year appears to be an anomaly.

Further, understanding market price points is also hard. Flos and prepared pharmaceuticals such as Sativex are highly expensive right now. In the case of the Canadian firms, their medical exports are being sold at about twice the price of their domestic recreational sales points. Look for this to change dramatically as real competition heats up across Europe (and from more distributors than just this Frankfurt upstart).

What the news in other words about Farmako really signifies is that the price barriers in the medical market are about to come down at the point of sale- and hopefully in the short term, patients will not have to rely on the approval of their insurance companies to be able to access the drug because they will be able to afford it themselves. No matter what happens with the bid. Although this too will also serve to lower prices.

The great medical normalization race for medical cannabis in Europe is now officially “on.” And that is good news not only for patients, but of course, the industry.

British Barristers Take On Cannabis “Novel Food” Regulation In Brussels

By Marguerite Arnold
No Comments

The first thing to understand about the significance of the British barristers now challenging the EU’s classification of hemp extracts as a novel food is that this is like jumping into the middle of an action adventure by coming in at the second act. In other words, you miss the introduction and the first couple of car chases.

That said, this action movie also features a cannabis-flavored plot. Those used to the maddening hair splitting now going on just about everywhere as the industry gains legitimacy, in other words, are familiar with the larger story line.

Here are the “CBD Cliff’s Notes.”

The structure of cannabidiol (CBD), one of 400 active compounds found in cannabis.

It is highly significant that a major British cannabis trade organization, the Cannabis Trades Association, hired a leading law firm in London to go sue the EU over its recent decision to lump all CBD extracts into the same “novel” distinction. Up until now, only CBD sourced from cannabis had fallen prey to this strange regulation. Thus, the lawsuit. No Brexit themes involved. Yet. Although that too will play a role in all of this.

What Is This Really About?

If those in the CBD business are honest with themselves, the real reason for this segmented part of the cannabis industry to even exist in the first place is the race, desire and need to actually be allowed to operate in relative regulatory peace. No matter what the battles are on the THC front. CBD has been seen as a result, pretty much since the beginning of the new age of legalization, as the “safer” political and market entry choice by those in regions such as U.S. southern states and the burgeoning, can’t-wait-to-be-off-to-the-races, market in Europe. See the new federal hemp legalization bill in the United States as Exhibit A.

However, in Europe this has run into more than a few problems since the Swiss put “low THC” or “Cannabis Lite” on the map more locally. Starting with the whole discussion about licensing in general. And then, even more confusingly, about what to actually classify the plant. Especially when it is used in food and cosmetics as opposed to “medicine.”

Specifically, where does the cannabis plant in general, let alone its individual components, really fall when it comes to regulated human consumption?

european union states
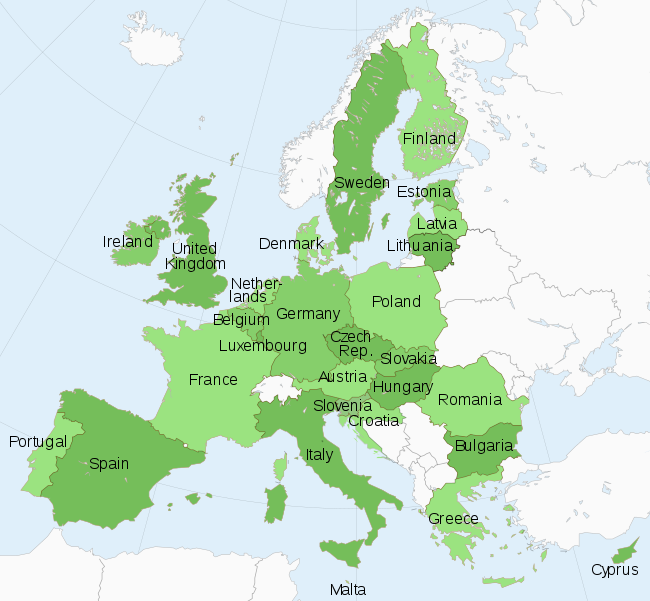
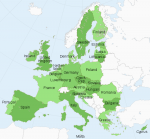
Member states of the European Union

For the time being- read last year when the industry in Spain was facing police busts over CBD cookies on the shelves at health stores- the conventional industry wisdom was that this whole furore was “just” over the use of concentrates, tinctures and other products made from cannabis-sourced CBD. However, given the noise that Austria managed to make over Christmas about the entire “licensing” issue (namely who has the right to produce, sell and package even CBD as a cannabinoid no matter where it is sourced), the EU also moved all CBD products and tinctures- even those made from good old hemp- into the novel food category.

This means in effect, that even CBD extracts produced from the hemp plant (which is actually the majority of such product in Europe) must now be regulated as a “novel food” too. Even though in poor old hemp’s case, it is certainly the case that health food nuts have been consuming the same in Europe long before (and certainly after) standing EU “novel food” regulations were put into place back in the late 90’s.

Thus, the lawsuit, launched from a country unsure of whether it will even be in the EU post-May (either the month or the current PM).

According to the EU at least for now, CBD itself is a “novel food” no matter from where it is sourced. And that, according to not only science but food history is an absolute fallacy.consumer safety, from factory to pharmacy or farm to table, is never far from the discussion

Likely Outcomes

Those who were hoping that CBD would remain unregulated in the EU should think again. It is highly likely that what will happen is that CBD production licensing is in the cards and just about everywhere. Think GMPs but with a consumer-food twist.

While indie producers might groan at the prospect of fees and licensing procedures, remember this is Europe. And consumer safety, from factory to pharmacy or farm to table, is never far from the discussion.

While this lawsuit, in other words, is likely to make the EU think more closely about regulating CBD in general, what is most likely to happen is that entire enchilada will be lumped under a regime to insure that high quality production, particularly of crops bound for consumption, is also extended to anything that ends up in either a food or cosmetic product.

CBD Producers Have To Keep Current On Regs

Given the current murkiness that exists, in other words at this point across Europe, in every country and for every CBD product, exports here from other places are still not a great idea.

There are labeling, licensing and of course, ultimately legislative issues that are all still in flux. And while the outcome of the lawsuit might eventually regulate and standardize things, the idea that a license-free CBD production industry is clearly now dead in the water.