Tag Archives: finance

Flower-Side Chats Part 6: A Q&A with Fabian Monaco, CEO of Gage Cannabis

By Aaron Green
No Comments

In this “Flower-Side Chats” series of articles, Green interviews integrated cannabis companies and flower brands that are bringing unique business models to the industry. Particular attention is focused on how these businesses integrate innovative practices in order to navigate a rapidly changing landscape of regulatory, supply chain and consumer demand.

The Michigan cannabis market is making pace with big time cannabis players like California (#1) and Colorado (#2). For the first quarter of 2021, combined cannabis sales in Michigan were nearly $360 million. At that pace, Michigan could see combined sales of $1.4 billion — well outpacing 2020 sales of $984 million.

Gage is the exclusive cultivator and retailer of world-leading cannabis brands including Cookies, Lemonnade, Runtz, Grandiflora, SLANG Worldwide, OG Raskal, and its own proprietary Gage brand portfolio in Michigan. The company recently secured a $50M investment in an oversubscribed round which included a $20M investment from JW Asset Management.

We spoke with Fabian Monaco, CEO of Gage Cannabis. Fabian started Gage in 2017 after meeting his operating partners in Michigan. Prior to Gage, Fabian worked as an investment banker racking up a number of firsts in cannabis industry financing and M&A transactions.

Aaron Green: Tell me how you got involved in the cannabis industry.

Fabian Monaco: My background is in investment banking – specifically 10 years of capital market experience. I was fortunate enough to be part of the initial team that brought Tweed, now Canopy Growth public. In fact, I worked on a lot of firsts in the industry: the first acquisition, the first $100 million financing, the first IPO in the space. Shortly after that, I went to XIB Financial, which co-founded Canopy Rivers with Canopy Growth. I was working on that when I encountered these two phenomenal operators. At the time, I had visited over 100 of these cultivation facilities and these were some of the best operators in the business. So that led me to start Gage in 2017.

Green: Where is Gage currently operating?

Fabian Monaco, CEO of Gage Cannabis

Monaco: In the U.S., we are purely operating in Michigan. We do have a licensing agreement with a small producer in Canada, so you will see the brand there.

Green: Tell me about your choice to settle the company in Michigan initially?

Monaco: If you look at Michigan as a historical cannabis market, it was the second largest cannabis market from a medical card holder standpoint for nearly a decade, only behind California. This was probably the case until 2019, where they went to adult use. So, for us, we knew this medical base was going to be a great platform to an outsized adult-use market. And already we see that April was $154 million in sales, adding up to over a $1.8 billion dollar run rate. That’s the third highest run rate in the country, only behind California and Colorado.

Green: What is it that makes Michigan different? You talked about medical cannabis already. Is there anything else about the demographics in Michigan or the consumer base that makes Michigan special in that sense?

Monaco: In Michigan, over 70% of the population is old enough to consume. So, when you take a look at how much of the population is 21-years-old plus, relative to other markets, the total addressable market in Michigan is just huge. Then when you take a look at their consumption habits, especially when it comes to flower, Michigan is consuming some of the highest amounts on a per capita basis. Those two stats set up a scenario where we foresaw the potential of the market. To be honest, the market has exceeded our expectations. We didn’t think it would be this strong this quickly. Right now, the state is looking to be a $3 billion market by 2024 – and it could easily surpass that.

Green: Any plans for expansion beyond Michigan?

Monaco: We’ve been to eight or so different states in the past 60 or 75 days really trying to educate ourselves on the licensing structure, the markets there and the key players in those respective markets. What are some of the costs, in terms of acquisitions? We really want to branch out the Gage brand into other states across the US. The thing is, we believe in the model that Trulieve deployed. They really focus on being the number one player in a very, very big market. For instance, Trulieve is obviously one of the top players in Florida. We’re trying to mimic that strategy.
Trulieve is a dominant market force in Florida

Once we have that deep market penetration, that market share, then we’ll start to get into other states. But for now, why would you want to go and rush out to another state when you’re already in the third largest market in the country?

Green: Are there any criteria you look for in a potential expansion state?

Monaco: We look at consumption habits. We want states with similar demographics to Michigan. Close proximity states also allows us to quickly go from one state to the other without having to take a multi-hour flight to get there. States we’re considering are Northeast and Midwest states, like Illinois, Pennsylvania, Ohio, New Jersey, Massachusetts and Maryland.

Green: What kind of consumer trends are you seeing in Michigan as it relates to products?

Monaco: Flower continues to dominate. In a market like Michigan, we have some of the top flower consumers in the country on a per capita basis. We specialize in flower and flower only, so this created a perfect scenario where we are able to ramp up our brand quite quickly, from a flower standpoint.

Now that we have that brand equity, that brand power, we are going to potentially delve into other categories, including extract-based products, such as vape carts and concentrates. You hear talk about these new beverages, but we’re not seeing that take off in this market as much as people think it would. Flower still remains at the top and that’s something we highly anticipate going after for quite some time.

Green: Can you tell me about your vertical integration strategy?

Monaco: We’re one of the larger retail portfolios in Michigan right now. We have 13 locations. Nine are operational. So, we’re really in a great spot overall in terms of how big of a platform we do have – one of the larger ones – and, frankly, in one of the larger markets in the country.
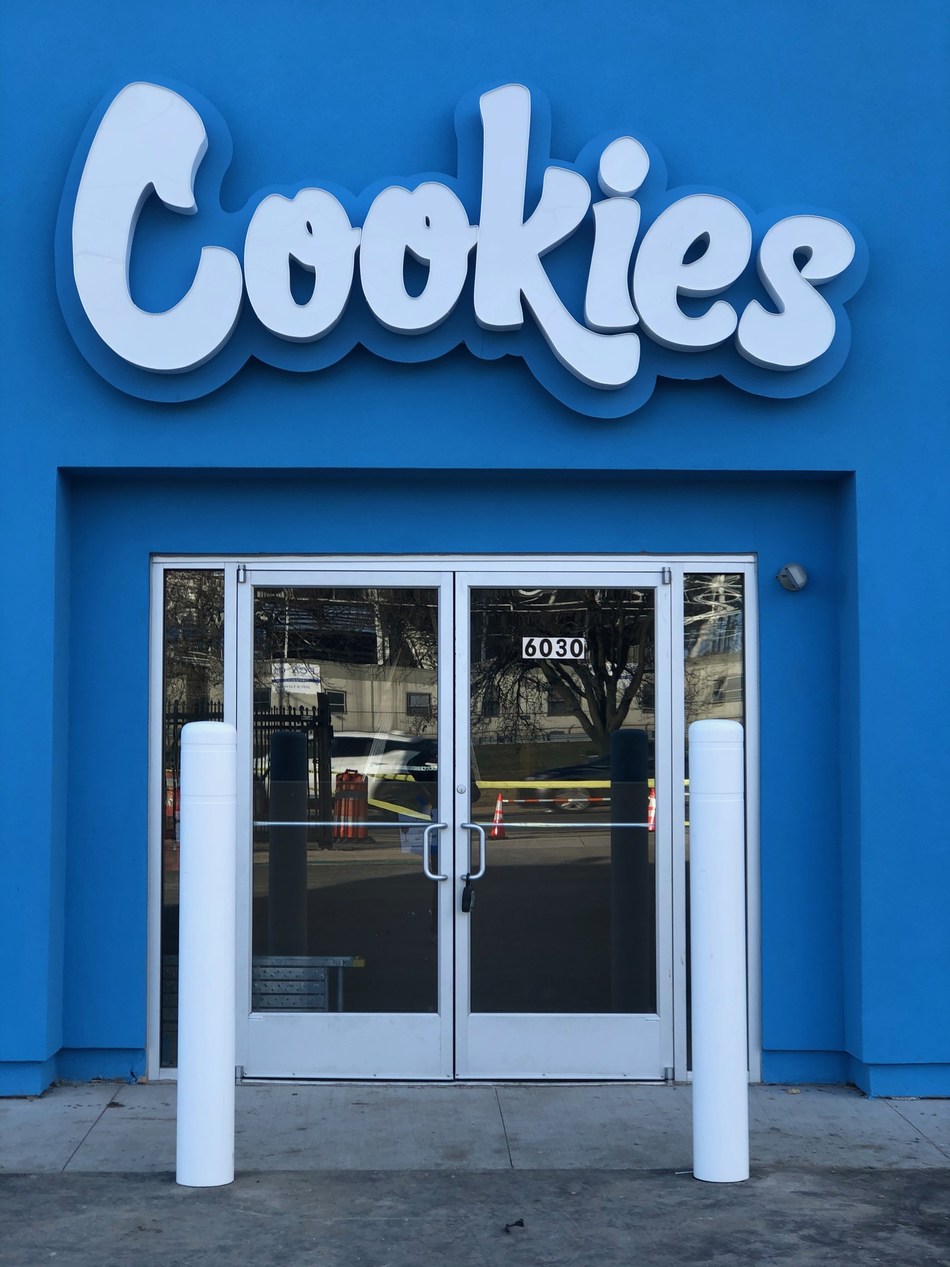
The Cookies flagship dispensary in Detroit, Michigan

We actually have a little bit of a unique scenario on the cultivation side of things. We have our own three cultivation assets that are going to be producing, on average, about 1,000 pounds of product over the next couple of months as they fully ramp up. We’ve actually contracted out a lot of our cultivation. Cultivation is time consuming, and it’s also very, very costly to build out. Luckily for us, we’re a really well-established and strong brand. We had the opportunity to contract out our growing. So, we have 10 different contract growth partners. These are phenomenal cultivators, again, some of the best in the state. They grow Gage and Cookies branded product for us. We have a great breakdown from a financial standpoint. We share the retail revenue with them on a 50/50 basis. They pay a little bit too, for packaging and testing. So, basically for $0 we’re getting product on the shelf where we’re achieving 50% plus gross margins. It’s a phenomenal setup for us on the cultivation side where we went from two cultivation assets in the latter half of last year to now eight different cultivation assets, moving to 13 by the end of the year.

On the processing side, we’re just actually finishing our processing lab. We should have extract-based products launched in Q3. We’re really excited to have our own line of extract-based products. We plan to focus on vape carts to start – a very popular category in Michigan on the retail side of things.

Green: Are those cultivations all indoor?

Monaco: Yes, we’re big proponents of indoor flower. It allows us to control the quality of our flavors and consistency in our strains when we grow indoors. From our consumers, there is a very strong demand for indoor grown high-premium, high-quality products.

Green: What sets Gage apart from other competitors in Michigan?

Monaco: I think focus. We just focused on our flower. We focus on our post-production process. We hang dry everything, we hand trim everything, and we hand package everything. That’s a little bit more time consuming. It’s a little more costly. But all that effort shows in the end product which is key.
A lot of people think you can grow great quality product, you cut it down, you dry it and put it in the pack and it’s going to be great. You really need a strong attention to detail, especially in a big consuming market like Michigan, because again, they are a refined consumer. They’re looking for the best. They’ve already been consuming some of the best quality products in the country for many years now. So for us, we put a painstaking process in place for flower production, not only from the growing standpoint, but also through the end of that post production process.

Ancillary to our cultivation process is also consistently providing new varieties of flavors on the flower side of things to the consumers. When you look at the successful brands in California, what makes them special is that they’re consistently pheno hunting, coming out with new flavors. This is similar to the wine industry where the best wineries come out with a new kind of grape or mix and consumers get excited, they rush out and buy half a dozen bottles or a dozen bottles.

It’s a very similar scenario in the cannabis industry. I hate when people say that cannabis is a commoditized industry. It’s so far from the truth. You look at brands like us or Cookies, Jungle Boyz and you can see their constant innovation, their constant drive. They are always bringing something new for the consumers to try. That’s what really sets apart the best brands.
Green: What’s got your attention in the cannabis industry? What are you interested in learning more about?

Monaco: I’m always intrigued with new ways of consuming. Across the U.S. and well-developed markets like California and Colorado, you see all these interesting new ways to consume the product. You’ve got patches, sublingual strips, etc. There are so many unique ways. I am currently seeing how they play out. Are they fads? Do people get excited about them initially, and then go back to their vape carts, pens and typically dried flower pre-rolls? I’m always trying to educate myself to see what’s on the market. What’s new? Who has a new drink? How does it hit? Are people excited about it?

Also, I am constantly learning about new brands that come out. There are so many new small brands that don’t necessarily have the scale or the capital to really expand, but are producing some of the best products in the country in a cool, unique form of packaging, etc..

Green: Alright, great. That concludes the interview!

Monaco: Thanks, Aaron.
Support Grows for Federal Cannabis Legislation with the SAFE and CLAIM Acts

By Jay Virdi
No Comments

Things are about to change for cannabis and cannabis-related businesses, as landmark legislation to reform federal cannabis banking and insurance laws is just around the corner with the SAFE and CLAIM Acts now making their way through Congress.

The Secure and Fair Enforcement (SAFE) Banking Act, which already passed in the House, would allow financial institutions to do business with cannabis companies without facing federal penalties. There are high expectations the proposal will make its way through the Senate and onto President Biden’s desk.

The Clarifying Law Around Insurance of Marijuana (CLAIM) Act was introduced in Congress in March and is in the first stage of the legislative process. If it passed, it would allow insurance companies to service cannabis businesses without the threat of federal penalties.

For years, fear of sanctions kept banks and credit unions from working with the cannabis industry, forcing cannabis businesses to operate on a cash basis which made them targets of crime and created complications for financial regulators. This is a significant first step for cannabis businesses toward conducting more legitimate and safe operations.

The SAFE Banking Act: Providing a Legitimate Avenue to Banking and Loans

With 37 states and D.C. having taken action to legalize cannabis in some way, it is clear the federal cannabis regulatory model has shifted and the path forward for the SAFE Banking Act shows promise.

The bill creates a safe harbor for banks and credit unions to the extent they would not be liable or subject to federal forfeiture action for providing financial services to a cannabis-related business.More competition means greater capacity and lower premiums for all. 

The bill would prohibit a federal banking regulator from:

  • Recommending, incentivizing or encouraging a depository institution not to offer financial services to an account holder affiliated with a cannabis-related business or prohibit or otherwise discouraging a depository institution from offering services to such a business
  • Terminating or limiting the deposit insurance or share insurance of a depository institution solely because the institution provides services to a cannabis-related business
  • Taking any adverse or corrective supervisory action on a loan made to a person solely because the person either owns such a business or owns real estate or equipment leased to such a business. 

The CLAIM Act: Backing Cannabis Businesses with the Right Insurance Coverage

Should the CLAIM Act pass, it will protect insurance companies that provide coverage to a state-sanctioned and regulated cannabis business. It would also prohibit the federal government from terminating an insurance policy issued to a cannabis business and protect employees of an insurer from liability due to backing a cannabis-related business.

The CLAIM Act will be a boost for the insurance market and drive more underwriters to write cannabis policies. More competition means greater capacity and lower premiums for all. The act would also have a notable impact on currently hard-to-source policies like Cyber coverage, Directors & Officers (D&O) insurance, Errors & Omissions (E&O) and other management liability policies that have been extremely limited to cannabis businesses.

Cannabis Sales Still Growing Strong Globally 

The cannabis market is not slowing down in the United States or globally. Recent forecasts have U.S. sales reaching $28 billion in 2022.

As was the case in Canada where cannabis was made federally legal in 2018, there’s going to be a steep learning curve industry-wide for financial services and insurance vendors who don’t yet understand the risks and liabilities of cannabis operations, even if the SAFE and CLAIM Acts pass this year. And yet this is one giant step in the right direction toward the safe and equitable sales of cannabis country-wide.

Five Things Every Cannabis Business Needs Before They Open

By Tim Allen
No Comments

When it comes to small business opportunities these days, few phrases give people the old dollar-sign-eyes more than “legal cannabis”.

From states like Michigan where it’s been approved for both medicinal and adult use, to places like South Carolina where legalization has been a popular topic for ballots and voters, cannabis is slowly turning into one of America’s biggest businesses.

You don’t need us to tell you that – Investopedia reports that (as of Nov. 2020) over 340,000 American jobs were devoted to the handling of plants at various stages along the retail cycle, and the industry was estimated at over $13 billion as of 2019.

Not bad for a plant that’s still technically illegal under federal law, huh?

If you’ve read this far, it probably means you’re hoping to be among the lucky ones who can strike it rich with their own cannabis business. A noble undertaking, but are you really prepared to make your mark? In a field as competitive – and occasionally complicated – as cannabis can be, you really need to lead with your best foot forward, and make sure you’re as well prepared for the various challenges of a fairly new industry as possible.

With that in mind, below is a list of the five things you’ll need to double-check and make sure you actually have access to before embarking on your new business venture.

The right shelving & equipment

You see this a lot with smaller businesses as well as, er, ‘independent growers’. A lot of people assume that they can just buy some greenhouse shelves, line the walls of their business with it, and call it a day, right?

Offering rare or unique cannabis strains is a great way to differentiate

This approach leads to problems more often than not. Even above and beyond the inherent concerns of helping your plants grow safely (and productively!), the sort of equipment you use should reflect the sort of business you’re trying to run. A cannabis retail outlet, for example, is going to need different sorts of shelves and tables than a dispensary or growing facility, as the work being done is completely different.

It will take a little research, but it helps that a lot of businesses these days are starting to offer shelving specifically designed for various cannabis operations. Check to see if any of the big warehouse suppliers near you have gotten into the cannabis game yet – Shelving Inc, Metro, and Rack & Shelf are a few of the bigger shelving names with cannabis offerings as of this writing.

Strong branding

Long gone are the days when all you needed to be successful in cannabis was a booth at the shady flea market, a pun name and a big sign that said “Head Shop” to throw off the authorities.

Far too many cannabis businesses launch themselves headlong into a business plan without stopping to think of a good name, or just settling for the first one they think of. With as crowded as the playing field is quickly becoming, it might honestly be worth it to pay someone to help you come up with a decent logo and branding – it’ll go a long way towards helping you stand out against everyone else using a green font. Places online like HIGHOPES specifically offer these services for cannabis businesses, so you know they’ll be able to figure out what you’re about more quickly.

An understanding of your consumer base

The exact sort of work your cannabis business performs is going to affect what your potential customer base can be – and vice versa.

Brands are embracing contemporary design more and more

Early on in the planning stages, make sure to figure out exactly who you’re going to sell your products to, as this will inform nearly every other decision your business makes. Do you want to sell directly to the customer, or to work as a distributor for CBD/cannabis retail outlets? Are you prepared to manage and run your own storefront, or are you just going to rent warehousing space to sell your plants to other retailers? If so, do you know who the businesses are in your area that you could work with? Or, if you are planning on entering the retail space, do you know how many other cannabis businesses could be operating in your desired geographical area? Finding an audience may be the hardest part of opening any business, but it’s important work.

Banking that understands your industry

Maybe the biggest drawback to being involved in an industry as comparatively new as cannabis, is that a lot of the old methods of doing business aren’t quite available to you. Many financial institutions of various sizes are limited in the ways they can help finance cannabis businesses, from not understanding the regulations and needs of your industry, all the way to being unable to assist cannabis businesses with banking in the first place.

Finding the right banking services can be challenging

It might be advantageous to look into banks, credit unions or financing companies in your area that specifically offer banking services (like business accounts and the like). A few examples include Aery Group from New Mexico, or Seed to Sale in Michigan. (It’s important to note that many of these companies, such as Aery Group, can only service the state they’re located in due to different state-by-state regulations – check ahead to make sure you find a place that can help you!)

Knowledge of the needed licensing and regulatory requirements

Getting a license to open any business is a tricky prospect on a good day, but for an industry as wide-ranging and varied as cannabis, getting licensed can require a lot of homework.

Even if you’re lucky enough to be setting up shop in a state that allows for the sale of cannabis, the licensing process can vary widely from state-to-state. In New Mexico, for example, it can take months to acquire a license simply due to the amount of paperwork, research and submissions required to cement your business. Before going too far down the rabbit hole of opening your business, make sure to take the time you need to completely research and understand the various local and state regulations you’ll need to adhere to for your business to get off the ground.

Obviously, there’s going to be a lot of other hurdles and requirements that come with starting a business – but by remembering these five things, you’ll be off to a much better start than many others.

A Q&A with Matt Hawkins, Co-Founder & Managing Partner at Entourage Effect Capital

By Aaron Green
No Comments

The cannabis industry saw close to $15.5B in deals across VC, private equity, M&A and IPOs in 2020 according to PitchBook data. Early and growth stage capital has been a key enabler in deal activity as companies seek to innovate and scale, taking advantage of trends towards national legalization and consolidation. Entourage Effect Capital is one of the largest VC firms in cannabis with over $150MM deployed since its inception in 2014. Some of their notable investments include GTI, CANN, Harborside (CNQ: HBOR), Acreage Holdings, Ebbu, TerrAscend and Sunderstorm.

We spoke with Matt Hawkins, co-founder and managing partner at Entourage Effect Capital. Matt started Entourage in 2014 after exiting his previous company. He has 20+ years of private equity experience and serves on the Boards of numerous cannabis companies. Matt’s thought leadership has been on Fox Business in the past and he has also recently featured on CNBC, Bloomberg, Yahoo! Finance, Cheddar and more.

Aaron Green: How did you get involved in the cannabis industry?

Matt Hawkins: We’ve been making investments in the cannabis industry since 2014. We’ve made 65 investments to date. We have a full team of investment professionals, and we invest up and down the value chain of the industry.

I had been in private equity for 25 years and I kind of just fell into the industry after I’d had an exit. I started lending to warehouse owners in Denver that were looking to refinance their mortgages out of commercial debt into private debt, which would then give them the ability to lease their facilities to growers. I realized there would be a significant opportunity to place capital in the private equity side of the cannabis business. So, I just started raising money for that project and I haven’t looked back. It’s been a great run and we’ve built a fantastic portfolio. We look forward to continuing to deploy capital up to and through legalization.

Green: Do you consider Entourage Effect Capital a VC fund or private equity firm? How do you talk about yourself?

Hawkins: In the early stages of the industry, we were more purely venture capital because there was hardly any revenue. We’re probably still considered a venture capital firm, by definition, just because of the risk factors. As the industry has matured, the investments we make are going to be larger. The reality is that the checks we write now will go to companies that have a track record of not only 12 months of revenue, but EBITDA as well. We can calculate a multiple on those, and that makes it more like lower/middle-market private equity investing.

Green: What’s your investment mandate?

Matt Hawkins, Co-Founder and Managing Partner at Entourage Effect Capital

Hawkins: From here forward our mandate is to build scale in as many verticals as we can ahead of legalization. In the early days, we were focused on giving high net worth individuals and family offices access to the industry using a very diversified approach, meaning we invested up and down the value chain. We’ll continue to do that, but now we’re going to be really laser focused on combining companies and building scale within companies to where they’re going to be more attractive for exit partners upon legalization.

Green: Are there any particular segments of the industry that you focus on whether it’s cultivation, extraction or MSOs?

Hawkins: We tend to focus on everything above cultivation. We feel like cultivation by itself is a commodity, but when vertically integrated, for example with a single-state operator or multi-state operator, that makes it intrinsically more valuable. When you look at the value chain, right after cultivation is where we start to get involved.

Green: Are you also doing investments in tech and e-commerce?

Hawkins: We’ve made some investments in supply chain, management software, ERP solutions, things like that. We’re not really focused on e-commerce with the exception of the only CBD company we are invested in.

Green: How does Entourage’s investment philosophy differ from other VC and private equity firms in cannabis?

Hawkins: We really don’t pay attention to other people’s philosophies. We have co-invested with others in the past and will continue to do so. There’s not a lot of us in the industry, so it’s good that we all work together. Until legalization occurs, or institutional capital comes into play, we’re really the only game in town. So, it behooves us all to have good working relationships.

Green: Across the states, there’s a variety of markets in various stages of development. Do you tend to prefer investing in more sophisticated markets? Say California or Colorado where they’ve been legalized for longer, or are you looking more at new growth opportunities like New York and New Jersey?

Hawkins: Historically, we’ve focused on the most populous states. California is obviously where we’ve placed a lot of bets going forward. We’ll continue to build out our portfolio in California, but we will also exploit the other large population states like New Jersey, New York, Arizona, Massachusetts, Michigan, Ohio and Illinois. All of those are big targets for us. 

Green: Do you think legalization will happen this Congress?

Hawkins: My personal opinion is that it will not happen this year. It could be the latter part of next year or the year after. I think there’s just too much wood to chop. I was encouraged to see the SAFE Banking Act reappear. I think that will hopefully encourage institutional capital to take another look at the game, especially with the NASDAQ and the New York Stock Exchange open up. So that’s a positive.

I think with the election of President Biden and with the Senate runoffs in Georgia going Democrat, the timeline to legalization has sped up, but I don’t think it’s an overnight situation. I certainly don’t think it’ll be easy to start crossing state lines immediately, either.

Green: Can you explain more about your thoughts on interstate commerce?

Hawkins: I think it’s pretty simple. The states don’t want to give up all the tax revenue that they get from their cultivation companies that are in the state. For example, if you allow Mexico and Colombia to start importing product, we can’t compete with that cost structure. States that are neighbors to California, but need to grow indoors which is more expensive, are not going to want to lose their tax revenues either. So, I just think there’s going to be a lot of butting heads at the state level.

The federal government is going to have to outline what the tax implications will be, because at the end of the day the industry is currently taxed as high as it ever will be or should be. Anything North of current tax levels will prohibit businesses from thriving further, effectively meaning not being able to tamp down the illicit market. One of the biggest goals of legalization in my opinion should be reducing the tax burden on the companies and thereby allowing them to be able to compete more directly with the illicit market, which obviously has all the benefits of reduced crime, etc.

Green: Do you foresee 280E changes coming in the future?

Hawkins: For sure. If the federal illegality veil is removed – which means there’ll be some type of rescheduling – cannabis would be removed from the 280E category. I think 280E by definition is about just illegal drugs and manufacturing and selling of that. As long as cannabis isn’t part of that, then it won’t be subject to it.

Green: What have been some of the winners in your portfolio in terms of successful exits?

Hawkins: When the CSC started allowing companies in Canada to own U.S. assets, the whole landscape changed. We were fortunate to be early investors in Acreage and companies that sold to Curaleaf and GTI before they were public. We are big investors in TerrAscend. We were early investors in Ebbu which sold to Canopy Growth. Those were huge wins for us in Fund I. We also have some interesting plays in Fund II that are on the precipice of having similar-type exits.

You read about the big ones, but at the end of the day, the ones that kind of fall under the radar – the private deals – actually have even greater multiples than what we see on some of the public M&A activity.

Green: Governor Cuomo has been hinting recently at being “very close” on a deal for opening up the cannabis market in New York. What do you think are the biggest opportunities in New York right now?

Hawkins: If it can get done, that’s great. I’m just concerned that distractions in the state house right now in New York may get in the way of progress there. But if it doesn’t, and it is able to come to fruition, then there isn’t a sector that doesn’t have a chance to thrive and thrive extremely well in the state of New York.

Green: Looking at other markets, Curaleaf recently announced a big investment in Europe. How do you look at Europe in general as an investment opportunity?

Hawkins: We have a pretty interesting play in Europe right now through a company called Relief Europe. It’s poised to be one of the first entrants to Germany. We think it could be a big win for us. But let’s face it, Europe is still a little behind, in fact, a lot behind the United States in terms of where they are as an industry. Most of the capital that we’re going to be deploying is going to be done domestically in advance of legalization.

Green: What industry trends are you seeing in the year ahead?“We’re constantly learning from other industries that are steps ahead of us to figure out how to use those lessons as we continue to invest in cannabis.”

Hawkins: Well, I think you’ll see a lot of consolidation and a lot of ramping up in advance of legalization. I think that’s going to apply in all sectors. I just don’t see a scenario wherein mom and pops or smaller players are going to be successful exit partners with some of the new capital that’s coming in. They’re going to have to get to a point where they’re either selling to somebody bigger than them right now or joining forces with companies around the same size as them and creating mass. That’s the only way you’re going to compete with companies coming in with billions of dollars to deploy.

Green: How do you see this shaking out?

Hawkins: That’s where you start to look into the crystal ball. It’s really difficult to say because I think until we get to where we truly have a national footprint of brands, which would require crossing state lines, it’s going be really difficult to tell where things go. I do know that liquor, tobacco, beer, the distribution companies, they all are standing in line. Big Pharma, big CPG, nutraceuticals, they all want access to this, too.

In some form or fashion, these bigger players will dictate how they want to go about attacking the market on their own. So, that part remains to be seen. We’ll just have to wait and see where this goes and how quickly it goes there.

Green: Are you looking at other geographies to deploy capital such as APAC or Latin America regions?

Hawkins: Not at this point. It’s not a focus at all. What recently transpired here in the elections just really makes us want to focus here and generate positive returns for investors.

Green: As cannabis goes more and more mainstream, federal legalization is maybe more likely. How do you think the institutional investor scene is evolving around that? And is it a good thing to bring in new capital to the cannabis market?

Hawkins: I don’t see a downside to it. Some people are saying that it could damage the collegial and cottage-like nature of the industry. At the end of the day, if you’ve got tens of billions of dollars that are waiting to pour into companies listed on the CSC and up-listing to the NASDAQ or New York Stock Exchange, that’s only going to increase their market caps and give them more cash to acquire other companies. The trickle-down effect of that will be so great to the industry that I just don’t know how you can look the other way and say we don’t want it. 

Green: Last question: What’s got your attention these days? What’s the thing you’re most interested in learning about?

Hawkins: We’re constantly learning about just where this industry is headed. We’re constantly learning from other industries that are steps ahead of us to figure out how to use those lessons as we continue to invest in cannabis. We all saw the correlation between cannabis and alcohol prohibition. The reality is that the industry is mature enough now where you can see similarities to industries that have gone from infancy to their adolescent years. That’s kind of where we are now and so we spend a lot of time studying industries that have been down this path before and see what lessons we can apply here.

Green: Okay, great. So that concludes the interview!

Hawkins: Thanks, Aaron.
Cannabis Revival and Year of the SPAC’s: What’s To Be Expected the Rest of 2021?

By Michael Sassano
No Comments

The unusual nature of 2020 gave rise to a reciprocally roller-coaster-like cannabis market. Cannabis was cemented officially as an essential industry with the rise of COVID-19, and November elections resulted in even more United States markets welcoming medical and adult-use sales.

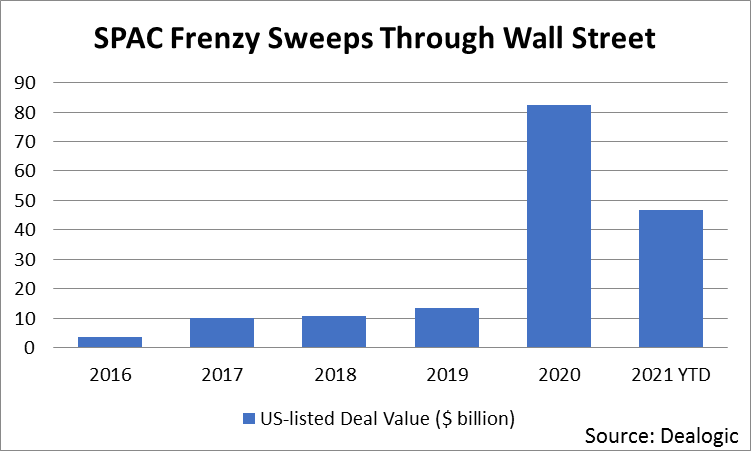
The stagnant cannabis stock market of 2019 became a thing of the past by the end of 2020. Throughout the course of last year, bag holders anxiously watched cannabis options creep back up. Now, nearly two years since market decline in 2019, the cannabis stock market is exploding with blank checks and buyout fever. Much of this expectant purchasing is due to Canadian companies considering U.S. market entrance. Combined with the recent surge in the use of special purpose acquisition companies (SPACs) to invest, this has led to an increase in asset prices.

A SPAC is defined as “a company with no commercial operations that is formed strictly to raise capital through an initial public offering (IPO) for the purpose of acquiring an existing company.” Though they have existed for decades, SPACs have become popular on Wall Street the last few years because they are a way for a company to go public without the associated headaches of preparing for a traditional IPO.

In a SPAC, investors interested in a specific industry pool their money together without knowledge of the company they’re starting. The SPAC then goes public as a shell company and begins acquiring other companies in the associated industry. Selling to a SPAC is usually an attractive option for owners of smaller companies built from private equity funds.

The U.S.-Canadian market questions that this rising practice asks are: Can Canadian companies enter a bigger market and be more successful? Is it advisable for U.S. companies to sell their assets to Canadian corporations whose records may be marred by a history of losses and a lack of proper corporate governance? Regardless — if both SPAC’s and Canadian bailout money is here, what comes next?

What is Driving this Bull Market?

Underpinning these movements are record cannabis sales internationally, making last year’s $15 billion dollars’ worth of sales in the U.S. look small in comparison. New markets have opened up in various states and countries throughout 2020, and that trend is only expected to continue. New demographics are opening up, especially among older age groups. This makes sense, as most cannabis sales — even in a recreational setting — are people treating something that ails them like insomnia or aches and pains.

Cannabis is set to take off, and we are entering only the second phase of its market expansion. The world is becoming competitive. Well-run companies that are profitable in key markets are prime targets for bigger, growing companies. At the same time, the world of SPACs will continue to drive valuations. Irrespective of buying assets, growing infrastructure is and will continue to be greatly needed.

The Elusive Profitability Factor

When Canada blew up, one of the biggest changes was companies began focusing the year on cost cutting and — most importantly — profitability. Profitability became the buzzword. But bigger companies are on the search for already-profitable enterprises, not just those that have the potential to be. However, profitability is currently still unobtainable in Canada. Reasonable forecasters should expect this year will show a few companies getting bailed out while many others will be forced to either merge for survival or declare bankruptcy.

An ideal company’s finances should highlight not only revenue growth, but also profitability. Attention should be focused on how well businesses are run, and not on how much money they have the potential to raise or spend. Over the years, there have been many prospective companies that spent hundreds of millions only to barely operate, and are now shells in litigation. Throwing money at any deal should have been a lesson learned in the past, but SPACs are tempting because they are trendily associated with new, interesting management styles and charismatic businesspeople.

Companies should be able to present perfect and clear financials along with maintenance logs for all equipment. In today’s day and age, books must be stellar and clean. As money pours into SPACs, asset valuations for all qualities of companies will rise. The focus instead becomes about asset plays, which will cause assets to continue rising as money is poured into SPACs.

Once upon a time, if number counters presented a negative review or had to dig too much, executives would turn a cold shoulder on investment. But in the age of SPACs, these standards of evaluation will be greatly undervalued. Aging equipment and reportability of every piece of equipment may or may not be properly serviced and recorded in a fast-moving market. Costs of repair or replacing equipment that isn’t properly maintained may be a problem of the past. Because when money comes fast, none care for the gritty details.

Issues for SPACs

Shortage of talent and training has become a big concern already in the era of SPACs. How many quality assets are out there? Big operators in the U.S. are content and don’t see Canada as an enticing market to enter. So, asset buys are likely to primarily be in the U.S. Large companies like Aphria may buy out some of the major American players, but most Canadian companies will use new funding rounds to pay down debts. Accordingly, they will then be forced to piece together smaller operators as a strategy.

A cannabis company’s personnel and office culture are very important when looking to integrate into a larger corporate culture. Remember, it’s not just the brick and mortar that is being invested into, it is also the people that run a facility. Maintaining employee retention when a deal occurs is always critical. Your personnel should be highly trained and professional if you want to exit. Easy to plug-in corporate structures make all the difference in immediately gaining from the sale or having to retool the shed and bring in all new people.

The rise of the SPAC-era and Canadian entry into the U.S. market will cause asset increases, but it is only the second chapter in the market expansion of cannabis. Proper buys will nail profitability, impeccable books, proper maintenance records and will have created an efficient corporate structure with talented personnel. The rest will be overpriced land buys that will require massive infrastructure spending. The basics of a well-run organization don’t change. The cannabis market is going to ROAR, but don’t worry if the SPACs pass you by- they are buying at the start of cannabis only.

Wyoming Lawmakers Introduce Bill to Legalize Cannabis

By Cannabis Industry Journal Staff
No Comments

Update: The House Judiciary Committee has passed the legalization bill, HB0209, by a 6-3 vote. After moving out of the Judiciary Committee, the bill now awaits a floor hearing, which is expected to come within the next week or two during the legislative session that ends on April 2. 

A bipartisan group of lawmakers in Wyoming have introduced a bill to legalize cannabis in the state’s legislature. First reported by Buckrail.com, HB0209 was assigned on March 2. The bill would legalize possession, home grow and sales for adults, as well as establish a regulatory framework for licensing, tracking and taxation.

In November 2020, voters in Montana and South Dakota passed ballot measures that legalize adult use and sales of cannabis. About a month after Election Day, the University of Wyoming conducted a poll that found roughly 54% of Wyoming residents now support legal adult use cannabis. In 2018, UW found that 85% of Wyoming residents support medical cannabis legalization.

In March of 2019, Wyoming Governor Mark Gordon signed a bill into law that essentially legalized hemp in the state. That bill was a boon for the state’s agricultural economy, giving many farmers a much-needed boost in their crop diversity.

Wyoming Governor Mark Gordon

You can find the current version of HB0209 here. Sponsors of the bill include: Representatives Jared Olsen (R-Laramie), Mark Baker (R-Sweetwater) Eric Barlow (R-Campbell/Converse), Landon Brown (R-Laramie), Marshall Burt (L-Sweetwater), Cathy Connolly (D-Albany), Karlee Provenza (D-Albany), John Romero-Martinez (R-Laramie), Pat Sweeney (R-Natrona), Cyrus Western (R-Sheridan), Mike Yin (R-Teton) and Dan Zwonitzer (R-Laramie) and Senators Cale Case (R-Fremont) and Chris Rothfuss (D-Albany).

According to Buckrail, if the bill becomes law, Wyoming could get roughly $49.15 million in tax and license fee revenue in 2022. That number would mean a sizable windfall for the state that saw an 8.5% decline in tax revenue in 2020. Governor Gordon proposed budget cuts as high as 15% for agencies across the state last year. Most of the revenue generated from cannabis taxes would be earmarked for education.

Wyoming’s tax revenue is notoriously limited when it comes to diversity: the state makes its money on oil and gas, and that’s about it. Earlier this year, the Biden administration halted oil and gas leasing on federal land, hitting pause on a nearly half-million-acre deal. If the pause on oil and gas leasing on federal lands continues or were to become permanent, Wyoming stands to lose tens, if not hundreds, of millions of dollars every year.

So, what does the least populous state in the country do when they can no longer generate revenue from oil and gas? Simple. Legalize cannabis.

Soapbox

How Rare Cannabinoids Will Impact Investing

By Maxim Mikheev, Dennis O’Neill
No Comments

There is a significant increase in demand for all cannabinoid products across the board—including CBD, THC, CBG and THCV—from recreational users, consumer packaged goods and pharmaceutical companies. And the next great race is on for the hottest arrival to scientific cannabis therapeutics: rare cannabinoids.

Research shows rare cannabinoids are poised to be the future of cannabis investing, providing better health benefits in addition to impacting the pharmaceutical, CPG, nutraceuticals, cosmetics and pet care markets significantly. According to recent reports, the biosynthesis of rare cannabinoids will be a $25 billion market by 2025 and $40 billion by 2040.

The companies that will revolutionize this market are ones with the highest quality and lowest prices, which means that biosynthetic cannabinoid companies will be the leaders in investment and capturing market share. We will also see a major consolidation in this market amongst the grow, harvest and extraction companies, increasing efficiencies and driving down costs.

What are rare cannabinoids and why should we care?

Tetrahydrocannabivarin (THCV)

Rare cannabinoids such as CBG, CBN, THCV, THCA and others have significantly better and more specific health benefits than just CBD on its own. Biotech companies like ours, Biomedican, which has a patent-pending biosynthesis platform, can produce pharmaceutical grade, non-GMO, bioidentical, synthetic cannabinoids with 0.0% THC at 70-90% less cost. Producing 0.0% THC means that rare cannabinoids can be added into nutraceuticals, CPG and cosmetics/lotions with zero changes in current cannabis regulations. Also, we produce the same exact product every time (not possible through plants), which is extremely important for pharmaceutical companies conducting clinical trials.

Why are rare cannabinoids important?    

The human body contains different cannabinoid receptors that help regulate critical processes, including learning, memory, neuronal development, appetite, digestion, inflammation, overall mood, sleep, metabolism and pain perception. This considerable involvement of cannabinoid receptors, critical to many physiological systems, underscores their potential as pharmaceutical targets.

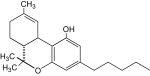
Tetrahydrocannabinol (THC), just one of hundreds of cannabinoids found in cannabis.

Pharmacological research has uncovered several medical uses for cannabinoids, which bind to cannabinoid receptors. They’ve been shown to help with pathological conditions such as pediatric epilepsies, glaucoma, neuropathic pain, schizophrenia and have anti-tumor effects as well as promote the suppression of chemotherapy-induced nausea. This ongoing research is becoming more prevalent and has the potential to uncover therapeutic uses for an array of cannabinoids.

In addition to the medical field, other prominent sectors have adopted the use of cannabinoids. There is an increasing demand for cannabinoids in inhalables, the food industry and in hygienic and cosmetic products. Veterinary uses for cannabinoids are also coming to light. The use of naturally occurring cannabinoids reduces the need for synthetic alternatives that may produce harmful off-target effects. 

So how does this affect the investing market?

Where there is demand, significant and growth investments follow. All the major players from nutraceuticals, CPG, cosmetics and pet care companies are driving the demand for rare cannabinoids. We are seeing a major investment shift from commodity-based prices for cannabis and CBD to the new biosynthesis technology which offers significantly better health benefits and higher profit margins. Those unique qualities of rare cannabinoids open an enormous opportunity to create new drugs and food supplements for treating various medical conditions and improving the quality of life. This creates a massive global opportunity for all companies in these categories differentiating their products from competitors.

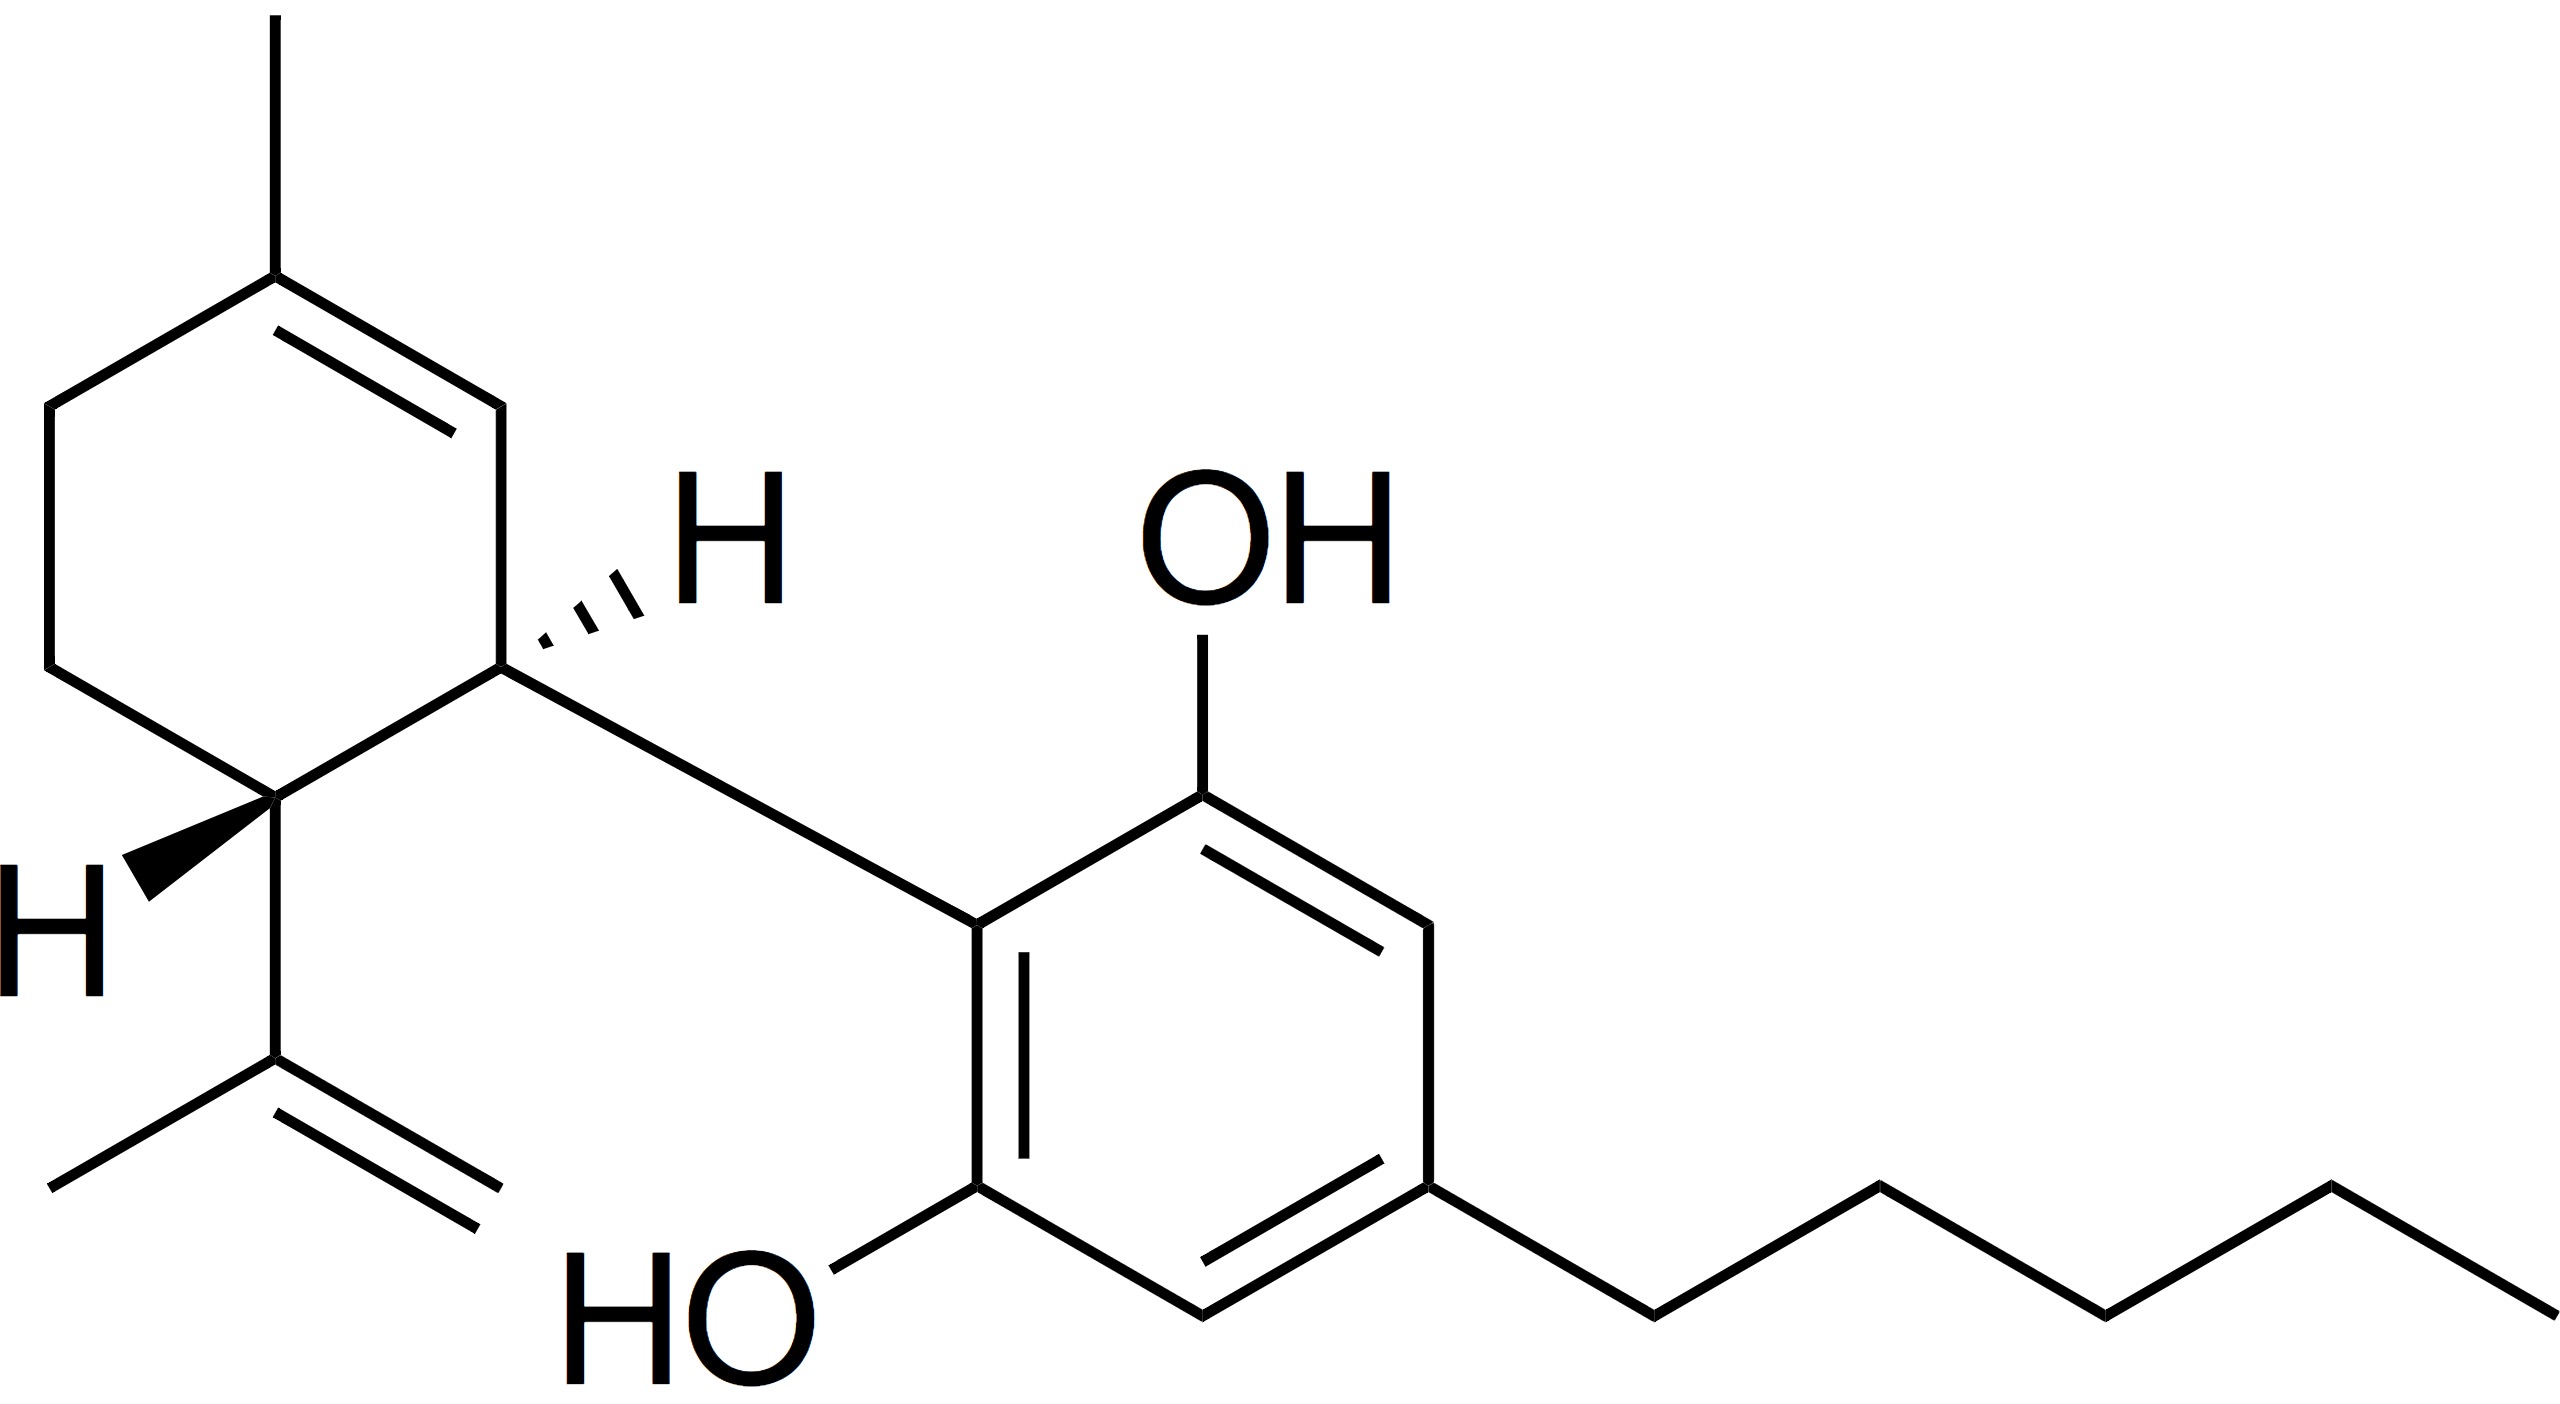
The structure of cannabidiol (CBD)

There will be big winners and losers in these markets, but at the end of the day, the highest quality and lowest cost producers will capture most of these markets. Biomedican has the highest quality, highest yields and lowest cost of production in the industry. Which we believe will make us the clear leader in the biosynthesis rare cannabinoid markets.

Which rare cannabinoid to invest in first?

Early reports indicate THCV (not to be confused with THC) could contain a variety of health benefits: it may help with appetite suppression/weight loss, possibly treat diabetes as well the potential to reduce tremors and seizures caused by conditions like multiple sclerosis, Parkinson’s disease and ALS.

There has been an explosion of interest in THCV due to its potential health benefits. We are seeing major players in the nutraceutical, health food and pharmaceutical industries clamoring to add THCV to their product lines. Companies can now produce THCV through biosynthesis, creating a pharmaceutical-grade, organic, bioidentical compound at 70-90% less than wholesale prices. This is exactly what the largest players in the market want: a pharmaceutical-grade, consistent product at significantly less cost. The current prices and quality have limited THCV production, but new breakthroughs in biosynthesis have solved those issues, so we expect a tsunami of orders for THCV in 2021.

Q&A with Bruce Macdonald, Chairman of C21 Investments

By Aaron Green
No Comments

Multi-state operators (MSOs) are on the rise in the United States, navigating complex regulatory frameworks to drive profitability through economies of scale and scope. C21 Investments is a vertically integrated cannabis company with operations in Nevada and Oregon; traded on the Canadian Stock Exchange (CXXI) and on the OTCQX (CXXIF). The company recently secured a commitment from Wasatch Global Investors, JW Asset Management (Jason Wild/TerrAscend) and CB1 Capital Management (Todd Harrison) who, in addition to C21’s CEO, provided an equity commitment for repayment of all convertible debt.

We spoke with Bruce Macdonald, Chairman of C21 Investments. Bruce joined C21 in 2018 after reviewing the company as a personal investment and getting to know the senior management team. Prior to C21, Bruce had a long and successful career in finance and capital markets at one of Canada’s largest banks.

Aaron Green: Can you give a brief overview of C21?

Bruce MacDonald: C21 is a cannabis company that has operations in both Nevada, and in Oregon. Oregon is fundamentally a wholesale business, and we recently announced a divestment of some non-core assets in the state. Our cash cow and where we currently see our best opportunity for future growth is our Nevada operations. We run a seed-to-sale business in the state with two dispensaries doing about $35M a year in revenue, with a 40% EBITDA Margin, and servicing 600,000 customers.

Aaron: Can you tell me about a little bit about your background and how you got involved in a cannabis company?

Bruce: I spent 37 years working for RBC in the capital markets business. I started as a floor trader, back when there was such a thing as a floor, and over the years held a number of positions, ultimately working my way up to Chief Operating Officer of the bank’s global capital markets division. Throughout my time, I built a lot of businesses, which was why C21 and this opportunity was so interesting to me.

My involvement in the cannabis sector was a bit of an accident, but it’s turned into a passion. It actually found me. I was an investor in the C21 IPO. I sat down with management to understand the investment and given my experience, they asked if I would consider becoming a member the Board. Since joining the Board, my involvement has been primarily focused on strategy and the financing side of the business. While I certainly didn’t anticipate it, it’s turned into a 24/7 gig and a challenge I am thoroughly enjoying.

Bruce Macdonald, Chairman of C21 Investments

Aaron: Can you tell me about the history of C21 becoming a MSO? Did you start in one state?

Bruce: While this history predates my time at the company, my understanding is that as a Canadian company, we had first mover advantage to be able to access public funding and get established in the US cannabis space. As part of that, the team at that time reviewed approximately 100 different properties. Because we were based out of Vancouver, the focus was primarily the Western states like Washington, Oregon, Nevada and California. Arizona wasn’t in the game yet. The first transaction C21 did was in Oregon, with a company called Eco Firma. In all, there were four acquisitions in Oregon, and one in Nevada. In fact, it was the investment in Silver State (Nevada) that was by far the most meaningful. As far as our Oregon assets are concerned, we have worked hard to integrate and streamline them into an efficient operation.

So, when I joined the Board, we were just completing the paperwork on the acquisitions, and finalizing our strategy and business plan to go forward.

Aaron: Today there are a number of MSOs. How does this more crowded market impact your value proposition; how do you think about gaining and maintaining strategic advantage?

Bruce: It’s important first to start with strategy. From a strategic perspective, we had the advantage of being the first operator in Nevada with Silver State. Sonny Newman, our CEO, started the business back in 2013. We run a seed-to-sale business so we have a deep knowledge of all aspects of the operation and really know the Nevada market. In fact, 70% on a dollar volume basis of the 700 SKUs that we sell are products that we manufacture. It’s a critical piece of our strategic advantage.  

What I would say is our most important strategic advantage is the fact that C21 is a stable, self-sustaining operator. What I mean by that is we’re one of the few businesses that actually makes money. This is what really allows us to be strategic and disciplined in our approach to growth. For example, it’s been more than 18 months since we did our last capital raise and that’s by choice. Every decision we make is through the shareholder lens and focusing on delivering value to customers and shareholders.

Looking at our value proposition, simply put, it comes down to four things – the right products, at the right price, in the right location, with the right environment. Some people might call this motherhood, but there’s a lot of work that goes behind each of them. 

Great quality products, that’s table stakes. You have to be a top-notch grower and generate quality products that people demand if you want to build a loyal customer base. Right price – to some it sounds like just putting the right sticker on the package – it’s not. It’s all about making sure you are efficient in your operations because to be profitable, you have to be a low-cost producer to deliver on a lower price promise. Tons of work has gone into our operation around being a “right price” business. 

Right location is another important element of our value proposition. We wanted to build a loyal customer base which for us meant focusing more on locals than on tourists. This is why Sonny positioned the dispensaries on commuter paths.

The last key factor is having the right environment to sell our products. In Nevada, the company ended up building fit-for-purpose dispensaries rather than fitting ourselves in a strip mall. We cater to over 600,000 clients a year. Now we’re doing 10,000 curbside pickups a month. With that type of volume, logistically speaking you need ample parking, a well-lit exterior so people feel safe, and of course, great curb appeal. These factors are essential in maintaining a loyal customer base.

Aaron: Tell me more about Silver State Relief and why it has been so successful?

Bruce: I think what you’re really asking for is: what is Sonny’s secret sauce? There are a few ingredients that go into it. As I highlighted, it was a purposeful decision to build a business with a loyal customer base focused primarily on locals. That needs product, price, and convenience. Sonny lives in the Reno area, which is one of the main reasons Silver State is located up North.  

Critical to success has been the culture of the organization. Let’s start with the company being nimble and I’ll give you an example. The early days of the pandemic included the complete shutdown of dispensaries. We went from serving over 1500 customers a day in our stores to the next day being told that we could offer delivery only. Within a week, we were able to pivot and had lockboxes, regulatory approvals and a delivery capability. When you look at our Nevada operation, we ended up with just a 10% dip in our revenues for the quarter, even though we had to live through six weeks of delivery-only and then a phase of curbside-only.

Another key element of the culture is our laser focus on cost management. We’ve talked a little about cost management, but it’s absolutely critical, especially in the context of the high cost of capital that we see in this sector. Add to that the punitive tax impact of 280e where federal tax is applied to gross margins which means SG&A and interest are non-deductible expenses for tax purposes. So, to enhance our profitability, we are intent on having the lowest SG&A of the public cannabis companies. We’re also among the lowest in interest expense. That whole drive for efficiency has given us a formula and a mantra that has allowed us to have a stable business with significant cash flow. We get to make strategic decisions — not hasty or desperate ones — and focus on what’s good for the shareholder.

Aaron: How was C21 capitalized?

Bruce: We did a $33M raise on the RTO of a listed shell company. That was how C21 was established, and then signed contracts with the Oregon and Nevada properties.

Aaron: I recently saw a press release about expanding the Nevada cultivation. Can you give me some more details? 

Bruce: We announced that we are tripling our capacity within our existing 100,000 square foot warehouse facilities. We’re going to build out another 40,000 square feet, and we currently use 20,000. That’s the tripling. Expanding our cultivation was clearly the next logical step in our growth story. This should yield us an additional 7,500 pounds of high-quality flower. We can do this very cost effectively with about $6M in capex, and we anticipate funding the project internally. We will still leave another 40,000 square feet of expansion capacity as market needs justify.

This announcement was significant, but I don’t think it was fully understood by the market. Just to play with some numbers, 7,500 pounds of flower has a wholesale market value today of about $17M. It will cost us approximately $2M in incremental operating expense to add these additional grow rooms. We already pay the rent, so we just need to pay for the people, power, fertilizer and product testing. When you do the simple math, we see this as a big win for shareholders and extremely accretive on an after-tax basis. 

Historically, we always used to grow more than we needed, but with the increase in demand that’s going on in the market, we now run at a flower deficit. In the near term, this build-out will allow is to meet our current retail needs, with the balance that we will sell on the wholesale market. Ultimately, this positions us well on a seed-to-sale basis to support our plans to extend our retail footprint in Nevada. 

Aaron: It sounds like the decision was made based on both revenue growth and supply chain consolidation?

Bruce: Yes, and just the pure profitability of it! You can’t get a bigger, better bang for your buck from spending $6M to generate $17M with ongoing operating costs of $2M.

Aaron: The next question here is about the recent note restructuring and, and how the debentures was restructured. How’d that come about and what is the advantage now of having gone through that process? 

Bruce: This all fits into our medium-term growth strategy. For C21, the first thing we focused on was getting our house in order to ensure that we were efficient and profitable. We knew we needed to have a scalable machine to grow. The second step, which the debt restructuring relates to, was around fortifying our balance sheet. To support our growth plans, we needed to have a solid foundation.

Our balance sheet had two things that needed fixing. One was that we had an $18M obligation coming due to our CEO. The effect of the restructuring extended this obligation over the next 30 months at favorable terms. Additionally, $6.5M of convertible debentures were reaching maturity in January of 2021. And while the debentures were in the money and theoretically would convert to shares, we didn’t want to take the risk that our stock price could drift a bit and all of a sudden there could be significant cash required for redemptions. We’ve seen a lot of companies suffer significant unwanted dilution when their debentures get out of control. So, we approached Wasatch, Jason Wild’s JWAM and CB1 Capital, three seasoned investors, who provided a backstop whereby they would purchase any shares not taken up by people though the conversion of their debentures, so that we would be able to pay any debenture holders back cash with the money we would receive as the investors took shares. In exchange for providing this backstop, C21 gave them an upside participation in the form of warrants. I think it was absolutely critical to get this in place. And it’s phenomenal to have these three names in our corner. We couldn’t imagine better partners.

Aaron: So, what’s next for C21? 

Bruce: I hope you are getting the feeling that here at C21 our objective is to play the long game. That means we make measured decisions with the interest of shareholders top of mind. We’ve worked hard in 2020 to get our house in order, fortify our balance sheet, and generate significant cash flow. I think we’re clocking in at around $12M in trailing annual cash flow, which interestingly, is about the same number that Planet 13 is doing. That’s obviously a fantastic result for a company with $150M of market cap.

“We are working with urgency to break the back of these sector economics.”When we think about our medium-term growth strategy, we will continue to make our decisions through a cash flow and earnings lens rather than hype and flash. While we will remain opportunistic with respect to strategic alternatives, the core of our expansion is going to focus on where we already have a proven track record: Nevada. We’re big believers that to achieve long term success, you have to own your home market. And what I mean by that is today we’re about 5% of the Nevada market. Owning your home market looks more like a 15% share. That is our focus. I think we’ve shown that our disciplined approach delivers results – results such as having top five metrics in Net Income, Cash Flow and EBITDA Margin, across the range of public companies that we can see.

I think it’s key we’re getting noticed. We talked about the strategic investors, but we’re also one of the 17 plant-touching companies that’s in the MSOS ETF. So, we’re going to follow our clear growth trajectory, focused on the bottom line and delivering for shareholders. If you look under the hood right now, you see a 10% cash flowing company, which is a pretty rare bird in our industry. We’re excited about where we are.

One thing I haven’t touched on in great detail is our plans for expanding our retail footprint. How do you grow in the dispensary space? Aaron, I think what’s key here is looking at the expected return relative to the cost of capital. For example, if you targeted buying a dispensary with $20M in revenues, and are able as we are, to generate 25% in after-tax cash based on those revenues, then once optimized, it would generate $5M in earnings. An asset like this is going to trade at roughly one and a half times revenues. So, you’re going to have to pay $30M. For the people that have been going out and borrowing money at 15%, their annual cost would be $4.5M. We’re not going to give four and a half to the moneylenders, it just doesn’t make sense for shareholders. We are working with urgency to break the back of these sector economics. It is something we believe will be afforded to companies with stable earnings and profitability such as ours. Of course, no deal’s a deal until it’s on the tape, but we are very hopeful that we have cracked the code ahead of SAFE Banking to get capital costs down. This is just a little bit of an inside look into our thought processes.   

Aaron: Okay, awesome. All right. That concludes the interview.

Cannabis M&A in the Post-COVID Era

By Jose Sariego
No Comments

After a slow start following a disappointing 2019, M&A in the cannabis space closed 2020 with a bang, with more than $600 million in deals announced immediately following the November elections. Prospects for the New Year are expected to continue the explosive year-end trend with a backlog of nearly $2 billion in deals heading into 2021. The COVID-19 pandemic boosted sales of cannabis products, and election results opening up five new states to legal cannabis use and possible federal regulatory reform are further boosting prospects. Analysts now predict the U.S. cannabis market is poised to double by 2025.

Growth is expected to be led by multi-state operators who have achieved scale, cleaned up their balance sheets and stockpiled dry powder for roll-up acquisitions. Cannabis companies raised nearly $134 million in the two weeks before Election Day, a 185% increase over the same period last year. Most of the money flowed to multistate operators. In addition, the biggest stocks by market capitalization saw a roughly 20% bump ahead of the election and now are trading at record volumes, providing plenty of stock currency for further acquisitions.

Among the headline acquisitions last year:

  • Curaleaf continued its multi-state expansion with two of its largest acquisitions – the all-stock purchases of its affiliated cannabis oil company Select and of Grassroot, another MSO player. Curaleaf is now the largest cannabis company in the world based on annualized revenues, with annualized sales of $1 billion and operations in 23 states and 96 open dispensaries. Curaleaf also raised $215 million privately last year end for further expansion.
  • Close behind, Aphria and Tilray announced in December that they will merge, creating what they say will be the largest cannabis company in the world with an equity value of roughly $3.8 billion. The combined entity will have facilities and offices in the U.S., Canada, Portugal and Germany. The deal is expected to close during the second quarter of this year.
  • Also in December, Illinois-based Verano Holdings LLC unveiled plans to go public at a $2.8 billion valuation through a reverse takeover of a Canadian shell company. That deal followed the announcement that Verano will merge with Florida-based AltMed.
  • In addition, publicly traded New York cannabis firm Columbia Care signed a definitive agreement last month to acquire Green Leaf Medical, a privately held Maryland-based cannabis manufacturer and retailer, for $45 million in cash and $195 million in stock. The acquisition is expected to close this summer. Including Green Leaf’s inventory, the Columbia Care will operate 107 facilities, including 80 dispensaries and 27 cultivation and manufacturing facilities. Columbia Care also took advantage of cannabis fever last year by raising $100 million privately.
  • Also in December, Ayr Strategies announced it would acquire Liberty Health Sciences, one of the largest cannabis companies in Florida, for $290 million in stock, as well Garden State Dispensary, a New Jersey marijuana company for $41 million in cash, $30 million in stock and $30 million in the form of a note. This follows Ayr’s $81 million acquisition of an Arizona medical marijuana operator in November. Voters approved marijuana use in Arizona and New Jersey in November.  Ayr has completed a string of acquisitions in Nevada, Massachusetts, Pennsylvania, Arizona, Ohio and, upon the closing of December’s deals, New Jersey and Florida.

Not all cannabis companies will rely on acquisitions, however. Trulieve, as an example, has focused its efforts on Florida and organic growth. It remains to be seen whether a multi-state approach fueled by acquisitions or a single-state organic growth model will prove the more lasting. Growth and profitability in the short term likely will continue to be hampered by limits on economies of scale due to federal restrictions and differing state laws.

In light of the maturing industry and the 2019 bust, the valuation model for acquisitions in the cannabis space is evolving from one based on sales, typically associated with emerging growth industries, to a more mature industry model based on profits or Earnings Before Interest, Taxes, Depreciation, and Amortization (EBITDA). Most cannabis MSOs have stabilized and generate positive EBITDA, which justifies the evolution away from a sales-driven model.

From a legal standpoint, the same limitations that have vexed the cannabis industry for years will continue to challenge deal makers until there is greater clarity on the federal front. Institutional investor reluctance, financial industry constraints, haphazard state regulation and the unavailability of federal forums such as national copyright and trademark registration will continue to be issues for acquirers and their lawyers in the space.

Acquisition agreements will continue to have to address the federal Damocles’ sword should expected relaxation of federal enforcement under the Biden administration and further legislative relief does not materialize as expected. Although the U.S. House in December passed the “Marijuana Opportunity Reinvestment and Expungement Act” (MORE) to remove cannabis from the Controlled Substances Act, the Senate did not take up the bill in 2020 and it will have to be re-introduced in 2021. Notably, the MORE Act does not affect existing federal regulation of cannabis, such as the Food, Drug and Cosmetics Act, under which the FDA has limited the use of CBD in certain products despite hemp being removed from the Controlled Substances Act in 2018.

The cannabis M&A market is moving into a more mature phase, as MSOs will be choosier in their approach rather than continuing the land-grab mentality of years past. Due to improved financial strength, 2021 should see these MSOs continuing to expand their footprints either within existing states or new ones. Although uncertainties abound, further consolidation and expansion through add-on acquisitions is likely to continue apace in 2021, providing plenty of opportunities for deal makers and their lawyers.

2021 Trends: Nine Developments in California’s Cannabis Market

By Amy Steinfeld, Jack Ucciferri
3 Comments

While we’re pleased to report that 2020 is almost over, 2021 will be a mixed bag. New jurisdictions will open their doors to cannabis and consumption will continue to rise, but competition from new operators and illicit supplies will increase. As California’s cannabis industry matures and turns the page on a bizarre year, market uncertainty will linger as the pandemic drags on and overtaxation and regulation strangle profits. But let’s remember, cannabis has been cultivated for over 6,000 years and has withstood far worse—this market isn’t going anywhere and will continue to grow and become more impactful.

Access to Traditional Finance Services

The U.S. Senate will likely pass legislation providing cannabis businesses access to traditional banking and financing services. This will be a game changer for the industry. Valuations will go up. Increased liquidity will smooth transactions. Companies will look to affordable debt to expand their footprints and capacity to compete on a new scale. Full federal legalization could be a game changer if 280E tax restrictions are lifted and interstate and international cannabis trade open up, but the timing of this is hard to predict.

Continued Quarantine-Induced Consumption

Cannabis consumption will continue to increase as Californians seek to ease pandemic-related stress, temper quarantine conditions, and sample an eye-popping array of new products. Sophisticated consumers will be open to spending more on unique and niche products. But hemp-derived cannabinoids may present a new source of competition, especially if CBD remains unregulated. By the end of 2021, cannabis beverages will begin to compete with mainstream alcohol categories. Pharmaceuticals will increasingly take notice of this industry and the increasing share of consumers turning to plant-based remedies.

Ever More Cultivation Opportunities 

In pursuit of revenue, agricultural counties will liberalize their policies on cannabis cultivation by permitting more acreage and streamlining permit processes. Neighborhood groups will push back, but policymaker concerns will be assuaged when they see cannabis farms operating innocuously (and sustainably) around the state. Advances in seed breeding, pest-and-disease control, outdoor growing techniques and odor abatement technology will help too.

New Retail

Cities and counties will revisit opening their borders to cannabis retail storefront and delivery as they attempt to fill budget gaps. Many cities will allow cannabis retail for the first time and/or expand the number of licenses available. These new dispensaries will provide a much-needed outlet for the influx of licensed flower and will continue to spur innovation and consumer education. But a “second wave” of retail speculators seems poised to let optimism override judgement, setting themselves up for failure or acquisition by incumbents.

Getting Social Equity Right

2021 will be a pivotal year for social equity, which will establish a foundation for a just cannabis economy. The industry will have to grapple with how to ensure that those most impacted by the criminalization of cannabis and most often excluded from traditional financing exposure are provided with equitable access to meaningful opportunities. As California’s regulated cannabis market grows, getting social equity right will be important if the industry is to firmly establish itself as an inclusive industry that addresses impacts on marginalized communities and responds to customer demands.

Formalizing Appellations  

California’s new CalCannabis Appellations Program will provide cultivators and brands a way to credibly market the value of their unique growing regions and cultivation methods. These distinctions only apply to cannabis planted in the ground, excluding greenhouse and warehouse grows. The expectation is that high-end consumers, trained to recognize place-based designations and quality certifications in other products, will reward products that boast these designations. How many consumers will be willing to pay the premium and how long full implementation of the program will take, remains to be seen.

Prices May Begin to Drop

2020 was a great year for the few fully licensed cultivators in California permitted to sell to the regulated market. 2021 may be different. Numerous licensed cultivation projects will complete the permitting processes and come online next year. While growing demand may outpace supply at first, by Q3 supplies could swamp the market. Premium flower is perhaps an exception. Adding to the pricing pain, as always, is California’s illicit market, which will continue to undercut prices, as legal growers toil to comply with a labyrinth of state and local regulations. Nonetheless, cannabis will remain the most profitable crop on a per acre basis for some time.

Business Turmoil

The drop in prices coupled with continued high taxes and regulatory burdens will result in turnover of assets and businesses. Less efficient and inexperienced cultivators will struggle, many unable to ultimately withstand pricing pressure. Others will be hit by enforcement actions for failing to comply with California’s myriad regulations. Retailers, already burdened by punitive tax structures, real estate finance commitments and onerous local regulations, will need to be disciplined and have a clear strategy to address new competition.

Consolidation

Driven by business failures and renewed investor interest, California’s regulated cannabis industry may consolidate rapidly in the second half of 2021. Institutional finance will enter the space with a much more disciplined approach than prior capital sources. Traditional agricultural interests will invest in cannabis cultivation projects. Well-run retail chains will begin to outcompete, and then acquire, mom-and-pop competitors. Big brands will continue to expand their shelf space, relegating smaller competitors to niche and novelty status.

In short, the cannabis industry will continue to be highly dynamic, exciting, enticing and risky.