C-45 – or the Cannabis Act, passed overwhelmingly in the Senate by a vote of 52-29. Canadian Prime Minister Justin Trudeau has subsequently announced that the legislation will pass into law on October 17. The intent behind the legalization effort was to cripple organized crime and protect minors.
Only one other country in the world has taken such a dramatic step – Uruguay.
Now what?
The Medical Discussion Is Just Getting Underway
While legalization advocates and the increasingly corporate industry have everything to celebrate, this does not necessarily change the other conversation on the ground – in fact it only strengthens it.
Clearly this is a blow against prohibition still in force just south of the border in the U.S. This move alone is also likely to drive the debate in an environment where California and other states are clearly thumbing their noses at the federal government and proceeding apace with its own (and largest) U.S.-based marketplace.
However, there is another topic floating around this conversation. If cannabis is “harmless” enough for recreational use, its use for medical purposes has become the third rail that is now driving the conversation in other places – most certainly Europe.In the meantime, Canadian firms are in an unparalleled position to enter global markets (as they have already begun to do) and set the tone and debate.
Here, full legalization is absolutely off the table as policymakers and scientists begin to seriously contemplate integration of cannabinoids into comprehensive health systems. This week’s dramatic announcement in the UK to that effect, which came the same day as the Canadian vote, is one indication of that. Germany’s own cautious foray into medical use is another. The change in the law last year mandating public health insurance coverage of the same has created a population of 15,000 patients in the last year with many more lining up to obtain it. This population of patients will reliably use more cannabis every month than even the most dedicated recreational consumer.
What Comes Next?
Four and a half years after Colorado took the plunge, the world of cannabis acceptance has clearly changed – and for good.
But what is the next step? Clearly the pressure is now on in the U.S. to consider rescheduling to at least a Schedule II if not Schedule III drug. Marinol, the synthetic version of the drug, became a Schedule III drug in 2010. Epidiolex, GW Pharma’s drug derived from cannabis, just received FDA approval too. GW Pharma is the only British company allowed to develop cannabinoid medications. Let’s see how long that flag flies in the new commonwealth, with Canada fast behind the UK now as the two compete for the title of largest canna exporter. Globally.
The drug war, in other words, is finally coming to close for cannabisHowever full legalization – even in the United States and most certainly in Europe – is at least several years away.
In the meantime, Canadian firms are in an unparalleled position to enter global markets (as they have already begun to do) and set the tone and debate. How they will position themselves – as medical pharmaceutical or recreational companies – is another discussion that is still unfolding. Particularly because cannabis is a hybrid substance. And further, it is not entirely understood (nor has of course it been studied) where cannabis stops becoming a drug. If a consumer uses CBD, for example, as part of a wellness routine but also heads off a more serious condition, is the use of the plant “medical” or “recreational?”
These are all questions now on the table. But at least they are.
The drug war, in other words, is finally coming to close for cannabis. But the horizons beyond that, widely unexplored, promise blue ocean opportunities for decades to come. And not “just” in recreational use, but in the amazing worlds of science, technology and medicine that now lie within reach.
Techniker Krankenkassen (or TK as it is also frequently referred to) is one of Germany’s largest public or so-called “statutory” health insurance companies. It is companies like TK that provide health insurance to 90% of the German population.
TK is also on the front lines of the medical cannabis discussion. In fact, TK, along with other public health insurers AOK and Barmer, have processed the most cannabis prescriptions of all insurers so far in the first year after the law change. There are now approximately 15,000 patients who have received both a proper prescription and insurance approval coverage. That number is also up 5,000 since the beginning of just this year.
In a fascinating first look at the emerging medical market in Germany, TK, in association with the University of Bremen, has produced essentially the first accessible report on approvals, and patient demographics for this highly stigmatized drug.
Because it is in German, but also contains information critical to English-speaking audiences in countries where the medical issue is being approached more haphazardly (see the U.S. and Canada), Cannabis Industry Journal is providing a brief summary of the most important takeaways from TK’s Cannabis Report.
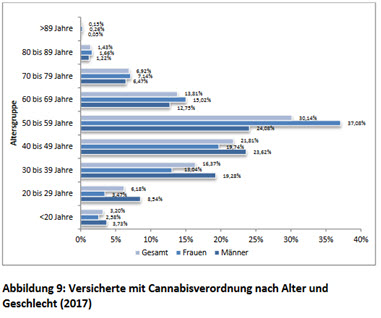
Patient demographics from the report
Most Patients Are Women
This is not exactly surprising in a system where symptomology rather than ability to pay is the driver of authorizations and care. This is also exactly the opposite trend when it comes to gender at least, that emerged in Colorado on the path to medical legalization circa 2010-2014. While chronic pain is still the most common reason for dispensation, the drug is going mostly to women, not men, in their forties, fifties and sixties.
Even Chronically Ill Patients Are Still not Getting Covered
This data is super interesting on the ground for both advocates and those who are now pushing forward on “doctor education” efforts that are springing up everywhere. The only condition for which cannabis was approved 100% was for patients suffering from terminal cancer pain from tumours. In other words, they were also either in hospice or hospital where this kind of drug can be expedited and approved quickly. Other conditions for which the drug was approved were both at far lower rates than might have been expected (see only a 70% approval rate for Epilepsy and a 33% approval rate for Depression).
Conditions and degrees of coverage chart from the report
Expect approval rates to change, particularly for established conditions where the drug clearly helps patients, even if there are still questions about dosing and which form of cannabis works best, along with improved research, data and even patient on boarding.
Also expect interesting data to come out of this market for patients with ADHD (or ADHS).
Imported Cannabis Is Very Expensive
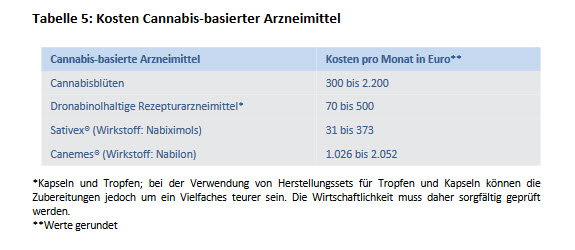
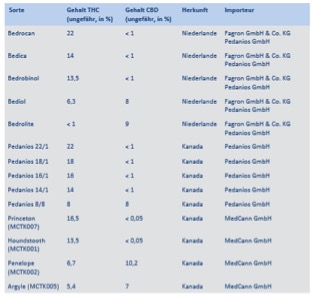
A table showing the different medicines prescribed in Germany
TK and other public health insurers are also on the front lines of another issue not seen in any other legalizing cannabis country at the moment. An eye-wateringly high cost per patient. The biggest reason? Most of the medical cannabis in the market is being imported. This will change when more cannabis begins to enter the market from other EU countries (see Spain, the Baltics and Greece) and, yes, no matter how many elements of the German government are still fighting this one when it begins to be cultivated auf Deutschland.
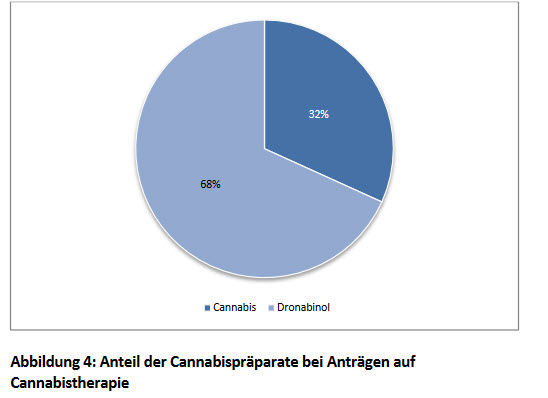
Most German Patients Are Still Only Getting Dronabinol
If there was one thing that foreign investors should take a look at, it is this. One year after legalization, just over 1/3 of those who actually qualify for “medical cannabis” are in fact getting whole plant medication or a derivative (like Sativex).
This means only one thing. The market is continuing to grow exponentially over at least the next five to ten years.
Most German Patients Are Still Only Getting Dronabinol
With the summer season (and recreational reform) fast approaching and the continued growth of the European medical market, Canadian LP Aurora has continued to power forward with another corporate acquisition. This time, the firm is medical cannabis firm MedReleaf (TSE:LEAF). The price? $3.2 billion in stock.
Aurora shareholders will now own 61% of MedReleaf.
The firm has also, of course, solidified its place as a global leader in the cannabis space with production capacity of over 570,000 kilos of cannabis a year.This purchase will absolutely ensure that the company is in a strong position
According to a statement by chief executive Terry Booth, “Our complementary assets, strategic synergies and strong market positioning will provide us with critical mass and an excellent product portfolio in preparation for the adult consumer use market in Canada.”
It also does a bit more than that.
With the German cultivation bid in what appears to be at least a three to six month delay, exports, including from Canada, are the only real way into Europe’s largest cannabis market. And Aurora, with it’s on the ground partner, Pedianos, isright in the middle of it. This purchase will absolutely ensure that the company is in a strong position as the next level of cannabis reform begins to unfold particularly in Europe.
Cannabis Is SO Expensive!
In fact, per this report just produced by one of the leading German public health insurers, Aurora, via Pedianos, and MedCann (the company that became both Spektrum Cannabis and bought out by Canopy Canada), appear to be the two Canadian LPs supplying the vast majority of all reimbursed medical cannabis to German patients. Further the vast majority of product is still coming from Canada – not the satellite grow or production facilities now being built in Portugal (Tilray), Denmark (Aurora and Canopy), Spain (Canopy) or anywhere else in Europe where legal cultivations are being established.
“The Cannabis Report” produced by Techniker Krankenkasse (TK) and the University of Bremen, p.20
However, this also makes for an expensive product here in Germany, land of the generic drug (and where most of them can be bought by consumers, with a prescription, at a regular pharmacy for about $12). In fact, this report was produced in part to underscore the still-evolving medical position on the use of medical cannabis and its efficacy. This highlights how much Germany’s import policy is now costing even public insurers.
What is even more intriguing about the TK report is that the Germans are clearly moving into new research territory. Sure AIDS, chronic pain and muscle spasms (in particular MS) are conditions for which the drug is increasingly being prescribed, but so is ADD. And research studies are now mushrooming around the country.
The Germans have engaged on the medical cannabis efficacy question. And while it is still unclear what doses and of what kind of cannabinoid, have yet to be standardized into protocols, such conversations are well on their way.
And Aurora is also, of course, right in the middle of them.
Another Aurora Acquisition
Given the importance and size of the German market, in particular, it is also no surprise to see another strategic Aurora acquisition coming less than a week after the announcement of this report in Berlin. Specifically, Aurora has also just sunk another 1 million in an investment in CTT– an Ontario-based firm leading the development of thin film wafers that can provide dose specific, smoke free delivery of medical cannabinoids.
The Teutonic cannabis market is clearly in the company’s sights. Not to mention absolutely driving investment and positioning strategy both at home and abroad.
It is old news that Canadian companies are entering the European market. And it is also no stop-the-presses flash that Germany is a big prize in all of this. But there are other Euro markets to watch right now. Switzerland is one of them.
Look for the Canadian influx here too.
One of the more interesting entrants this month? Green Relief – a Canadian LP with a really unique twist. They are the only company in the world to produce cannabis oil from flower grown with aquaponics. This unique method creates unbelievably “clean” cannabis with no pesticides – and no residue of them.
It also sets the company up for a really unique market opportunity on the ground outside Canada. Especially as they have now just announced a partnership with two Swiss companies– Ai Fame GmbH and Ai Lab Swiss AG. Both companies have been leading European pharmaceutical companies since the turn of the century. The idea is to leverage all three company’s intellectual capital with Green Relief’s additional and first international investment with an eye to the entire European cannabis market. Ai Fame specializes in cultivation, manufacturing, sales and distribution to both the food and medical sectors. Ai Lab Swiss AG operates as a laboratory and testing facility.Less than three weeks before Green Relief publicized their European announcement, there were also strategic developments afoot at home.
From this unique perch in the Swiss canton of St Gallen, the three companies are setting up to conquer Europe.
Why Is Switzerland So Strategic?
Switzerland has been on the legalization track since 2011. As of this date, the Swiss government began allowing adults to buy and use CBD-only cannabis. Shops were allowed to obtain licenses. A trickle of sales began. However, rather suddenly, as reform hit Europe, the craze took off. Last year, for the first time, the industry generated a significant amount of revenue (close to $100 million). That is $25 million for the government via taxes- just on CBD sales. Even more intriguing for those looking for market opportunity across borders? Less than a week ago, the German-based budget discount store Lidl just announced they were carrying smokeable CBD – in Swiss grocery stores. The leap across the border is imminent.
That has opened up other conversations, including the “legalize everything” push that makes an awful lot of sense to the ever tax-aware Swiss. This is a push afoot just about everywhere across the continent, including, of course, just across the border in Germany.
The cities of Zurich and the cantons of both Winterthur and St Gallen (home of the Swiss companies behind the new venture with Green Relief) have already indicated that they will not pursue possession fines for those busted with 10 grams or less– no matter what kind and even of the THC variety.
Read between the lines, and it is clear that the cannabinoid conversation locally has begun to attract the Canadians. And not just because of the many opportunities of the Swiss CBD market – but the huge medical and THC German and European opportunities now opening beyond that.
No matter which way Green Relief and their new partners slice it, they are now in the game – and across Europe – with a unique new play and product, and further one set to enter both the medical THC and “consumer,” albeit still CBD, market now burgeoning.
A Cross Market Play
Here is the truly interesting part about this new announcement. Less than three weeks before Green Relief publicized their European announcement, there were also strategic developments afoot at home. Cannabis Growth Opportunity Corporation also just announced an investment in Green Relief. The share purchase agreement netted Green Relief $750,000 in both cash and common shares.
With this, Green Relief seems to have set sail on its European expansion. Look for more interesting turns to this developing saga soon!
In the United States, the idea of transporting cannabidiol (CBD), let alone medical cannabis across state lines is still verboten. As a result, a patchwork of very different state industries has sprung up across the map, with different regulatory mandates everywhere. While it is very clear that California will set the tone for the rest of the United States in the future, that is not a simple conversation. Even in-state and in the present.
In the meantime, of course, federal reform has yet to come. And everywhere else, there is a very different environment developing.
In Canada, “territorial” reform does mean there will be different quality or other regulatory guidelines depending on where you are. The main difference between the territories appears to be at point of retail – at least for now. Notably, recreational dispensaries in the East will be controlled by the government in an ABC package store model. That will not be the case across all provinces however. Look for legal challenges as the rec market gets underway.
In Europe, the conversation is already different – and based on the realities of geopolitics. Europe is a conglomeration of federally governed nation-states rather than more locally administered territories, supposedly under federal leadership and control (as in the US). That said, there is common EU law that also governs forward reform everywhere now, just as it hindered national drug reform until a few years ago on the cannabis front.
However, now, because European countries are also moving towards reform but doing so in very different ways in an environment with open borders, the market here is developing into one of the most potentially fertile (and experienced) ex-im markets for the cannabis plant anywhere. On both the consumer and medical fronts, even though these labels mean different things here than they do elsewhere.
The Drivers
Medical reform in Europe basically opens the conversation to a regulated transfer of both non and fully loaded narcotic product across sovereign national borders. This is already happening even between nation-states where medical (read THC infused) cannabis is not federally legal yet, but it is has been accepted (even as a highly restricted drug). This means that Europe has already begun to see transfer of both consumer and medical product between states. In the former case, this is also regulated under food and cosmetic safety laws.
Cannabis in this environment is “just another drug.”While a lot of this so far has been via the strategic rollout of the big Canadian LPs as they attempt to carve up European cannabis territory dominance and distribution like a game of Risk, it is not limited to the same.
Pharmaceutical distributors across Europe are hip to the fact, now, that the continent’s largest drug market (Germany) has changed the law to cover cannabis under insurance and track its issuance by legal prescription. So is everyone in the non-medical CBD game.
As a result, even mainstream distributors are flocking to the game in a big way. Cannabis in this environment is “just another drug.” If not, even more significantly, a consumer product.
Game Time
The race for Europe is on. And further, in a way that is not being seen anywhere else in the world right now. And not just in pharmacies. When Ritter Sport begins to add cannabis to its famous chocolate (even if for now “just” CBD) for this year’s 4/20 auf Deutschland, you know there is something fundamental and mainstream going on. Lidl – a German discount grocery chain that stretches across Europe, has just introduced CBD-based cannabis edibles – in Switzerland.
As a result of this swift maturation, it is also creating from the beginning a highly professional industry that is essentially just adding cannabis to a list of pharmaceutical products already on a list. Or even just other grocery (or cosmetic) items.
Spektrum, Alcaliber and Canopy are part of some of the larger deals in Europe
In general, and even including CBD, these are also products that are produced somewhere in Europe. As of this year, however, that will include more THC from Portugal, Spain and most certainly Eastern Europe. It will also mean hemp producers from across the continent suddenly have a new market. In many different countries.
This means that the industry itself is far more sophisticated and indeed used to the language and procedures of not only big Euro pharma, but also mainstreamed distribution (straight to pharmacy and even supermarket chains).
It also means, however, understanding the shifting regulations. In general, the focus on ex-im across Europe is also beginning to standardize an industry that has been left out of the global game, on purpose, for the last 100 years. Medical cannabis, grown in Spain under the aegis of Alcaliber (a major existing opioid producer) can enter Germany thanks to the existing partnership with Spektrum and Canopy, who have a medical import license and source cannabis from several parts of Europe at this point. It also means that regular hemp producers, if they can establish the right brand and entry points, have a new opportunity that exists far outside of Switzerland, to create cross-European presence.
And all of this industry regulation is also setting a timeline, if not deadline, on other kinds of reform not seen elsewhere, anywhere, yet.
According to a press release, the Steep Hill team announced they are expanding internationally in a big way on Monday. Steep Hill, a well-known cannabis lab-testing and research company with roots in California, announced plans for licensing agreements in Mexico, Germany, Spain, France, Italy, Switzerland and the United Kingdom.
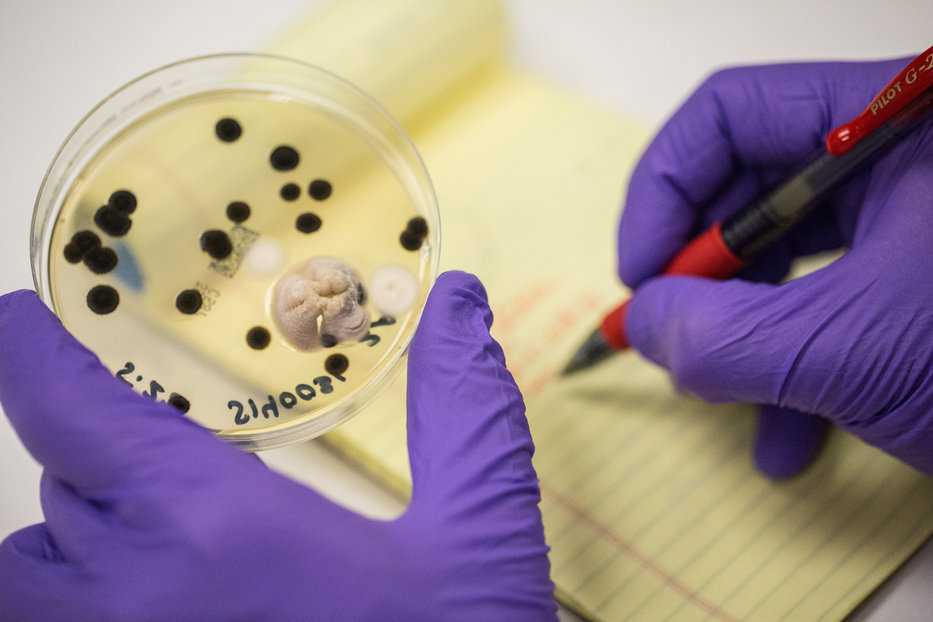
Photo credit: Steep Hill- a petri dish of mold growth from tested cannabis
The Canadian branch of the company, Steep Hill Canada, will lead the expansion efforts into Mexico and the six European Union countries. According to Martin Shefsky, chief executive officer of Steep Hill Worldwide, they are actively looking for other operating partners in new areas as well. “I’m extremely pleased at the opportunity to partner with Steep Hill to bring safe cannabis and scientific integrity to emerging international markets,” says Shefsky. “I anticipate that before long, full legalization will be implemented throughout the European Union and our presence will enable growers, producers, processors, and retailers – to offer standardized tested cannabis for patients and consumers across the European Union, while also enabling us to create a platform to share scientific and technology developments throughout the global cannabis market.”
In 2016, Steep Hill announced new licensing agreements to expand into Washington D.C. and Pennsylvania. In August of 2017, they expanded to Hawaii and several months later announced their expansion into Oregon. “It is an exciting time for us and our investors, as we pursue this first-mover advantage in anticipation of new global cannabis import-export markets,” says Jmîchaeĺe Keller, chief executive officer and chairman of the board of Steep Hill, Inc.
“In unregulated markets, we want to be on the ground supporting the legalization and regulatory process, helping regulators avoid making the mistakes that other jurisdictions have made in the past,” Keller says. “We believe that our role as the industry standard, allows us to leverage our world-class scientific knowledge and state of the art technology to help regulators provide confidence in the marketplace that the cannabis patients consume, is both safe and effective. We look forward to collaborating closely with Martin and his group to strive for this gold standard, across all international borders.”
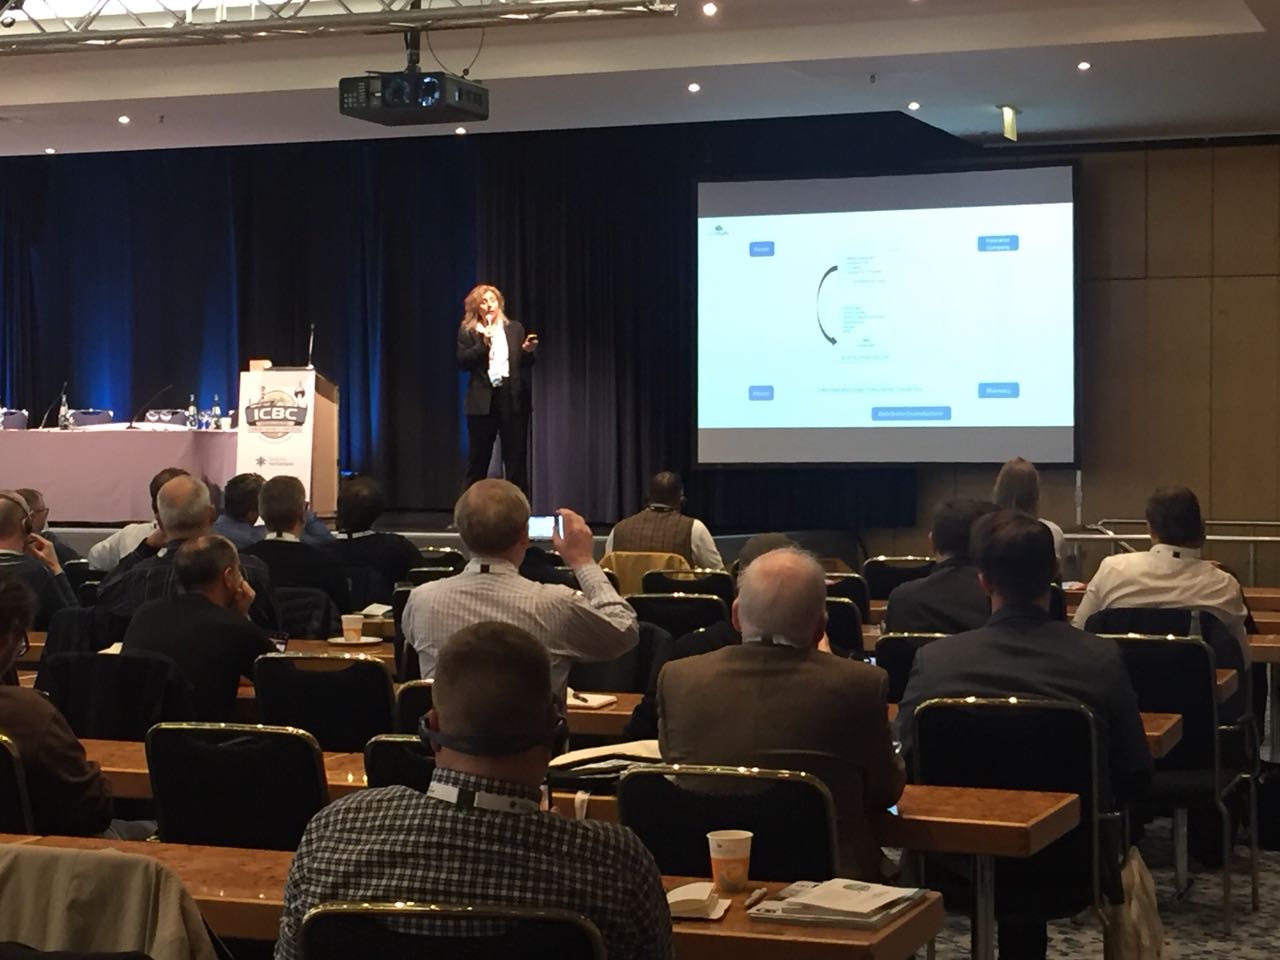
The International Cannabis Business Conference (ICBC) in Berlin is now officially over. The speeches have been made, the parties have been attended. The hard-working crew behind it all has wrapped up, checked out and is off to Vancouver. And most of all, the marathon of meetings and deal discussions that were the mark of this budding and certainly by now established market are done. Even if there are still details to be ironed out in all the new business in the coming months.
As always, the dilemma for conference attendees was how to spend the limited time in this concentrated cannabis gathering. With all of the networking and excitement, people still wanted to hear the experts who spoke on topics ranging from cannabis financing to actually doing business in Germany to new medical advances. Traffic in the expo section was also heavy, as attendees visited the wide range of vendors. Producers and distributors of both plant and derived product were present, along with vape companies brave enough to compete with Storz and Bickel on their own turf, various tech solutions and of course, international consultants.
As the dust clears and the contracts get signed, what are the takeaways from the second edition of the ICBC in Berlin?
Germany Is Going Green
The simplest takeaway? The ICBC Berlin is not a market to be missed in the future for the global cannabis executive. Even if you are an American firm (and for the most part still largely excluded from a rapidly expanding worldwide trade that is establishing itself now with authority), you need to be here. The contacts you make are global, and you do not want to be left out. For foreign investors interested in this market, it is a must. For everyone else, this is a meet and greet, not to mention education, barnone. The German medical and even prosumer CBD market is attracting the world.
Yes, there have been ups and downs even in the last three weeks that include the crashing of the German bid along with news stateside that the Trump Administration is going to hang Jeff Sessions out to dry for Russia with his latest “Make American States Great For Cannabis Again” contortion.
Guenther Weiglein, activist patient, being interviewed in front of MedPayRx booth
But here on the other side of the Atlantic, it is clear that the federal cannabinoid horse has left the barn. There are now rumorsfloating that the bid is not yet entirely dead (now apparently in a legal purgatory of appeals and even potentially “bid amendments”) that nobody is willing to go on record to discuss. Beyond that, however, as was clear from the frenzied deal-makingon the floor and off it at the ICBC, the market is open, distributors are finding new channels to move product, and patients demanding access are not leaving the streets.
Far from it. In fact, the budding nascent umbrella national non-profit campaign designed to open access for patients and educate doctors, The German Patients Roundtable, had a huge second meeting during the conference, with both German and international attendees from countries including Israel and South Africa.
The CBD and THC genie cannot be stuffed back into the local bottle. And everyone knows it. This is federal medical reform, and even better, covered under German national public health insurance. Despite the hiccups and challenges that still remain, this is open blue water for a medical market that has never existed anywhere to date.
Anyone with a GMP facility, Euro cleared export rights and crop or product ready to ship will be welcome here in a market that at this point, cannot get enough plant or oil. Edibles are still a to-come discussion.
To the extent that this is also negative, it is very clear that the market is still highly inefficient. Producers who do have productare not being found by those on the ground who want to sell it to patients. That will also begin to change. But for now, many on the ground are playing a digitalized Rolodex game of “who do you know” that still consists of personal emails between conference-met colleagues if not LinkedIn contacts and impromptu (and freebie) favors. Those who hope to gain an income merely by connecting the source of product and outlets the old fashioned way are also about to be left in the dust by a market that will not be held back and activist businesses who are eyeing both the United States and Canada right now (if not Israel and Australia), and translating all of that into both euros and German.
It is also very clear that the savvy Germans who were largely left out of the bid proceedings last time do not mean to sit this party out – and are angling to get into the game however they can. This is taking some interesting forms, but processing and testing are going to be huge issues of the market here for a long time to come. And so is home-grown, high-quality CBD. The German government is even offering tax credits for growing certain kinds of hempright now. Sound familiar Kentucky?
Trends and Takeaways
It is not just the Canadians who are going to get market share. The Canadian LPs are still in a good position to dominate the early market but it is clear that there is still room for others to enter. Whether the government allows an appeal of the court’s decision to hold up, there is a quick bid “redo” for the top 10 finalists, or a second bid, the market has now arrived and is in its second year.
Marguerite Arnold presents on the impact of blockchain on the cannabis industry
CBD is going to be an important path to other kinds of provision and cultivation. Despite the widespread misconceptions about Germany being a “CBD only” market (it is not), it is clear that a consumer CBD only strategy will be an interesting path into the market here but not one for the faint of heart. The Canadian companies in particular are beginning to move into the realm of big pharma (their market caps certainly are). But it is also clear that more local competition is hip to the same. And as a result, even this part of the market will be a highly competitive one.
German firms are first at this gate, beyond the big Canadian LPs, but they are not the only ones now in the market. See Dutch, Austrian and Swiss firms, many with pharmaceutical company credits and market entry already under their belt. Not to mention producers from both Greece and the Baltics. Everyone on the import side is eyeing the opening market and stalled bid as a fantastic opportunity. Look for products from these locales as testing and certification protocols become more effective.
Central to all of these developments? The conference is theplacefor the global cannabis industry to meet and get to know one another, put together by Alex Rogers and a seasoned, international team behind the ICBC.
In a move that seems to shed more doubt than certainty on domestic cannabis cultivation and the date that it will start auf Deutschland, the Higher Regional Court (or OLG) in Dusseldorf formally stopped the pending bid procedure for the first crop on March 28th. BfArM, the federal agency in charge of regulating all narcotic drugs, initiated that procurement bid. The tender bid was launched after the German Parliament and federal legislators changed the law last year to mandate that cannabis be available via prescription, and further that public health insurers were required to cover it.
That bid announcement was supposed to come as early as last September. Criticisms about the process and requirements began immediately thereafter. For starters, the bid’s requirements excluded all German-only respondents to the bid and left both Canadian and Israeli firms in the front positions to obtain these valuable licenses. However, there were other gripes, including the fact that the amount of cannabis requested (about 6.6 tonnes) was far too low to even begin to meet real demand. Namely, there are easily 1 million German patients who could qualify for the drug.
In the space of the last year, in fact, the number of “official” German cannabinoid patients has shot up from 1,000 to about 15,000. That said, the top three covering insurers also report a mere 64% approval rate. This means that there are more doctors writing prescriptions than insurers are covering.
That, at least for patients and their advocates is a bit of good news despite the blow that any delay in domestic production has created. Doctor resistance to prescribing cannabinoids even when there are no other alternatives has been used as an excuse in many media reports for the speed of market development. That clearly is not true. The attitude on the ground in Deutschland is rapidly changing.
That bid announcement was supposed to come as early as last September. At that point, however,the agency was then forced to extend the response date, which it did, but apparently not for long enough.
Throughout the fall, it was impossible to understand, from any direction, what was going on. Four lawsuits against the bid were launched around September, each with differing complaints that ranged from criticizing the agency for the lack of extension and response time to monopolistic business practices.
The OLG dismissed all but the criticism about the extension.what this decision has done most clearly is slowed down the production of domestically grown medical cannabinoids
The one clear thing to come out of Düsseldorf? BfArM has been banned from awarding its contract to anyone to produce medical cannabis in Germany starting in 2019. The first letters to bid finalists announcing the bid had been canceledbegan arriving the day after the court’s decision.
Reading Between the Lines
There have been rumors since last fall that the bid would end up in such waters. However,all the major producers widely suspected to have applied for the bid also began announcing themselves as finalists in press releases. For this reason, the official line from everyone that the bid was still, in fact, on track.
Nobody could understand why anyone would want or even be able to halt the production of direly needed, locally sourced, high-gradecannabis. That includes BfArM, which made an impassioned response, via their attorney to the OLG in Dusseldorf. Attorney Heike Dahs warned the court that any interruption of the bid was “very bad for the care of patients.” He was similarly pessimistic about the ability to begin production domestically by the previously set 2019 deadline.
In fact, what this decision has done most clearly is slowed down the production of domestically grown medical cannabinoids (although potentially not by much) while giving officials at BfArM a rather nasty black eye that might yet lead to further legal action.
It also means that there will be another bid process. In the meantime, the ex-im market is, if anything, taking off.
This is a Shock And Opportunity – but not a Surprise
No matter the opinionated emails and IM’ing going on in several languages all over the world right now about the implications legally in the future, the major producers are all taking this in stride. And appear to be well positioned to respond.
According to Dr. Pierre Debs, the managing director of Spektrum Cannabis (the global medical brand of Canopy and based just south of Frankfurt), who responded to CannabisIndustryJournal a day after the court decision, the company is not affected by this development. “Spektrum has a steady and constant supply and we do not anticipate any problems supplying patients through their pharmacies,” he says. Debs received the first German medical import license to bring Canadian cannabis into the country a mere two years ago and has continued to carve a leading path in the discussion across Europe. “In addition to our supply from Canopy Growth Corp, our partnership supply agreement with Alcaliber in Spain will see Spektrum importing sun-grown medical cannabis products starting towards the end of the summer,” says Debs.
Dr. Pierre Debs, managing director of Spektrum Cannabis Photo: ICBC, Berlin
But it is not just the big guys in the mix anymore. And there are many who see opportunityto a situation, which is frustrating.“As the second-largest country by population in Europe and a leader within the EU, the German market represents a new frontier for the cannabis industry in general in the region,” says Zlatko Keskovski, chief executive officer of NYSK Holdings, a Macedonian firm now in its second harvest of GMP-certified cannabis and holding EU export rights.
For such firms, even though NYSK is a surprise entrant to the conversation this year and outside the EU, the current situation represents an unbelievable chance to enter a market literally starving for qualifiedproduct. The firm is currently looking for German distributors who cannot access medical grade cannabinoids via other routes including attending the ICBC in Berlin in April. “This year’s ICBC looks to be a seminal moment for NYSK,” says Keskovski. “We have taken the appropriate steps to ensure our high-quality standards have led to products that our customers, and eventually patients, can rely on. We look forward to the chance to showcase our achievements that we’ve worked so hard for. The ICBC will also present us with the opportunity to meet with potential distributors and future partners.”
German Patients are Going to be on the Front Lines of This Discussion
The difficulties that German patients have already faced in obtaining a drug that is now legal in their own country for medical use (and even for recreational purposes across an open border in Holland) are legion. While to a certain extent, German patients are in the same boat as patients elsewhere and their problems, in fact, there are still huge access issues that remain. For starters, the drug is much more expensive here, so those without health insurance approval face bills of about $3,000 per month. Why the eye-watering price? All medical grade cannabis is still imported, although increasingly this is now just via other EU countries, not just from Canada.
“One of the reasons we organized the national German Patient Roundtable is to give patients a voice in all of this supply and demand discussion and to help BfArM and others formulate workable solutions for all,” responded Philip Cenedella IV when reached for a response by CIJ. Cenedella, an American expat and the organizer of the Roundtable, a nationally focussed, umbrella group that is kicking off its campaign this year, spoke for many who are far from court and boardrooms where the decisions are being made.
Philip Cenedella, pictured left, at the Deutsche Hanfverband (DHV) conference in Berlin last November. Photo: @MedPayRx, Instagram
“While there are very talented firms who will now take up this discussion with the government and reissue a response for the tender, what we continue to see on the ground is that patients simply do not have the access granted them in the law which was passed over a year ago,” Cenedella says, with more than a note of frustration. “We again are calling on all government officials, industry executives and patient advocates to band together to immediately establish workable protocols that directly help the patients.”
Indeed, despite the frustration and delay, if not new costs and opportunities that this decision creates, one thing is very clear on the ground here. The current status quo is unacceptable. That alone should also put pressure on the powers that be to remedy the situation as quickly as possible. And via several routes, including widening import quotas or even issuing new licenses as a new solution to domestic cultivation is implemented.
“Patients are not being served and do not have access to a medicine that has been proven to improve lives,” says Cenedella. “Our simple request is for BfArM to finally invite patients into their discussions, to work with patients to formulate workable cultivation and distribution solutions, and we humbly request that this happen now before they go down another dead-end road, ending in another court defeat, and resulting in even more delays to the patients that are still lacking the care afforded them by the German Federal Court’s decision of 2017.”
Disclaimer: Marguerite Arnold has just raised the first funds for her blockchain-based company, MedPayRx in Germany (and via traditional investment funding, not an ICO). She will also be speaking about the impact of blockchain on the cannabis industry in Berlin in April at the International Cannabis Business Conference.
Part I of this series was an overview discussion of blockchain, cryptocurrencies and cannabis and Part II dove into some of the pitfalls of ICOs in the cannabis space. This is the third and final piece of this series.
Beyond raising money or tying a tradable altcoin to cannaproduct, there are many places where blockchain technology can (and will) be used to great effect in the cannabis industry.
In fact, ICOs and cryptocurrency are only part of the blockchain discussion for the cannabis industry. In general, the technology will disrupt the vertical just like it is upending other businesses right now. However, for the moment at least, it will prove most useful in the most complicated and challenging technical and regulatory areas – supply chain product tracking being the lowest hanging fruit (which is still fairly high off the ground for a number of reasons). If evaluating blockchain tech is too onerous (which it usually is for the average investor or even senior cannabis exec), there are other options. Look for innovative mobile DApps (distributed apps that use blockchain for a specific purpose) and smart business cases.
The fascinating reality is that where there are service models that can be adapted to regulatory guidelines, blockchain promises, in fact, to remove the red tape and paperwork holding the industry back internationally. The impact on research and testing will also be huge.The rules are certainly changing with regards to public companies and cannabis.
The technology, or even the regulations, in other words, is not necessarily all to blame for the many issues budding blockchain entrepreneurs currently face. This space-age techie stuff, no matter how mind-blowing, is still “just” a tool. As the late Peter Drucker famously said, the raison d’etre of every successful business is one that solves a critical need for their customer. Find one for the industry that happens to use the technology, and you might just retire early. But there is a lot of road between that reality and now. And there probably will not be an ICO on that path. Not in most jurisdictions, and certainly not without complications in every one of them.
With an internationally stock-listed Canadian cannabis business now developing, the rules are certainly changing with regards to public companies and cannabis. For all the press that Cronos recently received for getting listed on the NASDAQ, AbCann got (relatively quietly) listed in Frankfurt last summer. Canopy and Aurora have also just become two of the hottest stocks in Sweden.
That said, these are public companies with regular stock issuances. What that means for ICO issuances related to the cannabis industry in Canada specifically is anyone’s guess at the moment. In Germany presently, this is mine-strewn territory. But even here, that will be driven as much if not more by banking law than canna-reform, just like everywhere else.
Not to mention this of course: Given the choice of investing in a public cannabis company already in business with its stock conveniently listed and purchasable via a regular exchange, what would most people choose? It’s just a whole lot easier than taking a flier on a cannabis-themed ICO offering for a concept that may be a great idea, but will never materialize. Or find a bank. Even in Europe or Canada.
The End Game Is Rosy Even If The Path Is Unclear
Despite all the caveats, the impact on the cannabis industry of this technology will be large – far beyond finance in other words – and in ways that are not necessarily all understood even now. The potential impacts on research, compliance and even further reform, however, are already clear. And for the most part, potentially very positive.
For that reason, there is no such thing as a blanket “yes” or “no” at any part of this discussion. Regulatory environments regarding both cannabis and blockchain are changing everywhere. Go slow and with caution is the watchword of the day. Look for interesting beta projects and track them.This is a rapidly changing territory in every direction.
Mentioning cannabis and blockchain if not cryptocurrency in the same breath is also legit, now. As little as 2 years ago, the idea or any combination of the two terms in fact, for whatever reason, was widely dismissed as just another iteration of Silk Road.
When combining this technology and cannabis, in other words, expect either amazing results or fantastic explosions that create a lot of heat and noise but go nowhere. There is more room, in other words, for a cannabis.io to become the industry’s NextGen Pets.com than Google or Facebook. That said, there are experiments going on now, in several countries where the banking and insurance questions are being addressed early (Germany, Canada, Australia and Israel all being such locales) where such issues have begun to be addressed up front.
In summary? Stay tuned and watch this space. This is a rapidly changing territory in every direction.
Cannabis pricing, globally, is a topic that is going to remain heated if not highly fluid for some time to come. Why? Government regulation (or lack thereof), compliance and even transport along with different models for commerce and consumption are creating an odd and absolutely uneven map of commodity pricing. We live in a world where accurate information is hard to come by. Even from ostensibly “official” sources that track operational markets. Black or legit.
It may sound complex today but it used to be a lot harder. As of just 2014, the UN’s Office of Drug Control listed the price of a gram of (black market) cannabis in Lichtenstein at $1,020 (as reported by a bemused Business Insider). While this could have been a simple matter of misunderstanding that Europeans frequently use commas rather than periods as decimal points in numbers, the fact that this was later corrected to $10.13 suggests human error in transcription rather than reporting. And the world has certainly changed since then.
Yet with no international legal marketplace or even platform yet in existence to track the global price of legal cannabis in different jurisdictions, this is the kind of issue that faces not only those in the industry but those trying to analyze it.
That said, there are beginning to be data points for those who are interested and those who must have this information for professional reasons. Here is a break-down of regional (legal) prices, per gram from a selection of sources generally considered fairly accurate. This is also made a bit more difficult by the difference in measurement systems and currency fluctuations. For ease of reference, these figures are in grams and U.S. dollars. An ounce is about 28 grams.
Medical grade cannabis also means different things in different markets. Outside the U.S., in Canada and the EU in particular, medical grade cannabis must meet a certification process that adds to the cost of production considerably. Certainly in comparison with outdoor grows. It is still, for the most part, imported, from either Canada or Holland, although look for that to start changing this year as domestic cultivation in multiple countries finally gets seriously underway.
The U.S.
Pricing really depends on where you are. It is also dropping fairly dramatically in established markets. The most recent example of this is Oregon – which has seen its higher-than-normal state retail market begin to normalize with California, Washington and Colorado. This is the price of establishing regulatory schemes on a non-federal level. That said, the competition is so extreme at the moment that Oregon, in particular, is a buyer’s market, with recently reported prices as low as $1 and change for a gram.
Retail pricing, in particular, will remain all over the place on a national level, especially given the amount of local competition between dispensaries underway. On average, however, medical grade-ish cannabis runs between $6-30 a gram, retail.
According to the website Cannabis Benchmarks, which tracks U.S. wholesale prices, the domestic spot index of wholesale cannabis was at $1,292 per pound at the end of January. Or about $5 per gram.The theory that the legit market has to price the black market out of existence is unpopular with those who want to collect more taxes from rec sales.
Nationally, at the moment, uncertainty over how the new post-Cole Memo world will play out, plus oversupply in certain markets, is creating strange pricing. Note to consumers, particularly in recreational markets: There are deals to be had.
Canada
This market is interesting for several reasons. The first is that several of the regional governments are considering establishing a Canadian $10 per gram price for the recreational market. Medical grade runs about $8 at the moment in local currency. That means, with a 20% differential in current f/x rates, a recreational gram will be set at USD $8 and a medical gram at about $6. That said, the theory that the legit market has to price the black market out of existence is unpopular with those who want to collect more taxes from rec sales.
Theories abound about the future of recreational pricing, but for the moment, a great deal of supply and new producers will keep prices low at least through 2019. After that? It is impossible to even guess. At that point, Canadian producers will still be supplying at least German medical patients with some of their imported bud. Regardless, the country will continue to play an important role in global pricing – even if it is to set a recreational and medical standard that plays out in markets already from the EU to Australia.
Israel
Like Canada’s market, although for different reasons, the Israeli official price on legal cannabis is absolutely constant. It is set by government policy. Those who have the drug legally, in other words with a doctor’s prescription, pay about $100 for a month’s supply. That amount on average is about 28 grams. That means that a medical gram in Israel will set you back about $3.50 per. U.S. not Canadian.
Europe
Price deltas here are the most impacted by changing national laws, standards and medical legalization. There are only two semi-legitimate recreational markets at the moment that include THC. Those are Holland and Spain. In Holland, via the coffee shops, the low-end of passable bud starts at between $12-15 per gram and goes up to about $30 for the really exotic breeds. This being Holland, they exist and are obtainable. In Spain, add the cost of joining a social club (about $50), but in general, the cost of a gram is about $10.Price deltas here are the most impacted by changing national laws, standards and medical legalization.
Medical markets in places like Germany are still skewed by integration of the drug into the country’s healthcare system and the fact that it is still all imported. The horror stories are real here. Patients must pay out-of-pocket right now for cannabis flower that is also being pre-ground by local apothekes for an additional price per gram that is eye-wincingly high. However, once the price and supply normalize, look for a medical standard here of about $10 for a month’s supply. That will be about 28 grams too.
Germany, in other words, will eventually be one of the cheapest markets for patients after reimbursement by insurance. That shapes up to be about $0.50 per gram at point of sale. It could be far less for those who are able to obtain authorization for higher amounts up to five ounces per month. The flat fee stays the same. Do the math. That works out to some pretty cheap (high grade) medical relief.
Black market cannabis and hash, which is also far more common in Europe than the U.S. at least, is fairly widely available for between $12 and $20 a gram.
The rise of cannabis production in Eastern Europe and the Baltics (which is also still largely pending and based on ongoing government talks and emerging distribution and cultivation agreements) will also dramatically drive down the cost of legal cannabis in the EU within the next several years. Production in this part of the world, along with Greece, may well also source rec markets all over the continent once that happens.
Africa & Central and South America
While the African cannabis trade has yet to break out – even in the media much of yet, there is definitely something green growing in several African countries including South Africa and Ethiopia. That trade unlike most of what is going on in South America with the possible exception of Uruguay is already looking for export opportunities globally. With African cannabis going for less than a buck a gram in most places (as in about a fifth of even that), look for certified African medical cannabis in select Western markets where price is going to be a major issue. Think medical standards. On the South American front, prices are equally low. However, remember that these are not regulated markets yet. And domestic government standards, starting with GMP and both indoor and outdoor grow requirements are basically non-existent. Growers who want to export to higher regulated markets are planning accordingly.
Assorted Outliers
It goes without saying that in places where cannabis is both illegal and carries the death penalty or other harsh penal retaliation, that the price is not only much higher, but the source is black market. In the UAE for example, a gram will set you back well over $100.
This website uses cookies so that we can provide you with the best user experience possible. Cookie information is stored in your browser and performs functions such as recognising you when you return to our website and helping our team to understand which sections of the website you find most interesting and useful.
Strictly Necessary Cookies
Strictly Necessary Cookie should be enabled at all times so that we can save your preferences for cookie settings.
We use tracking pixels that set your arrival time at our website, this is used as part of our anti-spam and security measures. Disabling this tracking pixel would disable some of our security measures, and is therefore considered necessary for the safe operation of the website. This tracking pixel is cleared from your system when you delete files in your history.
We also use cookies to store your preferences regarding the setting of 3rd Party Cookies.
If you disable this cookie, we will not be able to save your preferences. This means that every time you visit this website you will need to enable or disable cookies again.